Building a financial model for a SaaS startup isn't about making it look pretty.
It's about having a document that doesn't completely fall apart when you try to run a headcount hire plan alongside a 30% annual churn scenario. I've built enough of these to know that the spreadsheet most founders show investors is usually the third or fourth version, cleaned up and missing the parts that made the earlier ones actually useful. A proper model tracks revenue from sign-up to cash collection, accounts for the timing gap between when someone pays and when they're recognized as revenue, and reflects the reality that SaaS companies bleed money on customer acquisition before they ever see positive unit economics. Most first drafts miss the churn mechanics entirely, which means the model shows a steady climb that never happens in practice. The core components are straightforward. You need a subscription revenue engine that calculates Monthly Recurring Revenue based on new logos, expansion revenue, and churn. You need a cost structure that separates fixed costs from variable costs, where variable costs scale with revenue or customer count. Then you layer in headcount, infrastructure, sales commissions, and customer support. The output tells you when you break even, how much cash you need, and what happens if things go wrong.
I learned this the hard way. Two years ago I was building a model for a company that claimed their annual contracts would drive 80% of revenue. The model looked clean until I noticed they hadn't built in a separate churn assumption for annual versus monthly subscribers. Annual customers churned at roughly half the rate. Once I split that out, the CAC payback period stretched from seven months to fourteen. The investor deck changed, but the numbers didn't lie. That was the moment I stopped accepting any revenue projection that didn't explicitly model churn by contract type.
The Revenue Engine Is Where Models Break
SaaS revenue isn't linear. A subscriber signs up mid-month, pays upfront, and you recognize revenue monthly. Churn removes users unpredictably. Upsells happen irregularly. Your model needs to reflect this or it becomes fiction. Set up a monthly time-series layout. Columns for each month going out twelve to twenty-four months. Rows tracking new customers, retained customers, churned customers, expansion revenue, and gross revenue. Calculate net new customers as the difference between new sign-ups and churn. Multiply by average revenue per user to get MRR. Then apply a revenue recognition adjustment for the timing mismatch between cash collection and earned revenue. Here's something most people skip. You should also model the cash flow separately from revenue. Revenue recognition under ASC 606 means you book revenue ratably over the contract term. Cash comes in upfront. That creates a timing difference that matters enormously for runway calculations. A company can show healthy revenue growth while running out of cash because customers are on annual plans and the revenue recognition drag makes the P&L look better than the bank account.
Get the Full Details

I had a founder insist his model was correct because revenue was growing 40% month over month. When I pulled the cash flow statement, his operating cash flow was negative for eighteen consecutive months and projected to stay that way. He'd been pitching the revenue growth line without any mention of cash burn. The model wasn't wrong, it was just incomplete. I added a simple cash conversion section and the whole picture changed. Investors noticed immediately.
Cost Structure and Unit Economics
Your cost assumptions need to be defensible, not optimistic. Infrastructure costs scale differently depending on whether you're paying per-seat, per-request, or flat monthly. Sales commissions are typically paid quarterly or annually and often have accelerators. Customer support headcount usually scales with user count, not revenue. Get these details right or your unit economics will look artificially strong. Gross margin in SaaS typically ranges from seventy to eighty-five percent for established companies. Early-stage models often assume higher margins because they underestimate support and infrastructure costs. This is one of the most common errors. Start with sixty to sixty-five percent gross margin for year one and let it improve as the model reflects actual scaling economics. Customer acquisition cost needs to account for the full sales cycle. If your average deal closes in four months, you're spending sales and marketing money for four months before you see any revenue from that customer. The CAC payback period is calculated by dividing CAC by monthly gross margin contribution. Anything above twelve months is a red flag for most investors. I've seen models claim payback periods of five months for companies with two-person sales teams and no inbound pipeline. That's not realistic.
Churn Is the Silent Killer
Net revenue retention drives valuation more than anything else. Companies with NRR above 120% trade at significant multiples compared to those below 100%. Your model needs to reflect churn realistically, and most founders underestimate how much churn kills compounding growth. Monthly churn of three to five percent is normal for SMB SaaS. Enterprise SaaS typically sees one to three percent monthly churn. If your model shows churn dropping quickly to near zero, that's not credible. Churn stabilizes, it doesn't disappear. Set your churn assumption based on industry benchmarks for your segment, then stress-test what happens if it's two percentage points higher. There's an edge case that trips people up frequently. If you're modeling a freemium or free trial conversion funnel, you need separate churn assumptions for each stage. Free trial users churn at dramatically higher rates than paid subscribers. Conflating these creates an inflated retention picture. I fixed this on a model last year by building a conversion waterfall from trial to paid to upgraded, with churn rates applied at each level. The model's projected Year 2 revenue dropped by thirty-four percent after this adjustment. The founder was unhappy with the number but said thank you when his investor actually asked about it.
Scenario Modeling and What Investors Actually Check
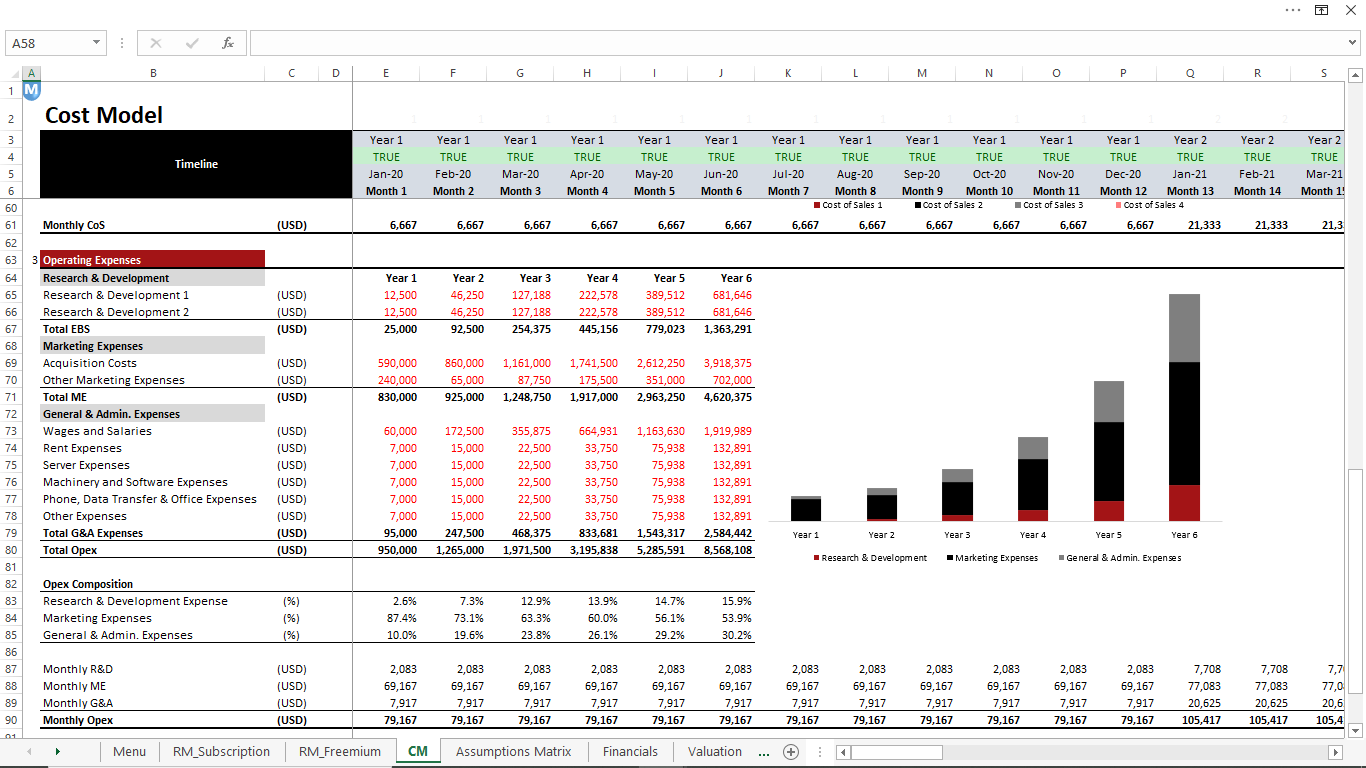
Your model should have at least three scenarios. Base case with realistic assumptions. Downside case with higher churn, slower growth, and longer sales cycles. Upside case is optional but helpful if you need to show stretch potential. Investors rarely look at the upside scenario seriously. They look at downside and base to see if you've thought about what could go wrong. One thing most first-time founders don't build in is hiring ramp. If you need ten salespeople by month eighteen, you can't hire them all in month one. Model the hiring curve with training periods, quota ramp time, and productivity curves. A new rep typically takes six to nine months to reach full productivity. Your model should reflect that lag between headcount spend and revenue contribution. Infrastructure costs are another area where models lie. Cloud costs don't scale linearly with revenue. They scale with usage patterns, storage needs, and architecture decisions. If you're growing fast, your compute costs can spike unexpectedly. Build in a reasonable estimate and include a stress test where infrastructure costs grow faster than revenue for a couple of quarters.
What the Model Can't Tell You
A financial model is a tool, not a crystal ball. It gives you a framework for thinking about your business math, but it cannot predict market shifts, competitive disruption, or execution quality. The best models in the world won't save a product that nobody wants. I've seen founders spend weeks perfecting their model while ignoring the fact that their pricing was wrong or their target market was too small. The model also assumes continuity of current trends. It doesn't account for black swan events. If you're raising money, investors know this. They're more interested in whether you understand your assumptions and can adjust when reality diverges from the plan. A model that's rigid and unchangeable is worse than a model that's obviously approximate but easy to update. Keep the model simple enough that you can revise it monthly with new data. Complexity is the enemy of usefulness. I've reviewed models with hundreds of lines and inputs that took two hours to update. The useful ones took fifteen minutes and had clear assumptions documented in a separate sheet. Update frequency matters more than precision when you're operating in a high-uncertainty environment.
Practical Steps to Build Yours
Start with revenue. Figure out your pricing, your conversion rates, your churn. Build the revenue engine first and make sure it works before adding costs. Then layer in costs in order of impact. Headcount is usually the biggest expense. Infrastructure is next. Then other operating expenses. Build in a separate cash flow statement. Revenue is not cash. Anyone who has run a business knows this, but too many models conflate the two. Track when cash comes in, when it goes out, and what your balance is at each point. Stress test everything. Change your churn assumption by plus or minus two percentage points. Change your CAC by fifty percent. See how sensitive your runway is to each variable. This tells you where your real risks are and what you should focus on managing.
Document every assumption. Write down where each number comes from and what it represents. Five months from now, you won't remember why you assumed seven percent monthly churn. Your investor won't either. Documented assumptions make the model credible and updateable. The model you need depends on your stage. Pre-seed, you're mostly proving the concept with rough numbers. Seed, you need enough detail to show you understand your unit economics and path to profitability. Series A and beyond, the model needs to be granular enough to support board-level discussions about hiring, spend, and growth targets. If you don't have a template to start from, you can build one from scratch or find an open-source option. The important thing is that it reflects your actual business model, not someone else's. A vertical SaaS company with annual contracts has a completely different financial profile than a horizontal product-led growth company with monthly subscriptions and freemium conversion. Match the model to your reality.
Most founders build one model and never touch it again. That's a mistake. Update it monthly with actual results. Compare forecast to actual. The gaps between your assumptions and reality are where you learn what your business actually looks like. The model becomes useful when it stops being a pitch document and starts being a management tool.