Where Most People Go Wrong With Ratio Analysis
Ratio analysis sounds simple in theory. You pull two numbers from a financial statement, divide them, and suddenly you know whether a company is healthy or walking into a wall. The reality is significantly messier. A good ratio can mask a terrible business, and a seemingly ugly ratio can hide a company that's about to turn things around. I've sat through more than one earnings call where the numbers on the spreadsheet looked fine until someone asked the wrong question about working capital timing. The first thing you need to understand is that Financial Ratio Analysis And Interpretation Example isn't about computing a bunch of fractions and hoping something sticks. It's about comparing ratios across three dimensions: over time for the same company, against peer companies in the same industry, and against the company's own historical baseline. Skip any of those and you're just doing arithmetic.
Financial Ratio Analysis And Interpretation Example From Real Data
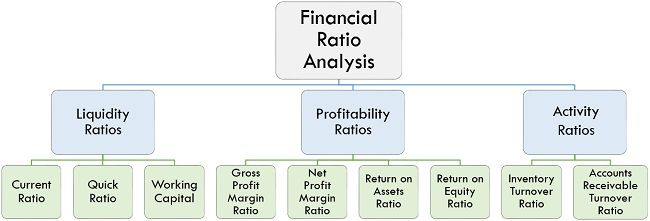
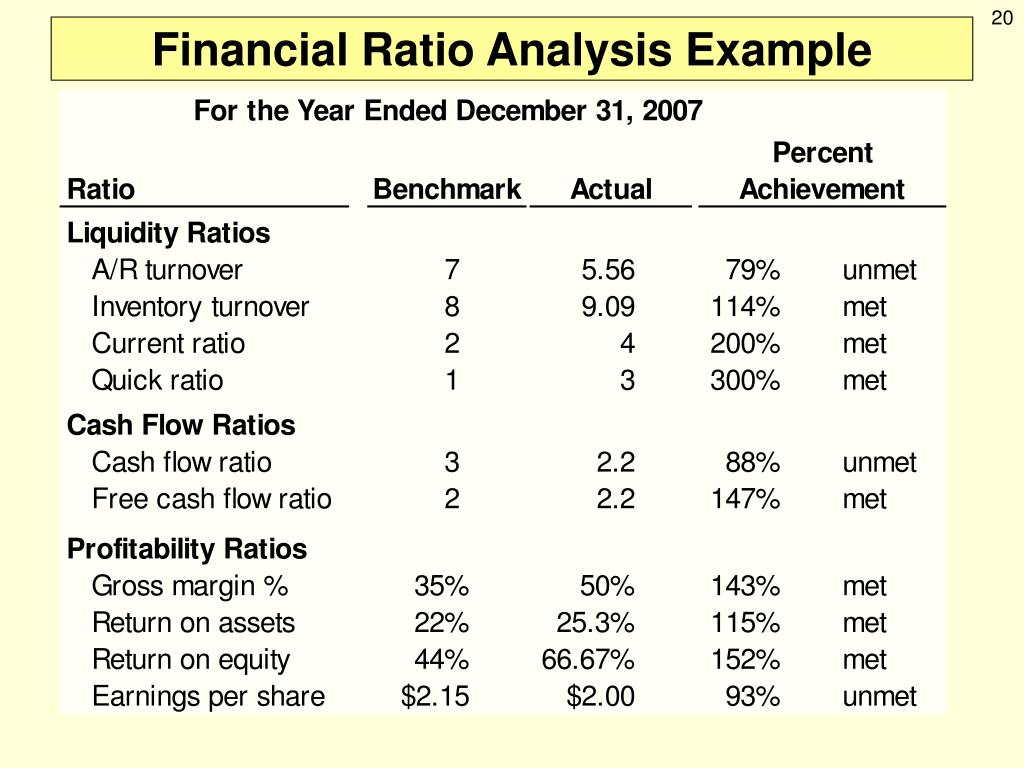
Let me walk through an actual case. I was reviewing a mid-market manufacturing company last year. On paper, the quick ratio looked solid at 1.4, which supposedly means they can cover current liabilities without selling inventory. But when I broke down the quick assets, roughly 40 percent was tied up in receivables from two customers who were 90 days past due. The ratio said one thing. The composition of the numerator said another. That's the kind of detail that separates actual analysis from template-driven spreadsheet work. Here's the breakdown of what I actually computed and why each one mattered: Liquidity ratios — Current ratio and quick ratio are the usual starting points. Current ratio measures whether a company can meet short-term obligations with all current assets. Quick ratio strips out inventory because inventory isn't always convertible to cash quickly. I always look at the inventory turnover alongside these two numbers. If inventory turnover is declining while the quick ratio looks fine, you've got a problem sitting in the warehouse.
Solvency ratios — Debt-to-equity and interest coverage tell you about long-term stability. Debt-to-equity shows how much leverage the company is carrying relative to shareholder capital. Interest coverage shows whether operating earnings can actually service that debt. A company with a low debt-to-equity ratio but declining interest coverage is still in trouble because it's borrowing to stay alive. Profitability ratios — Gross margin, operating margin, and net margin each tell a different story. Gross margin tells you about pricing power and production costs. Operating margin tells you about cost control at the operational level. Net margin tells you the bottom line after everything. When gross margin stays flat but operating margin shrinks, the issue isn't the product — it's overhead creep. When both shrink simultaneously, you've got a pricing problem or a cost problem, and those require very different responses. Efficiency ratios — Asset turnover, receivables turnover, and payable turnover measure how well management uses resources. Asset turnover relates revenue to total assets. A declining asset turnover alongside stable revenue means the company is accumulating assets without generating proportional returns. That's capital misallocation, plain and simple.
Get the Full Details

Market ratios — Price-to-earnings and earnings per share matter for publicly traded companies. These are the least useful in isolation because they're heavily influenced by market sentiment. The PE ratio is almost meaningless without comparing it to the company's growth rate and the industry average. When I explain this to people who are new to the work, I tell them to start with trend data. Pull five years of quarterly ratios for any company you're analyzing. Don't look at a single quarter in isolation. The trend tells you whether management is improving or deteriorating, and trends are harder to manipulate than individual data points. A company can window dress a single quarter by delaying payables or accelerating revenue recognition. They can't fake a five-year trend easily without raising eyebrows auditors and regulators. Here's a counter-intuitive point that beginners consistently miss. A very high return on equity doesn't always mean a company is well-managed. ROE can be artificially inflated through excessive debt. If a company has an ROE of 30 percent but a debt-to-equity ratio of 4.0, that return is leveraged, not organic. DuPont analysis breaks ROE into three components: net profit margin, asset turnover, and equity multiplier. If the equity multiplier is driving the ROE rather than margins or turnover, you're looking at leverage risk, not operational excellence.
Another thing people get wrong is treating industry averages as universal truth. Industry benchmarks exist for a reason, but they're based on median or average companies, not exceptional ones. A company that's truly competitive might look weak against its peers because the peer group is mediocre. I once saw a software company dismissed because its current ratio lagged the SaaS industry average. The average was being dragged down by unprofitable startups burning cash. The company in question had a strong balance sheet and positive free cash flow. The ratio comparison was completely misleading. When I do Financial Ratio Analysis And Interpretation Example for actual investment or credit decisions, I combine ratio analysis with a review of the cash flow statement. Ratios derived from accrual-based income statements can be distorted by non-cash items, accounting policy changes, and one-time charges. The cash flow statement doesn't lie the same way. Free cash flow to equity and free cash flow to firm give you a picture of actual cash generation that net income never will. If net income is growing but operating cash flow is flat, you have earnings quality issues regardless of what the margin ratios say. There are also structural limitations you need to acknowledge. Historical cost accounting means balance sheet values are often stale. Property, plant, and equipment are typically recorded at purchase price minus accumulated depreciation, which has nothing to do with current market value. Intangible assets are frequently understated because internally generated goodwill, brand value, and human capital don't appear on the balance sheet. This makes ratio comparisons across industries particularly unreliable. A tech company and a manufacturing company will look completely different on asset-heavy ratios even if they're equally profitable, simply because their asset bases are fundamentally different in nature.
Seasonal businesses create another headache. A retailer might have a terrible current ratio in November because inventory builds up before the holiday season, then recover dramatically in January. Comparing a November snapshot to an industry annual average is pointless. Always compare quarters to the same quarter in prior years, not to trailing twelve-month aggregates unless the business has no seasonality. If you want a practical workflow that cuts analysis time without sacrificing rigor, here's what I do. I pull the financial statements from SEC filings or the company's investor relations page. I calculate the ratios in a spreadsheet using cell references so changes to the source data cascade automatically. I build a one-page dashboard showing the last eight quarters of each major ratio category alongside the prior year period. I highlight anything that moves more than one standard deviation from the trailing average. That usually surfaces the interesting questions in about fifteen minutes. The deep dive on those questions takes the rest of the time. I also keep a reference sheet of common red flags memorized rather than looking them up every time. Revenue growing faster than receivables is generally good. Receivables growing faster than revenue needs explanation. Inventory growing faster than cost of goods sold is a warning sign. Payables growing faster than inventory suggests the company is financing operations through suppliers rather than its own cash flow. These relationships matter more than any individual ratio threshold.

The interpretation step is where most analyses fall apart. A ratio is just a number until you answer three questions: what is driving it, whether the driver is sustainable, and what it implies for future performance. Take a declining debt-to-equity ratio. That could mean the company is paying down debt, which is positive. It could also mean equity is shrinking due to accumulated losses, which is negative. The direction of the ratio alone doesn't tell you which scenario you're in. You have to dig into the balance sheet components and the income statement to distinguish between deleveraging and deterioration. One final note on tools. There are platforms that claim to automate Financial Ratio Analysis And Interpretation Example end-to-end. Some of them work for screening purposes, but they lack the context sensitivity that comes from actually reading the notes and understanding the business model. Automation is fine for generating a first draft of ratios. It won't catch the fact that a company changed its depreciation method mid-year, or that a significant portion of revenue comes from a related-party transaction that skews your margin calculations. Do the automation for the grunt work. Do the thinking yourself.