The Real Way Dental Practices Handle Equipment and Growth Capital
Dental practices usually finance equipment through a mix of traditional term loans, equipment-specific lending, and sometimes operating leases. The choice depends on whether you're buying a new unit, consolidating debt, or managing cash flow during a buildout. Most practice owners I talk to end up stacking two or three of these together because no single product covers everything cleanly. The equipment loan is the most common path for larger purchases like CBCT scanners, intraoral scanners, or digital X-ray systems. These loans are secured by the equipment itself, which makes lenders more comfortable. You typically put 10 to 20 percent down, and the loan terms run anywhere from 36 to 84 months. Interest rates for well-qualified practices sit somewhere between 6 and 11 percent depending on credit profile and the lender. The key advantage here is that the equipment serves as collateral, so you're not necessarily putting your personal assets on the line beyond the down payment. But equipment loans have a blind spot that catches people off guard. The loan amount almost never covers 100 percent of the purchase price including installation, training, and the ancillary items like cabinetry or electrical upgrades. I had a case last year where a practice was quoted $85,000 for an intraoral scanner. The equipment loan came through for $85,000, but the installation, integration with their existing practice management software, and the mandatory training package ran another $12,000. They were short exactly $12,000 at closing. The workaround was straightforward — they took a small supplemental operating line of credit specifically to cover the gap, then paid it off within 90 days once the scanner started generating revenue. It added about 0.5 percent to their overall cost of capital, which was a reasonable trade-off versus delaying the purchase entirely.
Financing For Dental Practice Options That Actually Make Sense
SBA loans through the 7(a) program are worth considering if you're doing a larger buildout or acquiring an existing practice. The SBA guarantees a portion of the loan, which gets you longer terms and lower rates than conventional business loans. A standard SBA 7(a) for a dental practice might give you 10 to 25 years depending on what you're financing. Equipment gets 10 years. Real estate gets 25 years. Working capital gets 10 to 25 years. The catch is the application timeline. It takes 30 to 60 days from submission to closing, and the paperwork load is heavier than a standard bank loan. You need three years of tax returns, profit and loss statements, a detailed business plan if it's a new practice, and personal financial statements from every owner with 20 percent or more ownership. Operating leases are the other major option and they get a bad reputation from people who don't understand the mechanics. An operating lease isn't a loan. You don't own the equipment at the end of the term. The monthly payment is typically higher than an equipment loan payment for the same asset, but the advantage is that the entire payment is usually deductible as a business expense under Section 179 in the year you place the equipment in service, assuming you meet the income requirements. For practices that are profitable and want to maximize current-year tax deductions, this can be significant. The downside is that you never build equity in the equipment, and at the end of the lease term you're back to square one if you want newer technology. Here's something most practice owners don't know: some dental equipment manufacturers offer captive financing through their own lending arms. KD Dental, Planmeca, Carestream — they all have relationships with third-party lenders who structure deals specifically for their equipment. These can sometimes beat bank rates by 1 to 2 percentage points because the lender has less risk. The equipment is identified, the dealer is established, and the lender already underwrites these deals regularly. But the trade-off is that you're locked into that manufacturer's ecosystem. If you take a Planmeca captive loan and then decide to switch to a different manufacturer's software or peripherals down the line, you may run into compatibility issues that wouldn't exist if you'd financed independently.
Debt consolidation is another angle that comes up frequently. A practice that bought equipment three years ago at 14 percent interest because they were a new business with thinner credit can often refinance those payments into a single lower-rate loan once they've built payment history. I worked with a practice that had four separate piece-of-equipment loans averaging 13.5 percent. They consolidated into one equipment term loan at 7.8 percent. Their monthly payment dropped by about $600 and they shaved two years off the total payoff timeline. The consolidation paid for itself in about four months. The thing nobody tells you about refinancing existing dental equipment debt is the prepayment penalty question. Some of those original loans have clauses that charge 2 to 5 percent of the remaining balance if you pay it off early. Before you shop for a refinance, pull every original loan document and check for those clauses. A $15,000 remaining balance with a 3 percent prepayment penalty means $450 just for the privilege of moving the debt. It changes the math on whether refinancing actually saves you money. Another edge case worth mentioning: revenue-based financing. This isn't traditional debt. A lender gives you a lump sum and you repay it as a percentage of your daily or weekly receivables. For a dental practice with steady insurance collections, this can work because the repayment scales with your actual cash flow. If you have a slow month, your payment is smaller. The rates are higher than equipment loans — usually in the 12 to 18 percent range — but the flexibility can be worth it if you're between equipment purchases and need working capital without locking into a fixed monthly payment that doesn't adjust.
Get the Full Details
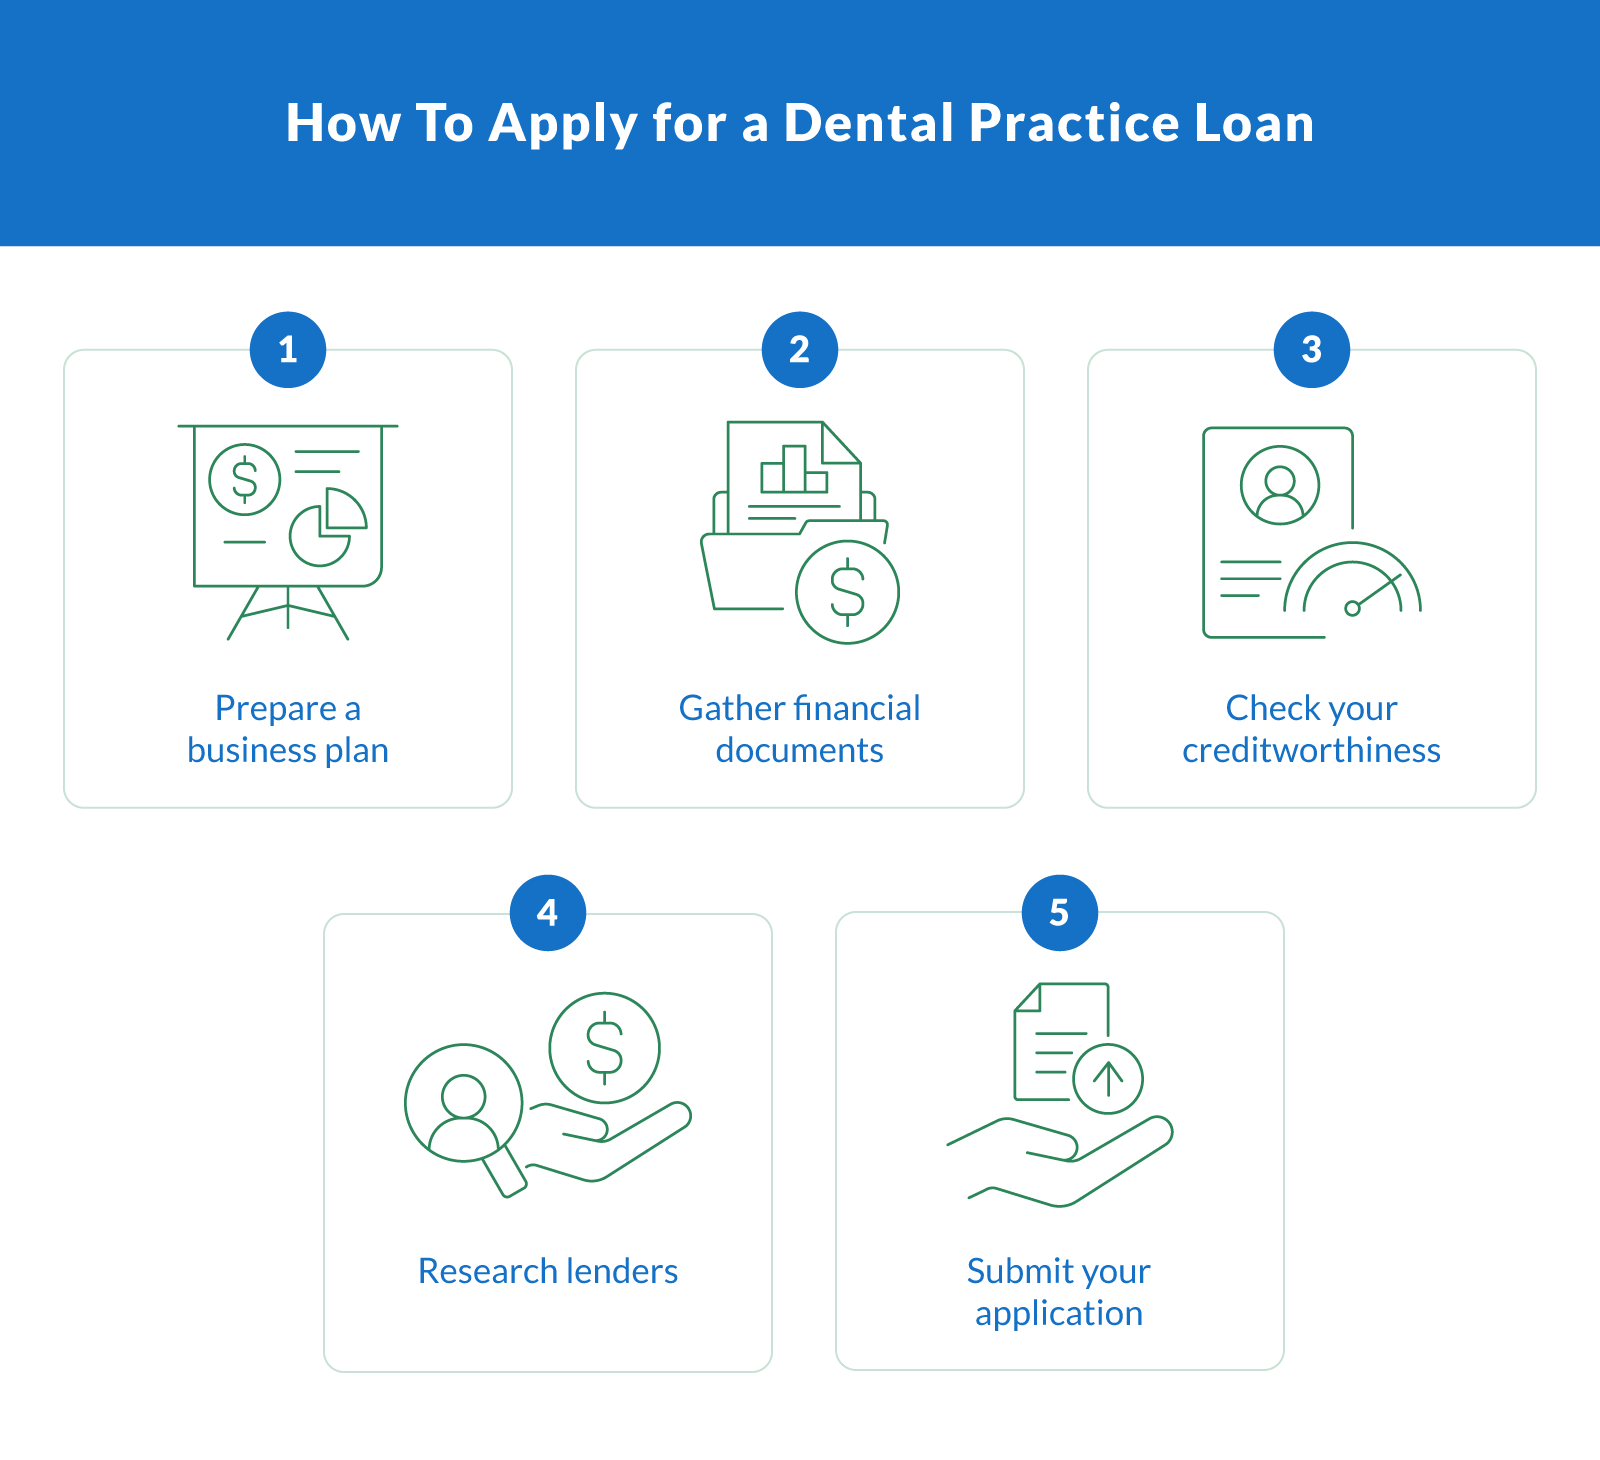
The application process for most dental practice financing follows a similar pattern regardless of the product. Lenders want to see at least two years of practice history, a clean DSO or private practice track record, and personal credit scores above 680 for the best rates. If your credit is in the mid-600s, expect rates to move up 1 to 2 points across the board. If it's below 620, traditional equipment financing becomes very difficult and you'll likely be looking at higher-cost alternatives like merchant cash advances, which I wouldn't recommend unless you have no other path. One practical tip that saves time: gather your documentation before you start applying. A complete application with tax returns, P&L statements, balance sheet, and a list of existing debt goes through underwriting in about half the time compared to an incomplete one. When I've seen applications come back for additional documents after submission, that's usually where the extra two to four weeks come from. Having everything ready upfront — especially recent bank statements and a schedule of existing equipment and loans — makes a measurable difference in how fast you close. The bottom line is that there's no single best financing product for every dental practice. The right choice depends on your credit profile, how much equity you have, whether you want to own or lease the equipment, your current tax situation, and how urgently you need the capital in place. Most successful practice owners combine two or three approaches rather than trying to fit everything into one loan.