Understanding Credit Card Statement Language Is a Mess
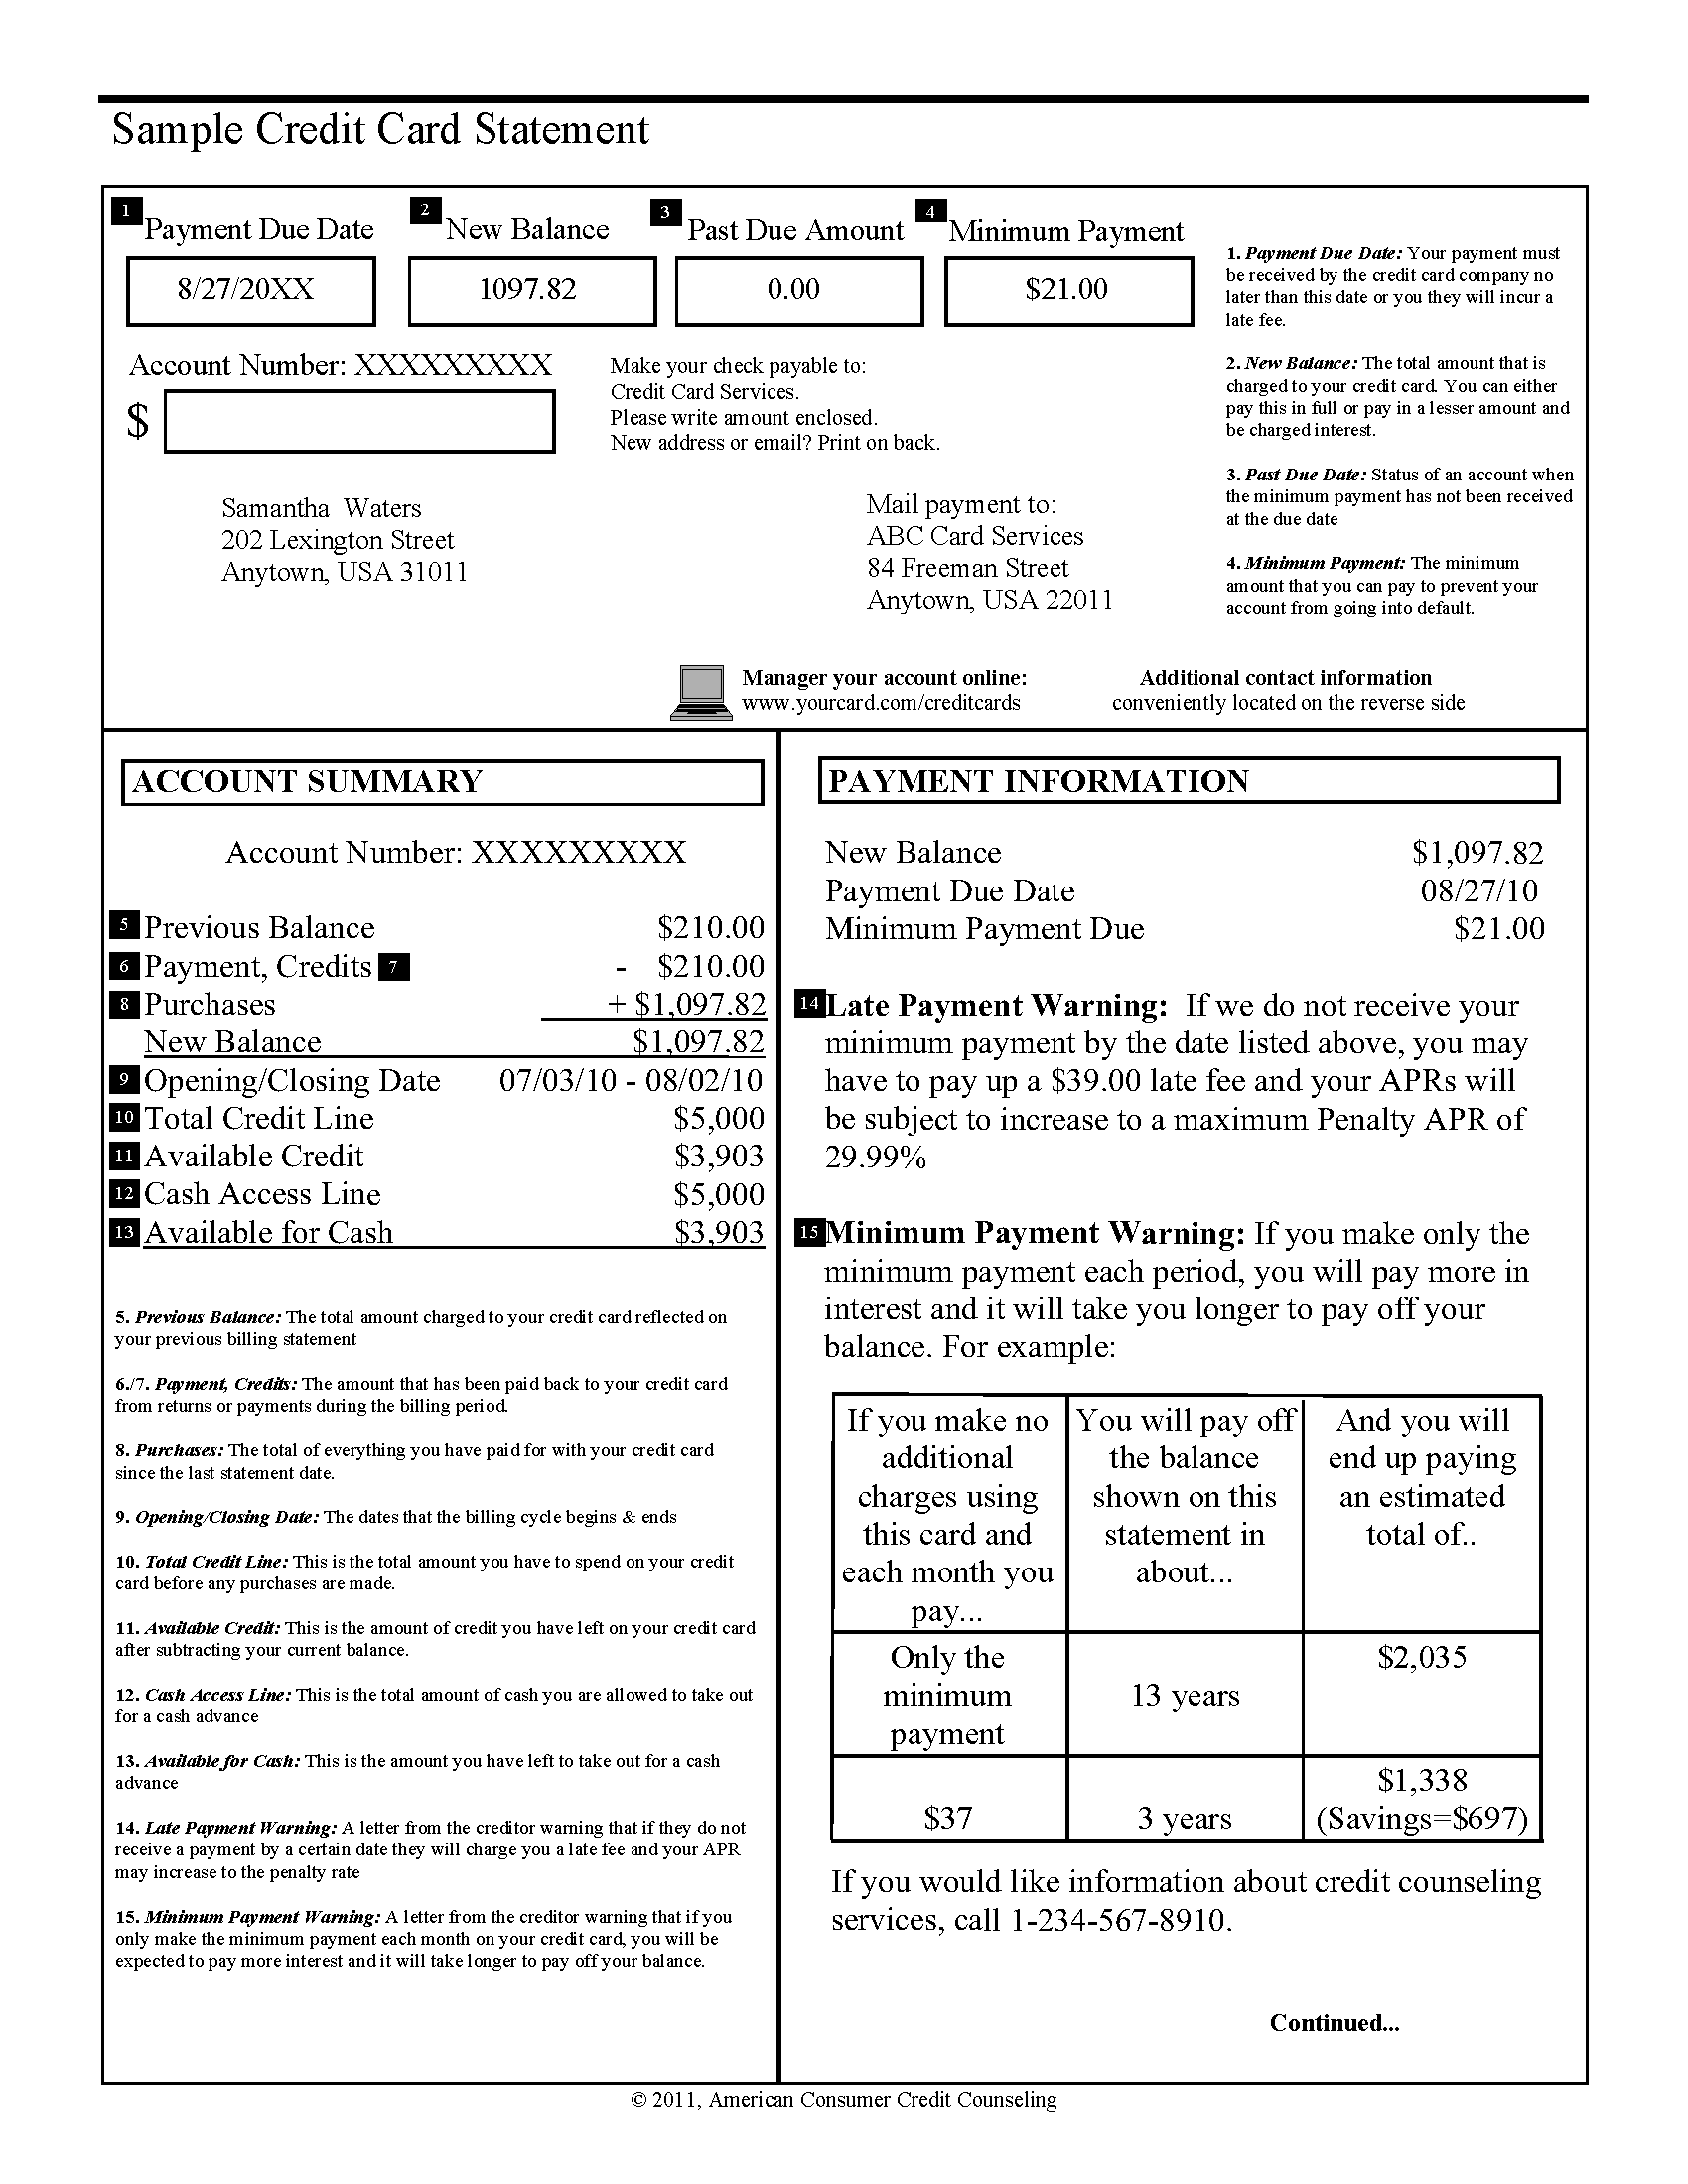
I spent about four years working in consumer financial literacy programs where we regularly ran into people who couldn't parse their own monthly statements. The interest calculations were opaque, the fee structures were deliberately confusing, and most users simply had no framework for reading what they were being charged. That gap is exactly where the Fine Print Credit Card Statement Answer Key came into focus for us. The concept isn't flashy. It's essentially a reference document that maps the standardized language you see on credit card statements to plain explanations of what each line item actually means. The APR disclosure section, the grace period notation, the minimum payment calculation, the late fee triggers — all of that gets decoded into something a person without finance background can act on. Most people never get past the total due number and the minimum payment, which is a problem because that's the least important part of the statement for anyone trying to understand their actual cost of borrowing.
Fine Print Credit Card Statement Answer Key
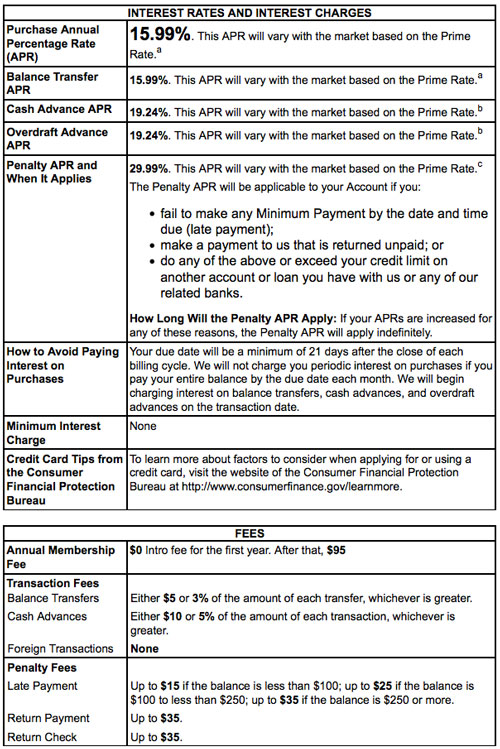
The answer key itself works as a lookup tool. You find a line on your statement, you look it up in the key, and you get a straightforward explanation of what that charge or notation represents. The most useful versions break things down by the standard sections that appear on nearly every American credit card statement: account summary, transaction detail, payment history, fee breakdown, and the regulatory disclosures at the bottom. Here's the thing nobody tells you about using these keys effectively. The legal language on statements is governed by Regulation Z and the Truth in Lending Act, which means there's a lot of standardization across issuers. A 29.99% APR penalty rate triggered by a late payment looks nearly identical whether you're with Chase, Citi, Discover, or Amex. That standardization is what makes an answer key viable at all. If every bank wrote their statements in a completely different format, you'd need a separate key for every single issuer. I remember going through a case last year where a client was being charged what looked like duplicate annual fees on two cards from the same issuer. The statement language for the fee was nearly identical, but one was labeled as a "product change adjustment" and the other as a standard annual fee. The answer key showed both under the same category, but when I dug into the actual cardmember agreement for each product, one of them was a promotional waiver that had expired without proper notification. The answer key got her to the right general area, but the real resolution required pulling the specific terms of each card's agreement. A decent answer key will point you in the right direction, but it won't replace reading the actual contract language when a charge doesn't look right.
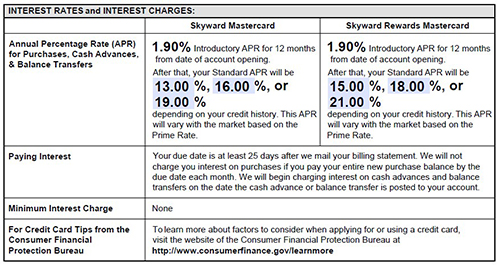
The typical answer key covers about fifteen to twenty common statement line items and notation types. Some of the most confusing ones for consumers are the interest calculation methods. Your statement might show a balance transfer APR, a purchase APR, and a cash advance APR all running simultaneously at different rates, and the payment allocation between them is controlled by the issuer according to the law of largest balance first in some cases, which means a payment might not reduce the highest-interest debt at all. The answer key should flag this clearly. Another area where answer keys fall short is new promotional pricing. Issuers are required to disclose introductory rates, but the expiration language is often buried in small print and worded in ways that make it easy to miss the exact date. One card I reviewed had an intro period that expired on the "first billing cycle after" a certain date, which some customers interpreted as the end of the month containing that date and others as the start of the following month. The statement would show the promotional rate transitioning to the standard rate without any bold warning. A solid answer key would call this out specifically. If you're looking for a download, the most widely circulated versions float around consumer advocacy sites and personal finance blogs. Many universities with financial literacy programs also maintain their own open-source versions. The key is finding one that was updated after the last major change to Regulation Z compliance requirements, which tend to shift every few years. An answer key from 2018 is probably still mostly accurate, but it might not capture newer disclosure requirements that appeared after the 2020 and 2022 regulatory updates.
Get the Full Details

The main limitation you need to accept is that an answer key only explains language, not strategy. It will tell you what a $49 late fee line item means, but it won't optimize your payment timing to avoid one. It will decode the interest calculation method, but it won't help you decide whether to pay off a balance transfer before the promotional period ends. Think of it as a dictionary for credit card statements, not a financial advisor. If you need the strategic layer on top of the explanatory layer, you'd be better off working with a certified credit counselor or using a debt management tool designed for actual payment planning.