How Firefighter Tax Deductions Worksheet Actually Works in Practice
Most firefighters come into tax season thinking they can't deduct much because their gear is provided by the department. That assumption is wrong. The IRS has a specific set of rules for uniform requirements and specialized equipment, and the Firefighter Tax Deductions Worksheet is the tool that helps you organize everything before you file. I built my own version years ago after losing a couple hundred dollars in deductions because I didn't track monthly uniform replacements properly. The core principle here is straightforward. If your employer requires you to wear a uniform or carry specific equipment as a condition of your job, and those items aren't suitable for everyday use outside work, you can deduct them as unreimbursed employee expenses. This used to be a much simpler category before the TCJA changes in 2017 squeezed most employees out of that deduction entirely. Firefighters are one of the few occupational groups that still have a realistic path to claiming these, which is why the worksheet matters.
Building Your Own Firefighter Tax Deductions Worksheet
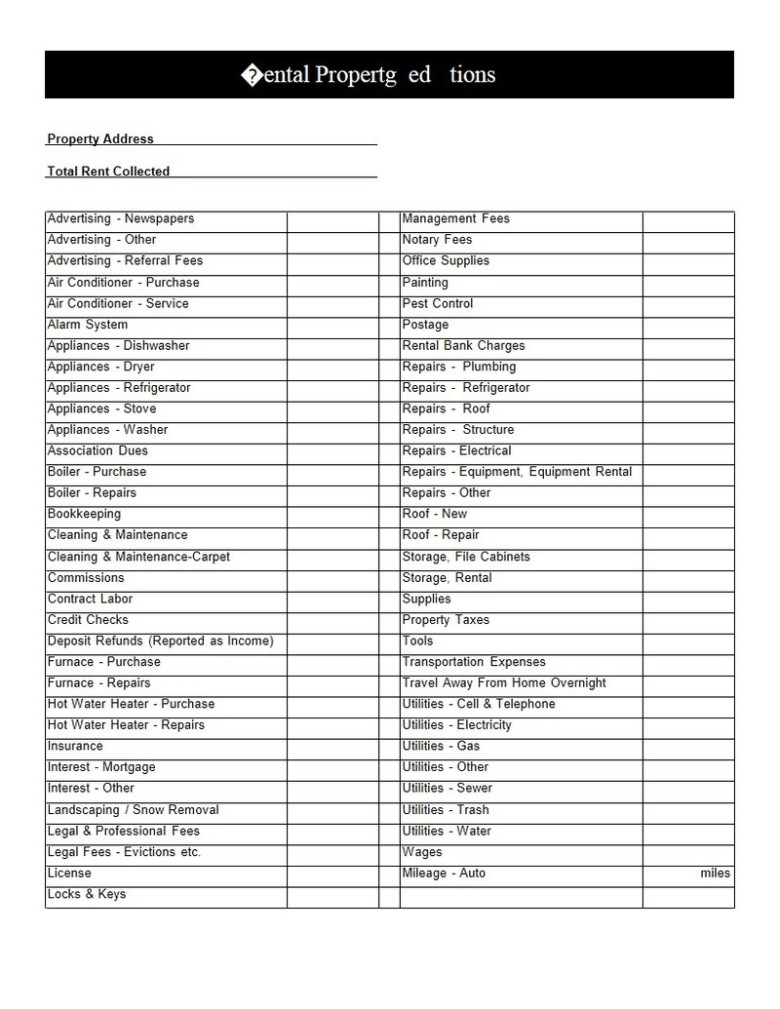
I started with a simple spreadsheet because nothing I found online actually matched the way firefighter expenses work. Most templates were generic or tailored to military personnel, which isn't the same thing. Here is what I ended up with, and it covers the real categories. First, you need a section for uniforms. This includes turnout gear, station uniforms, nominal gear like boots and gloves that replace regular shoes, and any mandatory insignia or patches. Keep receipts organized by quarter. I used to buy everything at the start of the year and then forget which receipt went with which purchase. Now I label everything with the date and department cost center code right away. It takes thirty seconds and saves you three hours in April. The second section is specialized equipment that isn't provided. Some departments issue gear but require you to maintain or replace it yourself. Things like SCBA face pieces, certain radio harnesses, or personal protective clothing add-ons. This is where the nuance sits. The IRS looks at whether the equipment is exclusively for work use. If you ever wear it outside of duty, even accidentally, the deduction gets complicated. I learned this the hard way when I took home a jacket for laundry and the auditor questioned whether it was still exclusively work-related. The workaround was having my department's policy letter on hand that stated all issued gear must be returned to the station after each shift. That policy document made the difference between a denied deduction and an approved one.
The third section covers training and certification expenses. This includes costs for certifications required by your department but not reimbursed. I've seen people miss this entirely because they assume training is always covered. It isn't. Some departments require you to maintain NREMT credentials at your own cost, or pay for specialized technical rescue courses that fall outside standard department funding. Fourth, there is the vehicle portion. If you use your personal vehicle for work-related travel that isn't covered by mileage reimbursement, you can deduct that. This applies to mutual aid responses, certain training locations, and equipment transport. Track this monthly. The IRS standard mileage rate changes every year, so don't rely on last year's numbers. For 2024 it was 67 cents per mile. For 2025 it moved to 70 cents. The difference sounds small until you are tracking eight thousand miles a year. I also added a fifth section for licensing and dues. Professional firefighter association memberships, state licensing fees, and certain exam costs can be deductible if they maintain or improve skills required in your current job. This is different from education that qualifies you for a new trade. A paramedic certification course that makes you eligible for a different job entirely is not deductible. Maintaining your existing EMT certification is.
Get the Full Details
Where People Mess This Up
The biggest mistake I see is mixing personal and work expenses in the same receipt. If you buy boots from a vendor that sells both work boots and casual footwear, you need to note which pair was for work and keep the documentation clear. The IRS doesn't care about good intentions. They care about paper trails. Another common error is forgetting the 2 percent floor. Unreimbursed employee expenses, including the firefighter category, only become deductible once they exceed 2 percent of your adjusted gross income. This is why the worksheet needs to capture everything. A firefighter making seventy thousand dollars has a 2 percent threshold of fourteen hundred dollars. If you only track uniform costs and miss the training, equipment, and vehicle sections, you might come in under that threshold and get nothing. Tracking all categories pushes you over. There is also a timing issue that catches people. If your department changes its uniform policy mid-year, the deduction eligibility can shift. I had a case where a department switched to a fully reimbursed uniform program partway through the year. The months before the change were still deductible. The months after were not. The worksheet needs a date column so you can split expenses by policy period. Without that granularity, you either overclaim or underclaim.
Limitations You Need to Know
Here is the part most guides don't mention clearly. The firefighter tax deduction only works if you are a W-2 employee. If you are an independent contractor or work through a staffing agency in a 1099 capacity, you fall under a different rule set. The self-employed deduction is actually more favorable because it isn't subject to the 2 percent floor, but it comes with different reporting requirements on Schedule C instead of Schedule A. State deductions vary significantly. Some states conform to federal rules on this. Others don't. California, for example, has its own set of rules for public safety employee deductions that may or may not align with what you claim federally. If you live in a non-conforming state, you will likely need to file a state amendment. This adds complexity and usually requires a separate tracking worksheet for state-specific adjustments. The worksheet itself won't solve everything. It is a tracking and organization tool, not a substitute for professional review. If your expenses are substantial, especially with the vehicle and training components, spending a few hundred dollars on a CPA who understands public safety occupations usually pays for itself within the first year. I stopped trying to DIY my own returns after my first audit scare. The peace of mind is worth the fee.