What Actually Goes Into a First Time Home Buyer Worksheet
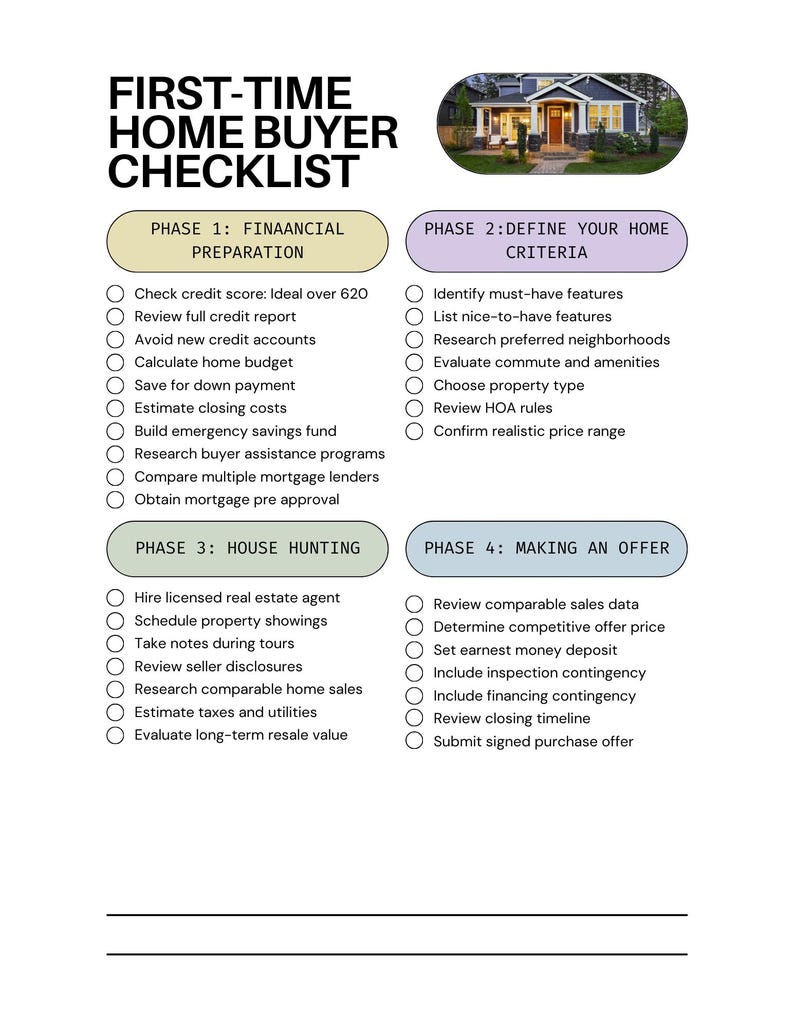
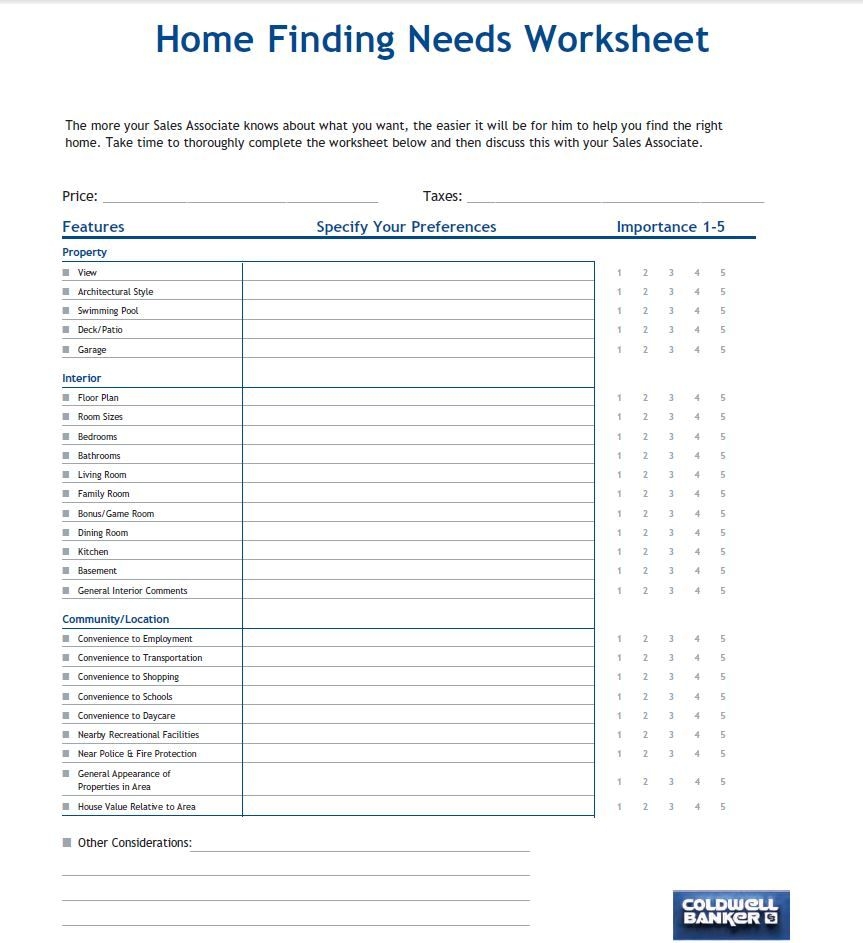
A First Time Home Buyer Worksheet is just a structured way to map out your finances before you start looking at properties. You plug in your income, debt, savings, and estimated closing costs so you know what price range you can actually afford. Without one, most people end up falling in love with a house that their lender would never approve. Start with your gross monthly income. That means everything before taxes come out. If you're salaried, divide by 12. If you're hourly or commission-based, use your average over the last two years, because lenders will ask for that anyway. Then list your monthly debts. Car payments, student loans, minimum credit card balances, child support. Every single one goes here. Next is your down payment. Check your savings accounts, check retirement accounts you might be willing to dip into, and check if you qualify for any assistance programs. Many first-time buyers don't realize they might be eligible for down payment assistance from state or local programs. Your worksheet should have a line for that.
Then calculate your estimated monthly housing payment. Principal and interest based on the price range you're targeting, plus property taxes, homeowners insurance, and if applicable, PMI. PMI is usually required when you put less than twenty percent down and it can add three to four hundred dollars a month to your payment on a typical purchase. Don't skip it. The debt-to-income ratio is where most people get tripped up. Take your total monthly debt payments, add your estimated housing payment, and divide by your gross monthly income. Front-end ratio, housing costs divided by income. Back-end ratio, everything divided by income. Most conventional loans want a back-end ratio below forty-three percent. FHA allows higher sometimes, up to fifty percent depending on the lender and your credit profile. I had a client once who had a surprisingly healthy front-end ratio but her back-end was at forty-six percent because she had two private student loans from graduate school that she'd consolidated into a monthly payment she'd forgotten about. The worksheet caught it before we even looked at a house. We paid one off with a personal loan at a lower rate and dropped her DTI to forty-one. She qualified for a better rate and avoided the FHA requirement.
Common Mistakes People Make
People tend to overestimate their affordability. They plug in the maximum mortgage a lender might pre-approve them for and assume that's what they can comfortably pay. It's not. Comfortable is usually twenty-eight percent of gross income going toward housing. Everything above that and you're stretching thin. Another mistake is ignoring closing costs. They run two to five percent of the purchase price. On a three hundred thousand dollar home, that's six to fifteen thousand dollars on top of your down payment. Some first-time buyer programs help with this but you need to know about it early and your worksheet should account for it. People also forget about post-closing expenses. Moving costs, immediate repairs, furniture, utilities deposits. Buy the house and show up with an empty place and no cash left. Happens more often than you'd think.
Get the Full Details
Using Your Worksheet After You Find a House
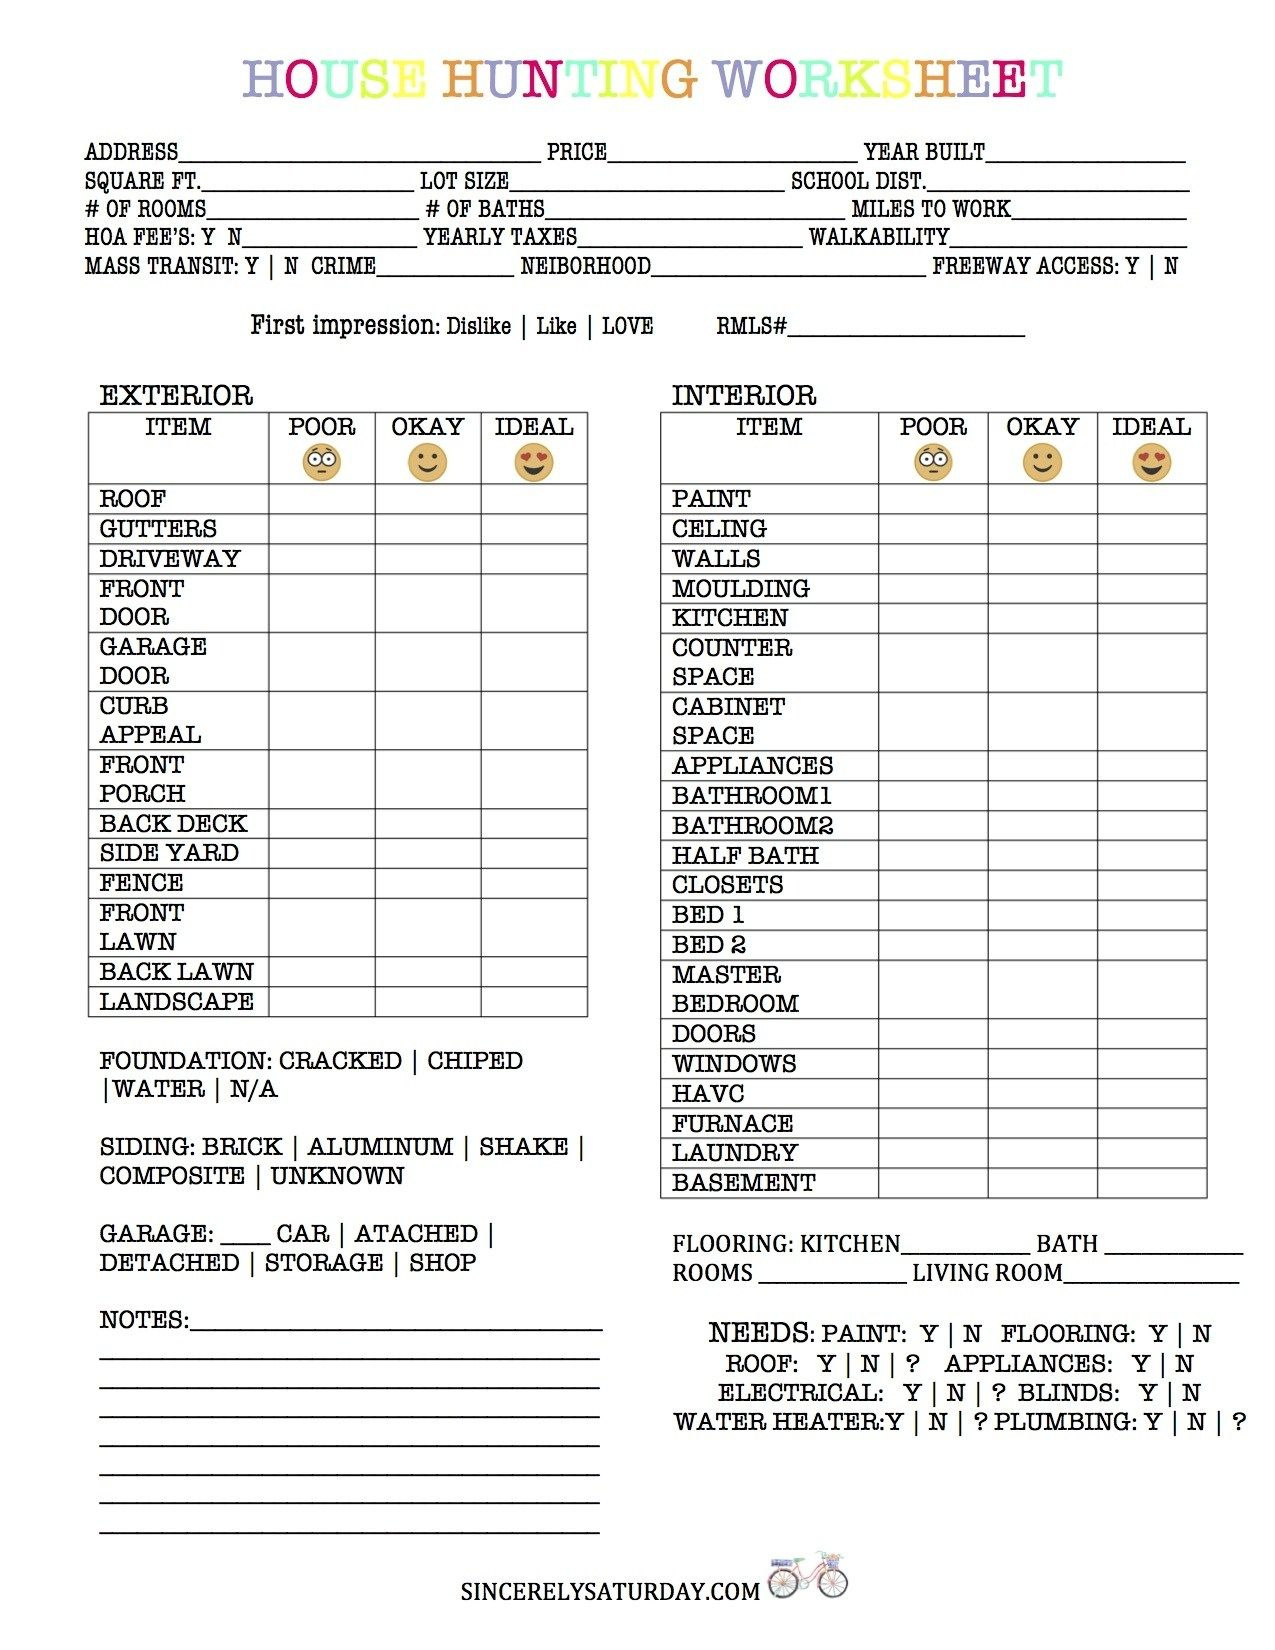
Your worksheet isn't a one-time thing. When you find a property, plug in the actual numbers. Updated property tax figure from the listing or assessor's office. Different HOA fees than you assumed. The interest rate your lender quotes you might differ from what you estimated. Adjust and see if the numbers still work. If the new numbers push your DTI above your comfort zone or the monthly payment eats more than thirty percent of your income, walk away from that property. There are other houses. A worksheet that tells you no is worth more than one that tells you yes when the lender later denies you. I learned this the hard way early on. A buyer I worked with fell in love with a fixer-upper in a good school district. The numbers on her original worksheet said she could afford it. The inspection revealed structural issues that would cost twenty thousand dollars minimum. We recalculated everything, factored in the repair estimate, and the house went from comfortable to impossible in an afternoon. She moved on and bought something else three months later at a price that actually fit.
Where to Get a Ready-Made Worksheet
You don't need to build this from scratch. Many lenders offer a First Time Home Buyer Worksheet as part of their pre-approval process. The HUD website has templates. State housing finance agencies often provide their own versions tailored to local assistance programs. A basic spreadsheet works fine if you're comfortable managing it yourself. The key is consistency. Use the same worksheet throughout the entire process so changes are easy to track. If your income shifts, your debts change, or interest rates move, update it immediately rather than hoping the old numbers still apply. There's a limit to how useful any worksheet is on its own. It can't predict job loss, medical emergencies, or major car repairs. It gives you a snapshot, not a crystal ball. That's why I always tell people to keep an emergency fund separate from your down payment and closing cost savings. Six months of expenses ideally, three months minimum if you're already pushing your budget. The worksheet won't protect you from bad luck but having a cushion does.
Download a template, fill it out honestly, and treat it like a living document. That's all it takes to stop guessing and start knowing what you can actually afford.