Form 3520 and the headaches that come with it
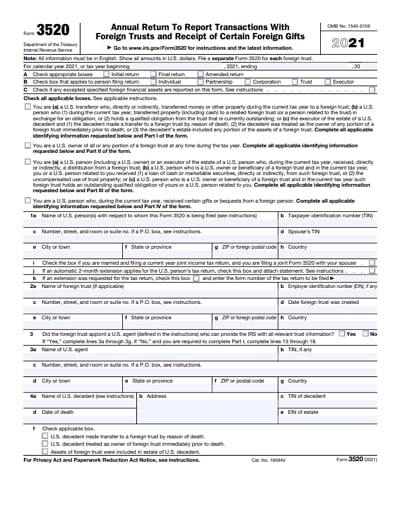
Most people who end up needing to file this form have no idea what triggered the requirement until they see the instructions. The IRS calls it the "Annual Return of U.S. Trusts and Foreign Trusts." You file it when you are a U.S. person who has some kind of relationship with a foreign trust — as a grantor, a beneficiary, or sometimes just the person who transferred money into one. The instructions lay out who falls into each bucket. Part III is where the breakdown lives: it maps out each trigger event and tells you what information to report.The form itself is deceptively simple. It is six pages, mostly boxes and lines. The real problem is figuring out whether you actually have to file it in the first place. I spent most of 2022 untangling a situation where a client inherited from an uncle in Mexico. That uncle had a fideicomiso — a Mexican bank trust, not a common-law trust. The instructions are vague on whether a fideicomiso counts. The instructions reference "foreign trust" and you can argue either way if you are skimming. I ended up calling the IRS international taxpayer hotline, transcribing the rep's response, and attaching a memo to the return explaining why I treated it as a foreign trust. That was the correct call, but only after the 45-minute hold and the back-and-forth. The official document sits on IRS.gov under "Instructions for Form 3520." Look for the revision date near the top — 2021 versions typically show a June or July update. PDF only, no interactive filling. If a site is selling you a fillable version, skip it. The instructions are static text. What changes between years is mostly the dollar thresholds and the penalty discussion language. For 2021 specifically, the key thresholds are:
- Part I: Report gifts and bequests from nonresident aliens and foreign estates over $100,000.
- Part II: Report transfers from foreign corporations or gifts/ bequests from foreign persons, plus foreign trust distributions.
- Part III: Foreign trust activities, including grantor trusts and significant U.S. owners.
- Part IV: Acquisition or disposition of foreign real property.
If your total reportable gifts from a foreign person exceed $100,000 in a single year, you file under Part I and you need to file by the due date of your tax return, including extensions. If you do not have an extension, April 15th applies. With an extension, October 15th. The penalty provisions apply regardless. The deadline confusion is the single biggest source of penalties. Form 3520 is due with your individual return. But it has its own penalty structure separate from the failure-to-file penalty for Form 1040. The penalty for not filing Form 3520 when required can reach 25 percent of the gross reportable distribution or the FMV of the transferred property. For foreign gift reporting, it is 25 percent of the reported amount, up to a cap in certain cases. These penalties accrue even if you have no tax liability on the transactions themselves. I worked on a case last year where a CPA missed the foreign trust distribution reporting because the client received funds from a Cayman Islands discretionary trust. The trustee did not issue a 1099 or any IRS information return. The CPA argued that without a statement, there was nothing to report. That argument does not hold water under the instructions. The instructions say you must report foreign trust distributions if you are a U.S. beneficiary, even if no paperwork was generated. I had the client reconstruct receipts, bank deposits, and the trust's annual reports from the trustee's website. It took three weeks and a lot of phone calls, but it beat the alternative of ignoring it. The IRS has been matching FBAR data to 3520 filings in certain audits.
Part I vs. Part II: the boundary most people miss
Part I covers gifts and bequests from foreign individuals and foreign estates. Part II covers distributions from foreign trusts and gifts from foreign corporations. The line between the two is blurrier than the form makes it look. A payment from a foreign trust to a U.S. beneficiary can sometimes be characterized as a gift from the grantor if the grantor is a foreign person, or it can be a trust distribution. The instructions give you examples, but the examples assume you already understand the classification rules in Pub 559 and the foreign trust sections of the Code. If you are not comfortable distinguishing them, you will misfile. Here is a practical rule: if the money came from a trust that the U.S. person created or funded, that goes into Part III, not Part I. If the money came from a foreign trust where the U.S. person is a beneficiary and did not create it, that is a Part II distribution. If the money is a outright gift from a foreign individual with no trust layer, that is Part I. I keep a small decision tree on my desk because I do not want to re-derive this every April.
Get the Full Details

Foreign grantor trusts and the Section 679 trap
This is where things get technical fast. Under Section 679 of the Internal Revenue Code, a U.S. person who transfers money or property to a foreign trust is generally treated as the owner of the trust for U.S. tax purposes, unless an exception applies. The most common exception is the gift exception: if you transfer property as a bona fide gift, you may not be treated as the owner. The instructions walk through this, but they do not explain how to prove the gift exception in practice. I once had a client transfer $2 million into a Puerto Rican trust thinking that because Puerto Rico is U.S. territory, the trust was domestic. It is not. The instructions call out that a trust created in Puerto Rico is treated as a foreign trust for these purposes. The client had been filing Form 1040 with no trust disclosures for four years. When we caught it, we prepared a amended return and filed Forms 3520 retroactively. The penalty exposure was significant, but the voluntary disclosure posture helped. The IRS was more concerned with the lack of pattern fraud than the mistake itself.
Specific instructions breakdown
The 2021 instructions are organized by part. Here is what each part requires in plain terms: Report aggregate gifts and bequests from nonresident aliens and foreign estates that exceed $100,000 in the tax year. You must include the name, address, and taxpayer identification number of the donor if known. If the donor is a foreign trust, you also need to indicate whether the donor is treated as a foreign person under the grantor trust rules. Line-by-line, you list each donor separately. If you have multiple donors who are related, the $100,000 threshold applies per donor, not across the board, unless the instructions specify aggregation. They do not in this section. You report distributions from foreign trusts and gifts from foreign corporations here. If you received money from a foreign trust during the year, you report the amount and indicate whether the trust is a grantor trust, a non-grantor trust, or a disqualified trust. The distinction matters for penalty calculation and for determining whether you need to attach Schedule B. The instructions require you to attach a statement if you do not know the trust's EIN or identifying number. You can estimate, but estimation without documentation invites scrutiny.
This is the densest section. If you are the grantor of a foreign trust, you report the transfer of assets, the fair market value at transfer, and whether you are treated as the owner under Section 679. If you are a beneficiary who is also a significant U.S. owner, you report distributions and the cumulative distributions. The instructions ask for the trust's employer identification number, which is often unavailable if the trust never applied for one. In that case, you provide the name and address of the trust and explain why the number is missing. Attach a signed statement. There is also a line about Form 3520-A. If the foreign trust is a U.S. person-owned foreign trust, the trust itself must file Form 3520-A. You must indicate whether that form was filed and attach a copy if required. This is where many filers drop the ball. I have seen returns with Part III filled out but no Form 3520-A attached, and the IRS returns those as incomplete. Fixing that later costs more time than doing it right the first time.
Part IV — Foreign real property transactions
Part IV is less commonly relevant. It asks about acquisitions and dispositions of foreign real property by U.S. persons in connection with certain foreign corporations or partnerships. The instructions are narrow. Most individual filers will leave this blank. If you are a U.S. person who purchased property in Canada through a non-U.S. corporation, check whether that corporation is a foreign corporation under the instructions. It usually is. But the real trigger is the ownership threshold, and that detail belongs in a separate analysis. The instructions summarize it in one paragraph because that is all they can fit on the page. The penalty language in the instructions is not sugarcoated. Failure to file Form 3520 can result in a penalty of 25 percent of the gross reportable distribution or the FMV of the transferred property. For foreign gift reporting, the penalty is 25 percent of the amount required to be reported, with a maximum penalty cap in some cases. The instructions note that reasonable cause and not willful neglect may excuse the penalty. "Reasonable cause" is the standard phrase. The IRS evaluates it based on the totality of circumstances, including whether you sought professional advice, whether you acted promptly once you became aware, and whether the omission was isolated. I have seen penalties abated when the taxpayer provided evidence of a qualified CPA preparing the return and relying in good faith on that advice. I have also seen penalties upheld when the same CPA missed the filing entirely and the taxpayer ignored repeated notices. The difference is usually whether the taxpayer engaged with the IRS after receiving correspondence. If you get a penalty notice, respond with a written statement and supporting documentation. Do not ignore it. The instructions do not say that explicitly, but the practice patterns make it clear.
A workaround for the foreign trust EIN problem
Many foreign trusts do not have a U.S. EIN. The instructions tell you to enter "N/A" and attach a statement. I stopped using "N/A" a few years ago. Instead, I enter the trust's foreign registration number or tax identification number from its jurisdiction and attach a signed declaration that no U.S. EIN was issued. The IRS accepts this far more consistently than the "N/A" approach. It takes about five minutes to draft the declaration and longer to get the trust's registering authority to confirm the number. The extra documentation prevents a follow-up request that would delay processing by weeks. The instructions are not the only document you should rely on. Pub 559, "Survivors, Executors, and Administrators," covers foreign trust basics. Rev. Proc. 2020-17 and Rev. Proc. 2021-24 provide safe harbor procedures for late filings. If you missed a deadline or did not file in prior years, those revenue procedures are useful. They allow you to submit a statement and amend without triggering immediate penalty enforcement, provided you meet the conditions. The conditions are strict. You must show that the failure was due to reasonable cause and not willful neglect. You must provide all required information. You must sign a declaration under penalties of perjury. The instructions mention reasonable cause but do not detail the safe harbor. You need to look elsewhere for that. Another common mistake is mixing up Form 3520 and FBAR. They are separate. FBAR is FinCEN Form 114, filed with the Treasury Department, and it reports foreign financial accounts. Form 3520 is filed with the IRS and reports foreign trust and gift activity. A foreign trust account may trigger both. The instructions assume you know this distinction. They do not spell it out. I have seen people file FBAR instead of Form 3520 and wonder why they got a penalty notice. The filing venues are different. The penalties are different. The information requirements overlap only partially.
How long it actually takes
If you have straightforward foreign gift reporting and the donors have U.S. TINs or you can easily obtain them, Form 3520 takes about 45 minutes to complete. If you are dealing with a foreign trust that has no EIN, no Schedule K-1 equivalent, and a trustee who is unresponsive, it can take several days of research. I average about 2 to 3 hours per return in normal years, and 6 to 8 hours when the trust documentation is sparse. The bottleneck is almost always the trust information, not the form itself.
Final note on accuracy
The instructions I referenced are the 2021 revision. If you are filing now, check whether the IRS has released a newer revision. The 2022 and 2023 instructions added clarifications around digital asset holdings in foreign trusts and updated the penalty safe harbor references. If your facts are from 2021, use the 2021 instructions. If your facts span multiple years, you may need to file multiple versions. The instructions do not address multi-year consistency, but the IRS expects it. File what is required for each year and keep the versions labeled clearly.