What Form 926 Actually Is
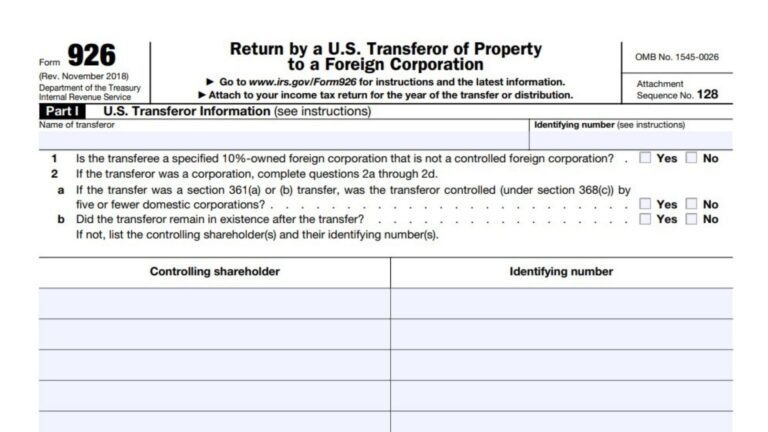
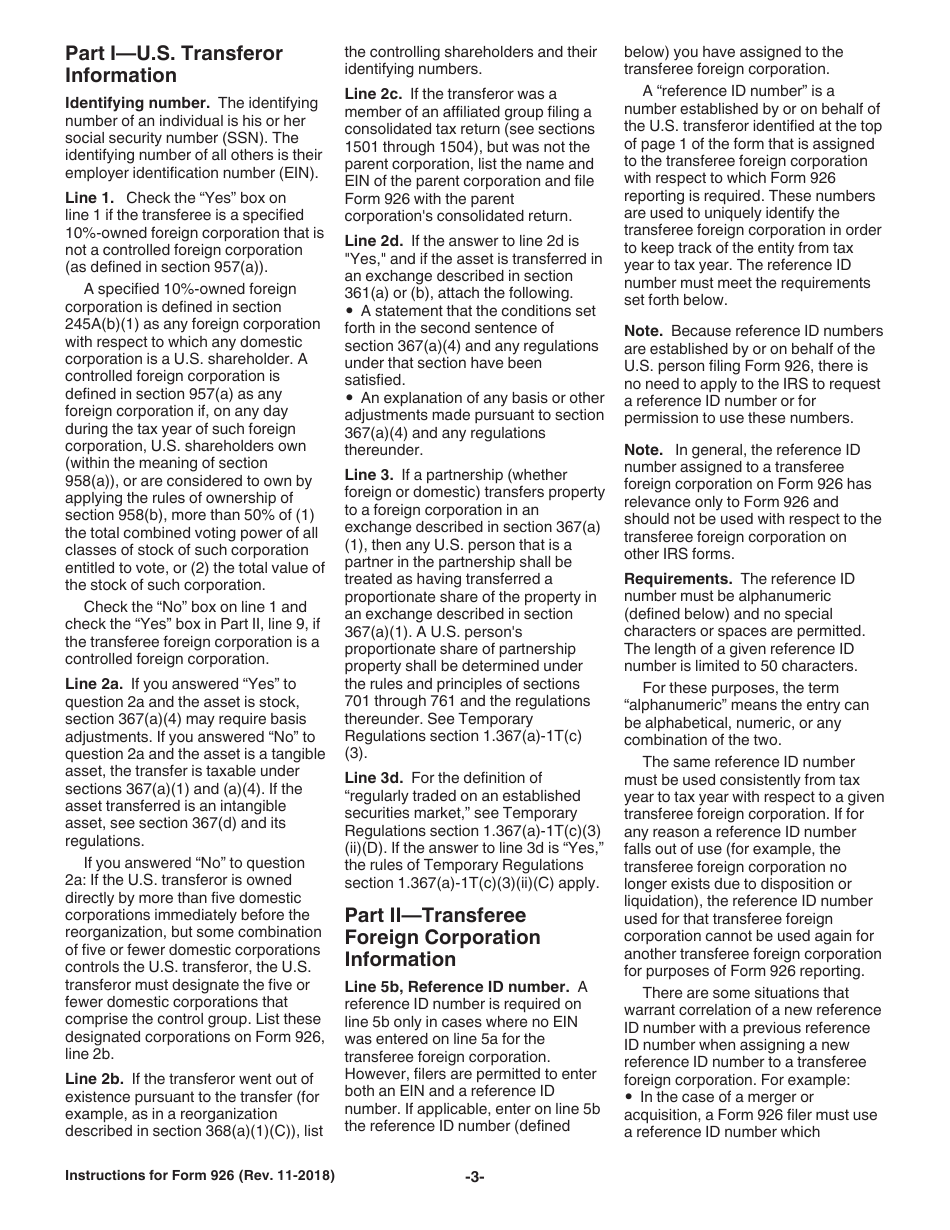
Form 926 is the IRS document you file when you transfer property to a foreign corporation. It triggers under Section 367 of the tax code. The form exists because the government wants to track outbound asset movements that could shift income overseas without proper reporting. You need to file it alongside your individual or corporate tax return for the year of the transfer. The official instructions live on IRS.gov. Go to the Forms & Publications section and search for "Form 926." You can download the PDF directly. The instructions document walks you through each line item, what counts as property, how to value the transfer, and the attestation requirements. Keep a copy of the full instructions on file — you'll need it when you fill out the form itself, not just the summary sheet. The actual form is two pages. The instructions are roughly forty pages. That length exists because the edge cases are brutal and the IRS wants to leave no ambiguity about what qualifies as a reportable transfer.
Who Has to File
If you're a U.S. person — that means a citizen, resident alien, domestic partnership, domestic corporation, or any estate or trust not classified as a foreign entity — and you transfer property to a foreign corporation in exchange for stock or a partnership interest, you file Form 926. The transfer can happen in a single transaction or across a series of related transactions. The IRS aggregates those when it determines whether the filing requirement is triggered. A few situations where people get tripped up:
- Transferring intangible property like patents, trademarks, or goodwill triggers reporting even if no tangible assets move.
- If you contribute property to a foreign corporation and receive both stock and debt, you still file Form 926 for the stock portion.
- Transfers between related parties count. It doesn't matter if the foreign corporation is a subsidiary, sister company, or something you created yourself. The reporting obligation is the same.
How to Fill Out the Form
Start with Part I. You'll identify yourself as the transferor, list the foreign corporation's details, and describe the property transferred. Part II covers the valuation. This is where most mistakes happen. The instructions say you need to use the fair market value at the time of transfer. Fair market value isn't whatever you and the other party agreed to — it's what a willing buyer would pay a willing seller, neither under compulsion. Part III requires you to attach a statement describing the transfer in detail. This statement needs to include the nature of the property, the date of transfer, the value, and the identity of the foreign corporation. If you're transferring multiple types of assets, break them out individually. The IRS reviewer will check each line against what you reported on your main tax return. The attestation in Part IV is serious. You sign under penalties of perjury. I've seen people skip this part, assume it's a formality, and then get flagged months later for an incomplete filing. Don't skip it. Don't sign it unless you've actually reviewed everything on the form.
Get the Full Details
Common Pitfalls I've Seen Over the Years
The biggest issue is undervaluation of intangible property. People transfer a patent or customer list to a foreign entity and value it at zero or near-zero because there's no active market. The IRS does not accept that. You need a credible appraisal or at minimum a defensible valuation methodology. Snap decisions here lead to section 367 adjustments that can wipe out basis entirely. Another mistake is failing to aggregate related transfers. Say you set up a foreign holding company and transfer assets to it in three separate steps over six months. The IRS treats those as one transaction for Form 926 purposes. If you file three separate forms or none at all, you're exposed to accuracy-related penalties and potential fraud flags. Here's a specific scenario I dealt with last year. A client transferred equipment and associated intellectual property to a newly formed Cayman Islands corporation. They filed Form 926 with the equipment valued correctly but listed the IP as having no value since it was internally developed with no arm's-length sale history. The IRS issued a notice six months later demanding a revaluation. The workaround was to engage a third-party valuation firm to perform a discounted cash flow analysis on the IP. The resulting value was higher than our original estimate by about three hundred thousand dollars. Filing an amended Form 926 with the corrected valuation resolved the issue, but the delay cost us additional interest and ate two weeks of professional time. The lesson: value everything upfront. Don't leave gaps for the IRS to exploit.
Penalties for Not Filing
If you fail to file Form 926 when required, the penalty starts at ten percent of the gain that would have been recognized if the transfer had been treated as a taxable exchange. That's on top of whatever tax you owe on the gain itself. For transfers involving intangible property, the penalty floor is the entire fair market value of the property transferred, not just the gain. This means if you transferred a trademark worth two million dollars and forgot to file, your minimum penalty is two hundred thousand dollars even if you recorded zero gain on the transfer. There's also a separate penalty for failing to attach the required statement. It's smaller but cumulative. Multiple omissions stack quickly.
When Form 926 Doesn't Apply
The form doesn't cover every cross-border transfer. Contributing cash alone to a foreign corporation doesn't trigger Form 926. Transfers that qualify for a specific exception under section 367(b) may not require filing, though you still need to evaluate whether the exception actually applies to your situation. Certain reorganizations and liquidations have different reporting requirements on Forms 8621 or 5471 instead. If your transfer falls into one of those categories, Form 926 is the wrong instrument. Keep copies of everything. The valuation support, the completed form, the attached statement, proof of mailing or e-filing. The statute of limitations for Form 926 violations runs longer than a standard tax review. The IRS can go back further when a required disclosure is missing because the statute extends proportionally to the undisclosed amount. If you discover an error after filing, amend promptly. An unsolicited correction looks significantly better than a correction made after the IRS contacts you. There's no formal amendment process for Form 926 itself — you file a new form marked "Amended" and attach an explanation. It's not glamorous but it works in practice and demonstrates good faith, which matters when penalties are being assessed.