How to Actually Use a Divorce Asset Worksheet Without Messing It Up
Most people treat these forms like they're filling out a tax return. They aren't. They're building an inventory that will be contested, re-valued, and picked apart by two sets of people who want the same money. Getting the basics down right matters more than having a perfect-looking sheet.Free Printable Divorce Asset Worksheet
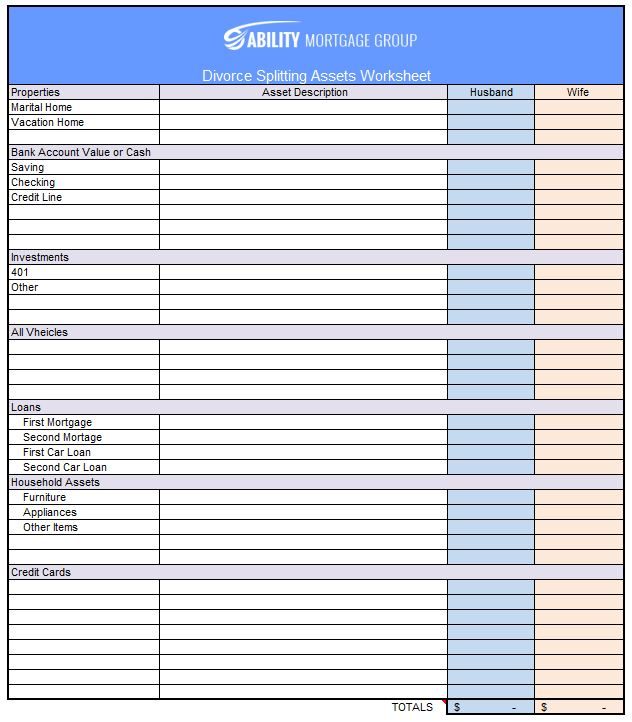
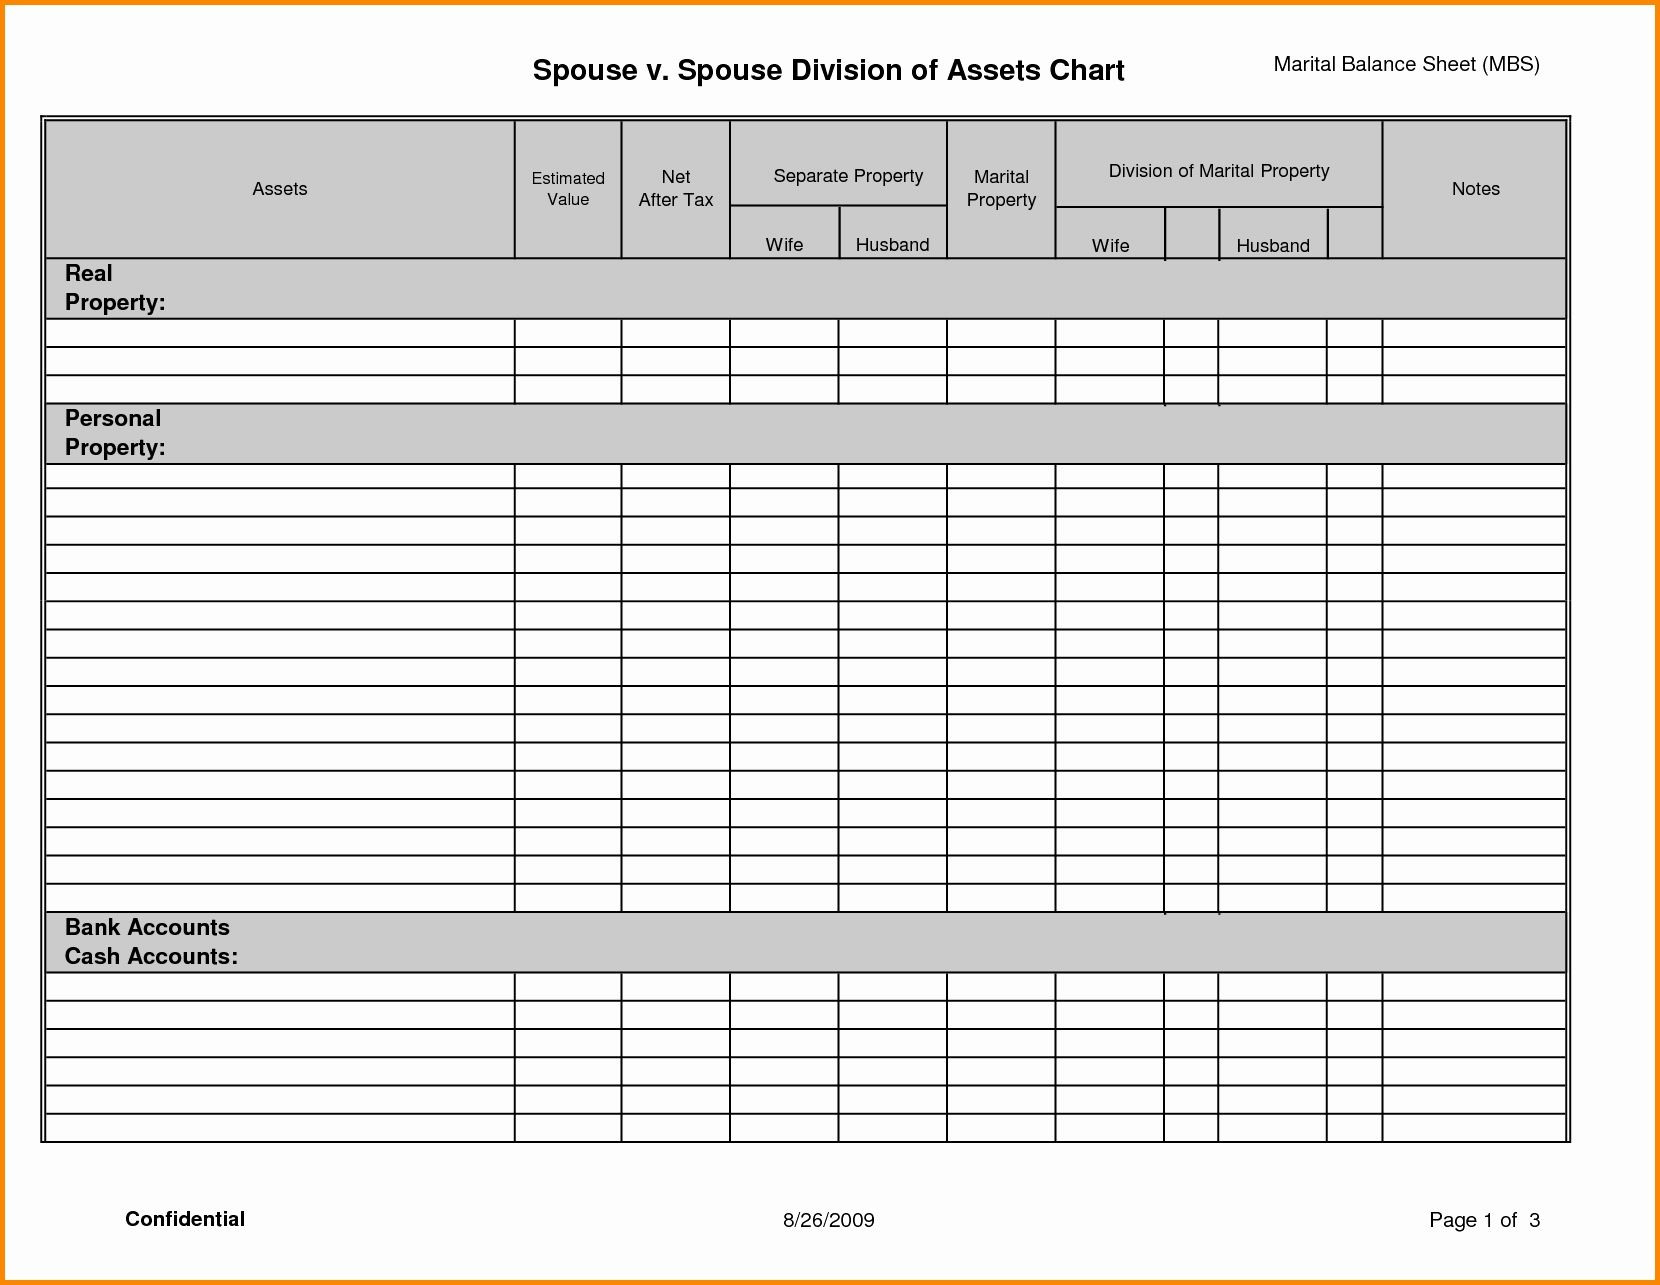
I've seen enough of these to know that the spreadsheet that looks cleanest is rarely the one that survives a negotiation. Here's what actually happens when you sit down to fill one out. Start with a blank document or a printed template and divide it into categories. You're not trying to be clever. You're trying to create a single source of truth that both sides can refer back to without arguing about who submitted the earlier version. Use headings for Real Estate, Retirement Accounts, Investment Accounts, Vehicles, Business Interests, Insurance Policies, Bank Accounts, Personal Property, and Debts/Liabilities. That's it. Don't nest sub-categories more than one level deep. Every extra tier is just friction later. For each asset, record four things: current fair market value, the account number or identifying information, whether it was acquired before or during the marriage, and how it's titled. The title field is where people get careless. A 401(k) in your name alone is still marital property in most states if contributions were made during the marriage. Listing it as "individual" without noting the marriage date creates a false distinction. Do the same for a car or a savings account. Put the acquisition date next to the title column. That pairing does more work than anything else on the sheet.
Here's the part nobody warns you about. Valuation dates matter more than value. Some jurisdictions use the date of filing, some use the date of separation, some let the court pick. If you value the house at $420,000 using a recent estimate but the relevant date is eighteen months ago, your entire asset pool is off by tens of thousands. Write down the valuation date next to every figure. Keep the source visible—a Zestimate, a recent appraisal, a brokerage statement. Don't round aggressively. Two thousand dollar differences look like rounding errors until someone adds them across fifteen line items. I ran into this once with a client who had a small consulting business she'd started three years into the marriage. The LLC was titled in her name, so the initial worksheet marked it as separate property. I almost missed it until the other side pulled her prior year tax returns, which showed business income flowing through her social security number and reported at home. The entity was hers, but the income was clearly commingled with joint accounts. We ended up tracing three years of deposits and withdrawals to determine the marital portion. That took a separate schedule attached to the main worksheet, not a column on the original form. If you have a business interest, add a second tab or a printed appendix showing the ownership percentage, acquisition date, and a brief trail of how marital funds interacted with it. Don't bury that detail in the main asset table. Debt is where worksheets get dishonest. Not intentionally, but people omit credit card balances or loans that appear on only one spouse's credit report. Both sides receive statements. Cross-check. Download a statement for every account you can find, even the ones the other person probably knows about. A $4,000 balance on a card you never saw until the final disclosure is worse than a missing asset. Assets can be negotiated. Hidden debt looks like bad faith.
When you list debts, include the creditor, the account number, the current balance, and the minimum monthly payment. The payment amount matters more than the balance in some negotiations because it shows cash flow impact after the split. A $15,000 car loan with a $400 monthly payment is a different problem than a $15,000 credit card balance with a $350 payment. Same debt, very different lifestyle consequences. Personal property is the hardest section to do honestly. People write "furniture" and put one number. That's not enough. List major items individually if they have significant value. Jewelry, artwork, collectibles, high-end electronics, fine dining sets. A wedding ring stays with the person who wears it in most places, but a inherited piece of jewelry might be separate. Note the source. Original purchase receipt helps. Receipt isn't mandatory, but without it the other side will assume the higher value. Retirement accounts need their own column for the spouse's name, plan type, current balance, and the last four digits of the account. QDRO-eligible accounts like 401(k)s and 403(b)s are divided differently than IRAs and Roth IRAs. Mark each row with a Q if it requires a qualified domestic relations order. That flag saves a conversation later when someone asks why the 401(k) wasn't split the same way as the savings account.
Get the Full Details
One thing most templates don't show you clearly: commingled assets. If you deposited an inheritance into a joint checking account and then used that money to pay down a mortgage on a house you owned before marriage, the asset is partly separate and partly marital. A simple worksheet row won't capture that. Add a note field. Three words won't solve it, but "partial commingling, inheritance origin" gives you a starting point for the actual math. Don't try to calculate the split on the worksheet. Just mark it and move on. You'll need a separate calculation or professional help for that anyway. If you want to print this, a single sheet won't work. Expect three to six pages depending on your situation. Use landscape orientation. Set column widths so the description column is at least two inches wide. Anything narrower and you'll be wrapping text and making it hard to read later. Save a PDF copy immediately after filling it out, then save another copy whenever you update it. Version control matters when you're sending revised sheets back and forth. There are downsides to relying on a printable worksheet. They don't link to your bank accounts, so every number is manual entry. Manual entry creates errors. You will transpose a digit at least once. Check every number twice. They also don't flag duplicate accounts automatically, so if you list a savings account in one section and again in another, nobody notices until the other side points it out. Print two copies. Cross-reference each row between them before submitting anything.
If you have complex assets—stock options, deferred compensation, intellectual property, international accounts—a worksheet is a starting point, not the solution. In those cases, spend the money on a forensic accountant or a divorce professional who knows how to trace assets. A free printable form won't save you from a misvalued option pool, and the cost of fixing that mistake later is always higher than the cost of getting it right the first time. For most people with a house, two cars, a couple of retirement accounts, and standard bank accounts, a well-filled worksheet cuts the disclosure phase from several days of scrambling down to a few hours. Fill it out in one sitting, sleep on it, then go back and verify every line against actual statements. That second pass is where the real work happens. The numbers don't lie, but the first version you write almost always contains optimism.
Party Name: _______________________
Valuation Date: ___________________
REAL ESTATE
Property Address | Current Value | Mortgage Balance | Title Status | Acquired (Date) | Notes
_________________________________________________________
_________________________________________________________
RETIREMENT ACCOUNTS
Account Holder | Plan Type | Balance | Last 4 Digits | QDRO Eligible? (Y/N) | Acquired (Date)
_________________________________________________________
_________________________________________________________
INVESTMENT ACCOUNTS
Account Holder | Institution | Balance | Last 4 Digits | Acquired (Date)
_________________________________________________________
_________________________________________________________
VEHICLES
Make/Model/Year | VIN (last 4) | Title Status | Purchase Price | Current Value
_________________________________________________________
_________________________________________________________
BUSINESS INTERESTS
Entity Name | Ownership % | Acquisition Date | Marital/Separate Note
_________________________________________________________
BANK ACCOUNTS
Account Holder | Institution | Balance | Last 4 Digits | Acquired (Date)
_________________________________________________________
_________________________________________________________
INSURANCE POLICIES
Policy Type | Insured | Cash Value | Beneficiary
_________________________________________________________
PERSONAL PROPERTY
Item Description | Estimated Value | Acquired (Date) | Source (Purchase/Gift/Inheritance)
_________________________________________________________
_________________________________________________________
DEBTS / LIABILITIES
Creditor | Account (last 4) | Current Balance | Monthly Payment | Joint/Individual
_________________________________________________________
_________________________________________________________
SIGNATURE: ________________________ Date: ____________