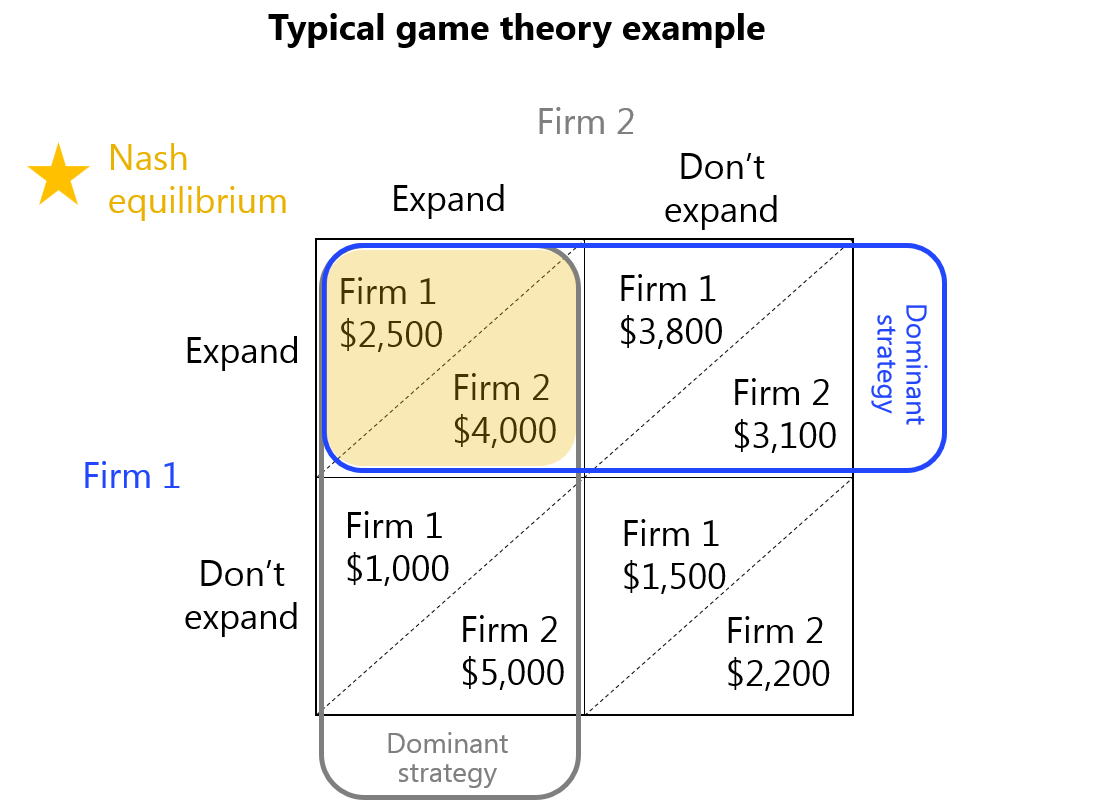
Understanding how firms actually use game theory
Game theory isn't just academic math for economists. Companies use it constantly, often without realizing they're doing it. When a pricing team debates whether to match a competitor's price cut or hold steady, they're running a prisoner's dilemma in their heads. When two suppliers negotiate a long-term contract while knowing both could walk away, that's a repeated game with incomplete information. The models are frameworks for thinking about strategic interdependence. I've spent years watching this play out across supply chain negotiations, competitive pricing strategy, and product launches. The theory works beautifully on paper and falls apart spectacularly when humans get involved. Let me walk you through what actually happens, some real examples, and the things people usually miss until it bites them.
Game Theory In Business Examples
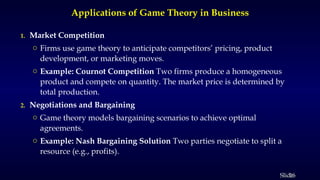
One of the most cited examples in business is the prisoner's dilemma as it applies to price competition. Think about the airline industry. Every time Delta considers lowering fares on a route, United has to decide whether to match or ignore the cut. If both keep prices high, they both make good margins. If one drops and the other doesn't, the discounter steals traffic while the matcher bleeds revenue. If both drop, they're in a race to the bottom. That's the textbook structure, and it describes exactly what happened on multiple domestic routes during the 2010s when Southwest pushed low fares into major markets. Another common example involves market entry deterrence. A dominant firm might structure its capacity or pricing so that a potential entrant calculates the expected payoff of entering as negative. Coca-Cola and Pepsi have used this implicitly for decades by maintaining massive distribution networks that make it nearly impossible for a new beverage company to get shelf space. The incumbent isn't necessarily acting maliciously, but the game-theoretic outcome is the same: the threat of a costly price war or capacity expansion keeps challengers out. Bertrand competition models explain something that sounds counterintuitive at first. When firms compete on price with homogeneous products, the Nash equilibrium drives prices down to marginal cost even with only two players. This is why retail sectors with very similar offerings tend to have razor-thin margins. The moment you differentiate your product slightly, the entire game changes because you're no longer playing Bertrand but moving toward a differentiated duopoly model.
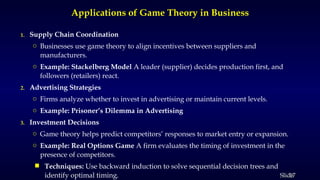
Here's a specific case I ran into that nobody in any textbook prepared me for. A client was negotiating a supply agreement with a component manufacturer who was also supplying their direct competitor. The game-theoretic model suggested that if we agreed to exclusive volume commitments, the supplier would prioritize us. But the reality was messier. The supplier had already invested heavily in tooling for our competitor's specs. The commitment we were offering didn't offset their sunk costs, so the theoretical leverage we thought we had evaporated immediately. What actually worked was structuring the deal with a volume floor combined with co-development of a new component variant that would be harder for the competitor to source elsewhere. That shifted the payoff matrix entirely. It took about three weeks to model the revised scenarios and another two to get internal approval for the higher upfront investment. The key insight most people miss is that repeated games change everything. A one-shot prisoner's dilemma predicts mutual defection. But in business, you're usually playing the same game repeatedly against the same players. That introduces the possibility of trigger strategies and reputation effects. Companies that understand this will sometimes absorb short-term losses to establish a cooperative equilibrium. You see this in B2B industries where vendors deliberately underprice a first contract to lock in a long-term relationship, knowing the repeated interaction makes cooperation more valuable than a single round of betrayal. Another counter-intuitive point is about signals and credibility. In business, cheap talk is everywhere. A CEO announcing that a price increase is coming is sending a signal, but unless there's cost structure behind it, rational competitors will ignore it. I've seen entire strategy sessions wasted because a company treated an ambiguous statement from a competitor's earnings call as a binding commitment. It wasn't. The only signals that move the game are those that carry real cost to the sender. If a firm shuts down a production line or commits to a multi-year contract, that's expensive. That's credible. Pricing slogans are not.
Get the Full Details

The Nash equilibrium concept is foundational but limited. It assumes all players are rational and have common knowledge of the payoff structure. In practice, companies rarely know their competitor's true costs or strategic priorities. Bayesian games account for this by introducing types and beliefs, but most business teams don't model uncertainty properly. They pick one scenario and optimize for it. A more robust approach maps probability distributions over competitor responses rather than assuming a single predicted move. This usually adds about a day or two of analysis but significantly improves decision quality because it forces you to confront worst-case outcomes you'd otherwise ignore. There are real limitations to relying on game theory in business settings. The models require assumptions that rarely hold in complex markets. They assume rational actors, which is obviously flawed when executives make emotional decisions or when board pressure forces suboptimal plays. They also struggle with more than two or three players, where the solution space becomes computationally intractable without heavy simplification. In highly dynamic markets where preferences shift rapidly, game-theoretic predictions become stale quickly because the payoff matrix itself is changing faster than you can model it. When game theory breaks down completely, you're usually looking at situations with extreme information asymmetry, rapidly evolving technology disrupting existing payoffs, or markets with so many small players that coordination becomes impossible. In those cases, optionality and scenario planning beat equilibrium analysis every time. A firm might map out several plausible futures and build flexibility into its strategy rather than trying to predict the single best response to a competitor's move. This is essentially real options thinking applied to competitive strategy.
The practical takeaway is straightforward but not simple. Start by identifying the strategic interaction clearly. Who are the players, what are their possible moves, and what do they value? Then map the payoff structure as honestly as you can, including what you don't know. Run through one-shot and repeated game logic. Test whether any equilibrium is stable or whether the dynamics push toward continuous adjustment. And always ask what would make a signal credible versus empty. That last part alone will save you from more bad decisions than any sophisticated model ever will.