Getting GASB Standards Implemented Without Losing Your Mind
GASB 68 and 75 changed how public pension and OPEB plans get reported. Most governments understood the new requirements eventually, but the implementation phase was messy. The GASB Comprehensive Implementation Guide is supposed to help, but it's 300+ pages of dense reference material that doesn't always tell you exactly what to do in practice. Here's what actually works when you're trying to get your financial statements compliant. The guide itself is published by the Government Finance Officers Association and the GASB jointly. You can find it on the GASB website or through GFOA's publication catalog. The current edition covers the major standards through GASB 99. It's organized by standard rather than by process, which means you'll spend more time hunting for answers than you'd like. What the guide does well: it gives you specific journal entry examples for the most common scenarios. The OPEB section has templates that are close to usable if you adjust them for your plan details. The pension section walks through the actuarial Present Value of Projected Benefits calculation methodology they expect to see. That part alone is worth the effort of reading through it carefully.
Where it falls short: the guide assumes your actuary is working within certain parameters that may not match your situation. I ran into this with a mid-sized municipality that used a custom entry age normal cost method. The guide's example calculations didn't apply. What I ended up doing was extracting the relevant paragraphs from the guide and cross-referencing them directly with the underlying GASB 68 text. The actual standard language is clearer about what flexibility exists than the implementation guide lets on. You have to know where to look, though.
The Real Implementation Sequence
Most people start wrong. They begin with the financial statement format and work backward. That creates problems because the note disclosures depend on numbers that come from actuarial valuations, and those valuations depend on decisions made early in the process. Start with the valuation inputs instead. First, confirm your discount rate methodology. This is where most errors show up. For high-quality fixed-income municipal bonds, the guide recommends using the S&P Municipal Bond 20 Year High Grade Index yield curve. The nuance nobody warns you about is that the yield curve points shift quarterly, and your measurement date determines which points matter. I've seen firms use the wrong month's curve and miss the discount rate by 15 basis points. That sounds small until you're looking at a $2 billion liability. Second, establish your actuarial assumptions and get them approved. The guide expects documentation of the board or authority that approved each assumption. If you're a smaller government without a formal benefit committee, the governing body minutes usually suffice. Make sure they're explicit about each assumption being adopted, not just referenced. Auditors will ask for the specific language.
Get the Full Details
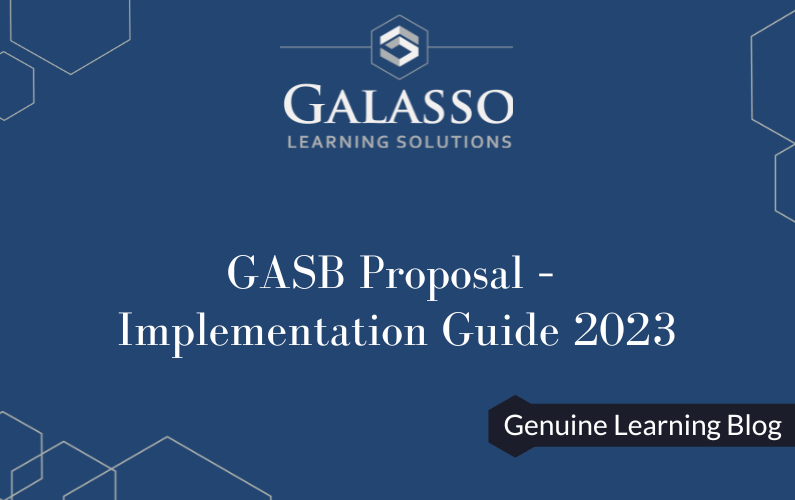
Third, run the valuation. Your actuary should produce a report that maps directly to the GASB Schedule E requirements. Don't accept a generic actuarial report and try to extract GASB numbers from it. That approach works sometimes and fails spectacularly other times. Specify upfront that the report needs to be structured for GASB 68 or 75 reporting.
Common Mistakes That Waste Time
The subscription cost calculation trips up a lot of people. GASB 71 requires you to recognize the employer share of the pension cost attributable to earlier periods when a new plan takes over. The guide covers this, but the practical application depends on whether your plan has a transition amount built in. If it does, you might not need to do a full GASB 71 calculation. Check first before spending hours on it. Another issue is the fiduciary net position presentation. The guide shows one format, but multiple pension plans with different measurement dates create complications. If your plans don't all use June 30 as their measurement date, you need to present them separately even if they're under the same employer. The guide mentions this briefly near the end. It deserves more attention. Statutory requirements interaction is another minefield. Some states have their own reporting rules that overlap with GASB standards. The guide doesn't address state-specific conflicts. If you're in a state like Texas or Colorado with additional requirements, you'll need to reconcile both sets yourself. Start this process early because it usually uncovers timing differences that affect your submission schedule.
What to Do When the Guide Doesn't Help
Sometimes the guidance simply doesn't cover your situation. I worked with a water district that had a hybrid defined benefit and cash balance plan. The guide treats them as separate entities with no section addressing the combination. What I ended up doing was treating each component independently and then reconciling the totals against the district's accounting system. It took three extra days but produced clean statements that auditors accepted without questions. When you hit these gaps, go to the primary source. The GASB Concepts Statements and the original standard documents are often more helpful than any implementation guide. The conceptual framework explains why the requirements exist, which makes it easier to figure out how they apply to edge cases. It's slower reading but saves time in the long run. The guide remains a useful reference tool if you know how to use it. Start with your specific requirements, work through the valuation process in the correct order, and don't treat the examples as universal templates. The actual implementation takes judgment, not just compliance checklisting.