What Actually Matters When Studying for General Lines P&C
Most people blow through study materials without understanding how the exam is structured, then wonder why they miss questions they thought they knew. The General Lines Property And Casualty Study Guide you end up using matters less than how you approach it. I have sat through enough of these licensing exams to recognize the patterns. Let me explain what is actually worth your time. The general lines P&C exam varies slightly by state, but most follow a similar pattern: roughly 100 to 150 multiple choice questions, divided into property coverage, casualty liability, and policy forms. You typically have two hours. Passing scores range from 60 to 70 percent depending on the state. This means you can get roughly 30 to 45 questions wrong and still pass. That sounds generous until you realize how many questions contain two answers that look correct on first read. The trick is that the exam tests application, not just memory. A question will describe a specific scenario — a homeowner's policy with a $500 deductible, a garage liability claim, a commercial auto exclusion — and ask what happens next. You need to know the policy language well enough to spot the trap.
How to Actually Use a Study Guide
Grab a General Lines Property And Casualty Study Guide, but do not read it cover to cover like a novel. That is the fastest way to forget everything by chapter three. Instead, use it as a reference while you take practice exams. When you miss a question, go back to the relevant section and read it actively. This takes longer on day one but dramatically reduces total study time over the next two weeks. I learned this the hard way back in 2014 when I was trying to add the commercial lines endorsement to my license. I had memorized the personal auto policy definitions cold but completely fell apart on commercial inland marine coverage. The textbook was organized by line of business, so I had been reading sequentially. Once I switched to practice test first, gap identification second, I cut my remaining study time from about six weeks down to ten days.
Property Coverage Is Where People Stall
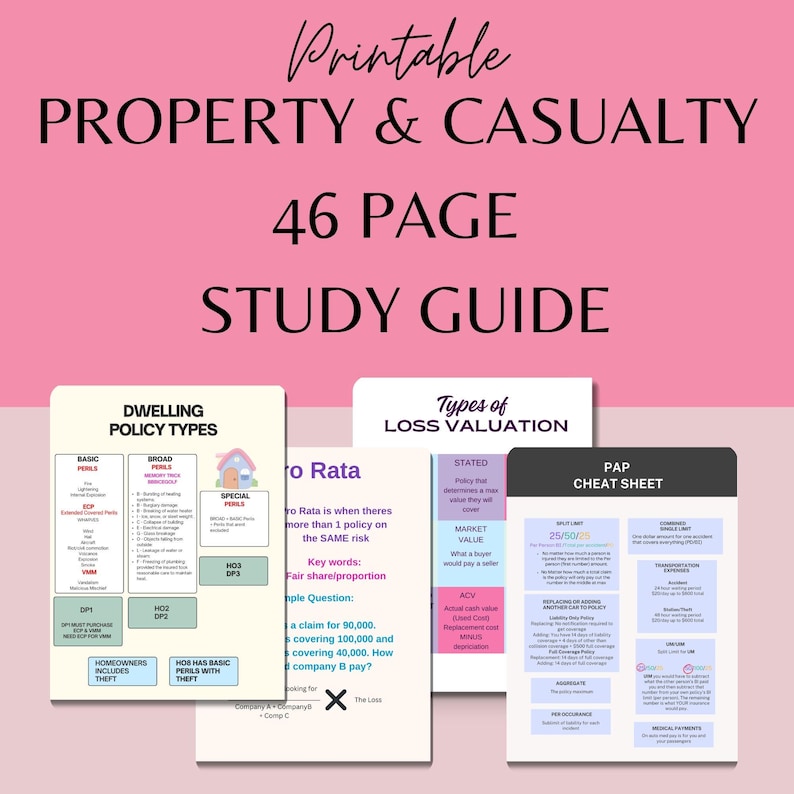
Property questions make up a significant portion of the exam, and this is where most candidates lose points. Specifically, the HO series policies and the differences between HO-3, HO-5, and HO-8. Most study guides list these in a table, which looks clean but does not prepare you for how the exam actually asks about them. Here is a detail that rarely gets emphasized: the named perils vs open perils distinction applies differently depending on the dwelling coverage versus personal property coverage within the same policy. An HO-3 policy provides open perils on the dwelling but named perils on the contents. An HO-5 does open perils on both. Questions will describe a loss and expect you to know which part of the policy applies and whether it is named or open. If you only memorize the broad categories without understanding the split structure, you will pick the wrong answer consistently on this section.
Get the Full Details

Common Pitfalls That Cost People the Exam
The first pitfall is confusing sublimits with overall limits. A policy might have a $100,000 coverage limit for personal property but only $1,500 for jewelry. The exam will give you a claim amount that falls within the overall limit but exceeds the sublimit, then ask how much the insurer pays. The answer is always the sublimit, not the overall limit. I have seen people second guess themselves on this exact question repeatedly because the wording is deliberately designed to make you think about the broader limit first. The second pitfall involves the duties after loss section. Every property policy includes a list of obligations the insured must fulfill after a loss occurs. The exam loves to ask what happens if the insured fails to cooperate. The correct answer is usually that the insurer may deny the claim entirely, but some questions frame it as a partial denial or a reduction in payment. Read the specific wording of each answer choice carefully. "May deny" and "Will deny" are not the same thing on this exam, and the test makers know that.
What No Study Guide Tells You Clearly
The CGL form and its amendments come up more than people expect. Specifically, the completed operations hazard and the contractual liability exclusion. These are easy to skim past because the language sounds dry, but they show up in scenarios involving contractors and subcontractors. If you are studying for a state exam that includes commercial lines, spend real time here. The contractual liability exclusion removes coverage for liability assumed under a contract unless that liability would exist anyway in the absence of the contract. That double negative trips people up. Write it out in plain English until it sticks: the policy only covers what you are legally responsible for regardless of any contract you signed. Another thing that catches people off guard is the difference between occurrence and claims-made triggers in professional liability and general liability. An occurrence policy covers claims based on when the incident happened. A claims-made policy covers claims based on when the claim was reported. Mixing these two up on the exam is an automatic wrong answer every time. Make sure you can identify which form is being referenced within the first sentence of a question.
Limitations of Study Guides
A study guide will not replace practice exams. No amount of reading alone will prepare you for the way questions are worded. The gap between knowing the material and recognizing what the exam is asking is real, and it only closes through repeated testing. Use the guide to fill gaps, not as your primary study method. Additionally, study guides become outdated quickly on state-specific endorsements. If your state has adopted a particular amendment to the standard ISO forms, your guide might still reference the original language. Check your state insurance department website for any recent rule changes before you schedule your exam date. I lost a week of study time once because my guide had a footnote about a homeowners endorsement that the state had replaced months earlier.
Where to Find Current Materials
The General Lines Property And Casualty Study Guide you should use is one that references the current year's ISO forms and matches your state's specific exam outline. Most pre-licensing courses provide one, and state insurance department websites publish the official content outline. Cross reference both. If a study guide contradicts what is on the state outline, the state outline wins every time. Practice exams from at least two different providers will also reveal where your weak areas are before test day. One provider will skew harder on property, another on casualty. Taking both gives you a more complete picture of your readiness than any single resource can. Time your practice sessions. Two hours is the actual exam length, and sitting through a full timed practice test reveals how much mental fatigue affects your accuracy in the final third of questions. Most people get careless on questions 120 through 150 because their focus drops. Building that stamina matters more than finishing one more chapter of the textbook.