Why Your Particular Solution Is Always Missing That Constant
I spent three semesters teaching differential equations before I realized most students never actually grasp what the general solution represents. They memorize the steps—separate variables, integrate both sides, add C—and move on. The C disappears in boundary value problems anyway, so they assume it is just a formality. It is not. That constant is the entire point. Here is what happens when you actually need the general solution in practice. You are working on a heat transfer problem for a pipe system, and the differential equation models temperature distribution along the length of the pipe. You solve it, get your particular solution with specific numbers plugged in, and hand it to the engineer. They come back two days later saying the model does not match field measurements. Turns out you solved for one set of boundary conditions when the system was operating at design temperature, but the actual conditions during testing were completely different. If you had kept the general solution with that arbitrary constant, you could have adjusted it to fit the new conditions without redoing the entire derivation. I learned that lesson the hard way.
What The General Solution Of A Differential Equation Actually Means
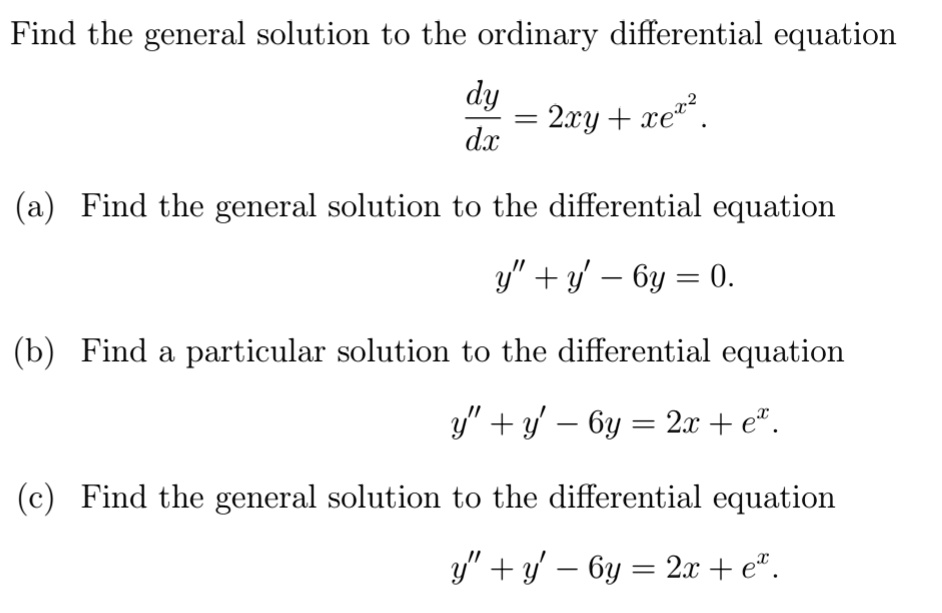
A differential equation relates a function to its derivatives. When you solve it, you are looking for the original function. The general solution is the family of all possible functions that satisfy that relationship, expressed with one or more arbitrary constants equal to the order of the equation. A first order equation gets one constant. Second order gets two. This is not a suggestion. It is a theorem, and it matters because missing constants are the single most common source of error in applied work. Consider y prime equals 2x. The immediate answer is y equals x squared plus C. Anyone who stops at y equals x squared has only found one member of the solution family, not the general solution. The particular solution comes later, when you apply initial or boundary conditions. The general solution exists before those conditions are imposed, and it carries information that particular solutions discard. Here is a case that trips people up regularly. Separable equations. dy by dx equals x times y. You divide both sides by y, multiply by dx, integrate, and get ln of absolute value of y equals x squared over 2 plus C. Then you exponentiate and write y equals e to the x squared over 2 plus C. A lot of students leave it there, but that is technically wrong. The correct form is y equals Ae to the x squared over 2, where A is an arbitrary nonzero constant. You also have to check whether y equals 0 is a solution, which it is. That equilibrium solution disappears if you divide by y without considering the case where y equals zero first. I catch this mistake in every class, and it is the same mistake engineers make when they skip the equilibrium analysis in modeling work.
The Standard Methods And Where They Break Down
First order linear equations follow the integrating factor method. You rewrite the equation in standard form, compute e to the integral of p of x dx, multiply through, and integrate. It works every time the integrating factor exists, which is almost always for continuous coefficients. The catch is that the method produces the general solution only when you carry the constant through every step. People often multiply by the integrating factor, recognize the left side as a derivative, integrate, and then forget to add the constant on the right side before solving for y. That produces a particular solution disguised as a general one. Exact equations are another story. The condition M dx plus N dy equals zero is exact when partial M over partial y equals partial N over partial x. When this holds, you find a potential function f such that partial f over partial x equals M and partial f over partial y equals N. The general solution is f of x comma y equals C. The practical problem here is that many equations encountered in real work are not exact. You have to find an integrating factor, which may depend on x alone, y alone, or some combination. Sometimes the integrating factor exists but cannot be expressed in closed form. In those cases, the general solution is implicit and numerical methods become necessary. I worked on a fluid dynamics problem a few years back where the governing equation reduced to a second order nonlinear ODE. The exact integrating factor depended on a function that could not be evaluated analytically. I ended up using a power series expansion around the operating point to construct an approximate general solution, then validated it against experimental data. The approximate solution worked within five percent for the range of interest, but outside that range it diverged quickly. This is the reality of general solutions in applied work: exact forms are rare, approximations are necessary, and you always need to know the domain of validity.
Get the Full Details

Higher Order Equations And The Characteristic Polynomial
Constant coefficient linear equations reduce to algebra through the characteristic polynomial. y double prime plus three y prime plus two y equals zero becomes r squared plus three r plus two equals zero, which factors to r equals negative one and r equals negative two. The general solution is y equals C one e to the negative x plus C two e to the negative 2x. Straightforward when the roots are real and distinct. Complicated when they are not. Repeated roots introduce a factor of x. If r equals negative one with multiplicity two, the general solution is y equals C one e to the negative x plus C two x e to the negative x. Students often miss the x factor on the second term because it does not appear in the simple case. Complex roots produce oscillatory solutions. If r equals alpha plus beta i, the general solution involves e to the alpha x times cosine of beta x and sine of beta x. The arbitrary constants still appear, but now they multiply trigonometric functions instead of exponentials. The method fails when coefficients are not constant. Variable coefficient equations like Bessel equations or Legendre equations do not yield to characteristic polynomials. You need series solutions or special functions, and the general solution is expressed in terms of those functions with arbitrary constants attached. Bessel functions of the first kind and second kind are the standard basis for cylindrical problems. The general solution to Bessel equation of order n is y equals C one J sub n of x plus C two Y sub n of x. You cannot simplify this further with elementary functions, and any software that claims to give a closed form in terms of polynomials or exponentials is lying to you.
Reduction Of Order And Known Solutions
When you already know one solution to a homogeneous linear equation, you can find the general solution by reduction of order. Suppose y sub one is a known solution to y double prime plus p of x y prime plus q of x y equals zero. You substitute y equals v times y sub one and derive a first order equation in v prime. This reduces the problem but does not eliminate it. The resulting equation is still a differential equation, just of lower order. For second order equations, you get all the way down to an algebraic integration, which gives the second independent solution and completes the general solution. Undetermined coefficients work for constant coefficient equations with specific forcing functions. If the right side is a polynomial, exponential, sine, cosine, or a combination, you guess a form with unknown coefficients and solve for them. The guessed form contains no arbitrary constants, so the arbitrary constants come entirely from the complementary solution. This means the general solution is always the sum of the complementary solution plus a particular solution. The complementary part carries the constants, and the particular part is fixed by the forcing function. I have seen engineers use undetermined coefficients incorrectly on equations with variable coefficients. The method only applies to constant coefficients. When coefficients vary, you need variation of parameters, which is more general but also more tedious. Variation of parameters constructs a particular solution using the Wronskian of the complementary solutions. It always works in principle, but the integrals involved are not always computable in closed form. When they are not, you are back to numerical integration.
When The General Solution Cannot Be Written Explicitly
Sometimes the general solution exists only implicitly. Consider y prime equals e to the negative y squared. The integral on the right side has no elementary antiderivative. The general solution is expressed as an integral involving the error function, or left as an unevaluated integral. This is not a failure of the method. It is a limitation of elementary functions. The solution is still well defined, it just cannot be written using the functions you learned in calculus. I encountered this type of situation when modeling a chemical reactor where the reaction rate depended exponentially on concentration in a way that produced a nonintegrable expression. The general solution could only be represented numerically. I used a Runge-Kutta method to generate solution curves for different initial conditions, which effectively gave me the solution family that the general solution describes analytically. The numerical approach is less elegant but more practical when closed forms are unavailable. The same issue arises with autonomous equations where the separation of variables leads to an integral that cannot be evaluated. You can still analyze the phase line, identify equilibrium points, and determine stability without writing the general solution explicitly. This qualitative analysis is often more useful than an explicit formula, especially for nonlinear systems where small changes in parameters can produce entirely different solution behaviors.

Common Pitfalls That Waste Time
The first pitfall is dropping the arbitrary constant during integration. Every indefinite integral introduces a constant, and losing one of them changes the solution set. I grade papers where students integrate and forget the constant, then apply initial conditions to a solution that is missing half its degrees of freedom. The result is mathematically wrong even if the arithmetic is correct. The second pitfall is treating the constant as a specific number before applying conditions. The constant is arbitrary until boundary or initial data specify it. Writing C equals five before you have any reason to do so is a logical error. It limits the solution prematurely and can cause you to miss valid solutions that satisfy the differential equation but not your prematurely fixed constant. The third pitfall is assuming that the general solution covers all possible solutions. Singular solutions exist for some nonlinear equations. The Clairaut equation is the standard example. Its general solution is a family of straight lines, but there is also an envelope solution that is not part of that family. The envelope satisfies the differential equation but cannot be obtained by choosing any value of the arbitrary constant. I found this relevant when analyzing a control system where the envelope solution corresponded to a stable operating point that the general family of solutions did not reveal.
A fourth pitfall is confusing the domain of the general solution with the domain of a particular solution. The general solution may be defined on an interval that is smaller than the interval where the differential equation is well defined. This happens with equations that have singular points. The solution exists, but only on a restricted domain, and the arbitrary constants do not extend that domain. You need to check the existence and uniqueness theorem conditions separately.
Verification Is Not Optional
Every general solution should be verified by substitution back into the original equation. This catches errors in sign, missing factors, and incorrect constants. I spent two hours once chasing a bug in a simulation that turned out to be a sign error in the general solution of a damping equation. The simulation produced physically impossible results because the exponential decay term had the wrong sign. Verification would have caught it in seconds. Software tools like Mathematica, Maple, and SymPy can compute general solutions, but they do not always handle edge cases correctly. Singular solutions, domain restrictions, and branch cuts in complex logarithms are frequently mishandled. I trust these tools for verification and exploration, but I always check the output against manual calculations, especially for the constants and domain issues. A general solution from software without verification is a gamble, and the consequences of a wrong gamble in engineering work are not theoretical. The general solution is not an academic exercise. It is the complete description of all behaviors permitted by a differential equation, and missing any part of it means you are working with an incomplete model. Whether you are solving textbook problems or building systems that control real infrastructure, that distinction matters. The constant is not decoration. It is the difference between knowing one solution and knowing all of them.