How HELOC Amortization Actually Works
Most people think a Home Equity Line of Credit payment stays the same month after month. It does not. The structure changes depending on which phase you are in, and if you do not understand that difference, your monthly budget will be off by a significant amount. A HELOC has two distinct periods. The draw period lasts anywhere from five to ten years, during which you can withdraw money as needed. During this time, your minimum payment is usually calculated on just the outstanding balance at an interest-only basis. Then comes the repayment period, which can stretch another ten to twenty years. At that point, the lender restructures your payment so it includes both principal and interest, and the amount jumps noticeably because you are now paying down the balance while still accruing interest.
Using a Heloc Amortization Calculator Correctly
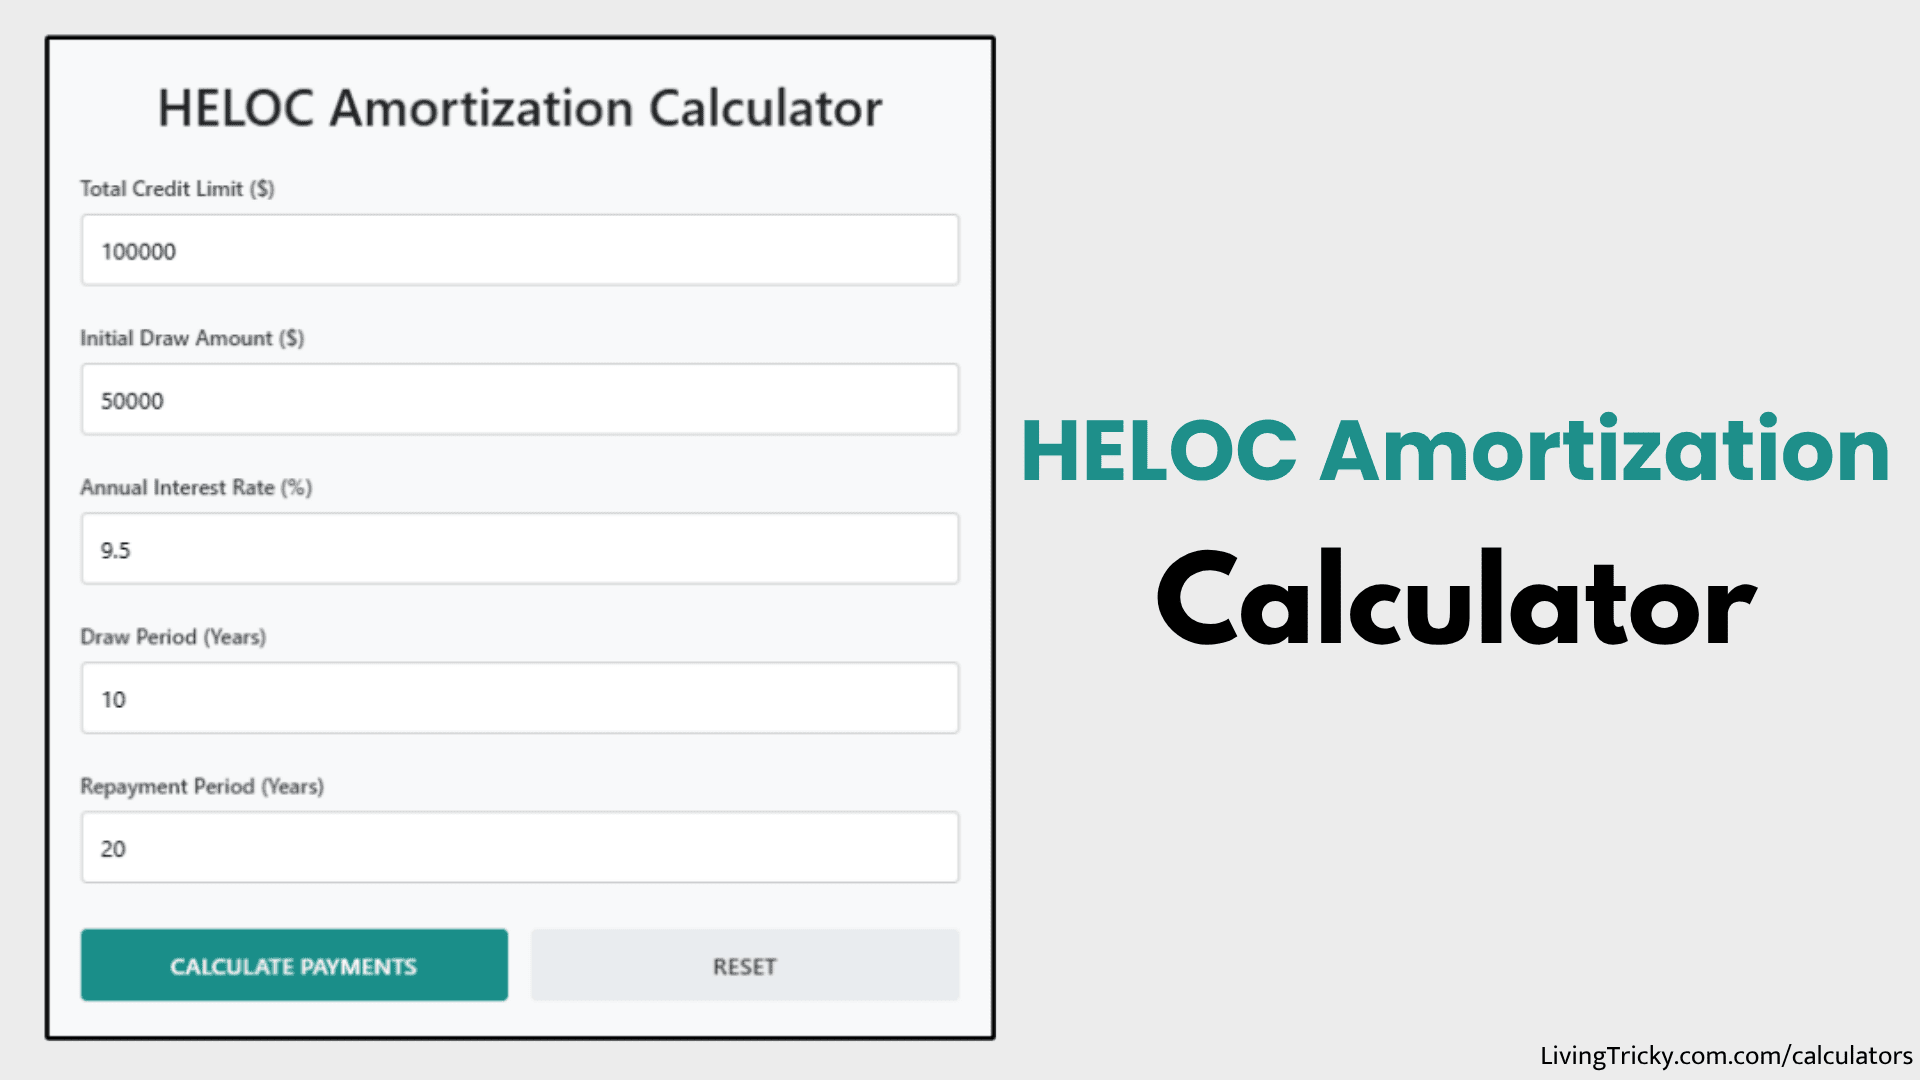
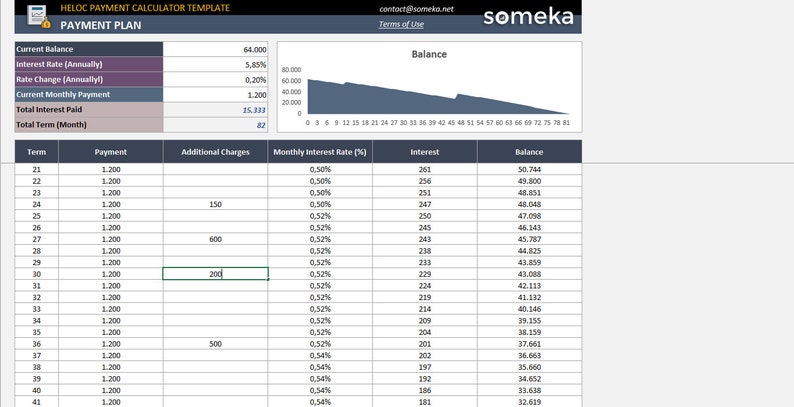
This is where most people make errors, and I have seen it repeatedly. A Heloc Amortization Calculator takes your credit limit, draw amount, interest rate, and term to project what your payments will look like across both phases. The important detail that most free online versions skip is that the interest-only period often does not reduce your balance at all. If you borrow $50,000 and only make interest payments for eight years, you still owe the full $50,000 when the repayment period begins. That means your actual monthly payment during repayment could be double or triple what you were paying during the draw period. The input fields you need to focus on are the draw amount, not the credit limit. The credit limit tells you how much you can access, but the draw amount is what actually generates your payment obligation. Put in the wrong number and your entire amortization schedule is meaningless. Another thing to verify is whether the calculator uses a 360-day or 365-day year for interest computation. Most lenders use 360, but not all free calculators default to that, and the difference can add up over a long repayment period. I ran into a specific problem last year when a client asked me to review their HELOC schedule. The calculator they had been using assumed equal monthly compounding, but their lender was applying interest daily based on a balance that fluctuated every time they made a withdrawal or payment. The projected amortization looked clean on paper, but their actual payments were consistently $40 to $60 higher each month than what the schedule showed. I switched to building a spreadsheet that calculated daily interest on the actual outstanding balance and adjusted for irregular payments, which brought the projection within $8 of the lender's actual statement. It took about forty-five minutes to set up, and it saved them from budgeting incorrectly for the next six years.
When you enter your data, pay close attention to how the calculator handles the transition between the draw and repayment periods. Some tools show a smooth curve, but the real jump in payment happens on the exact date the lender shifts your loan into amortization mode. If your repayment period is set for twenty years starting after a ten-year draw period, the calculator should reflect that the first twenty-four months of repayment still carry a high balance with relatively small principal reduction. Only in the later years does the principal pay down faster as the compounding effect kicks in. There are also situations where a Heloc Amortization Calculator simply will not give you an accurate picture. If your rate is variable and your lender uses a margin plus a benchmark index, the projected payments become speculative after the first year. A calculator can show you what happens at the current rate, but if rates move by half a point or more, your actual numbers will drift. Some lenders also charge annual maintenance fees or transaction fees on withdrawals that these tools do not factor into the amortization schedule. Those fees do not change your payment amount directly, but they increase the total cost of borrowing in ways that standard calculators ignore. The most useful application of this tool is not for day-to-day budgeting but for scenario planning. Run the numbers at three different interest rates — your current rate, plus two hundred basis points above and below — and look at how dramatically the repayment phase payment shifts. This helps you understand your maximum exposure before you commit to drawing a large balance. I usually run the worst-case scenario at the highest rate first because that number determines whether you can actually afford the loan if rates move against you.
Get the Full Details
If your HELOC has a reset clause that changes the repayment term depending on when you started drawing, check your promissory note for the exact language rather than relying on any calculator. These terms vary between lenders and can shorten or extend your repayment window in ways that standard amortization formulas do not account for. One lender I worked with had a clause that truncated the repayment period to fifteen years instead of the standard twenty if the borrower drew more than seventy percent of the available line, which dramatically increased the monthly payment compared to what a basic calculator would show. The bottom line is that these calculators are directionally useful but not precise enough for financial decisions on their own. They give you a framework, not a forecast. If you need accuracy, build or commission a schedule that reflects your actual lender's terms, compounding method, and fee structure. The time investment is worth it because getting the payment wrong during the repayment phase can cause a cash flow problem that is expensive to fix.