What the HELOC Equity Calculator Actually Does
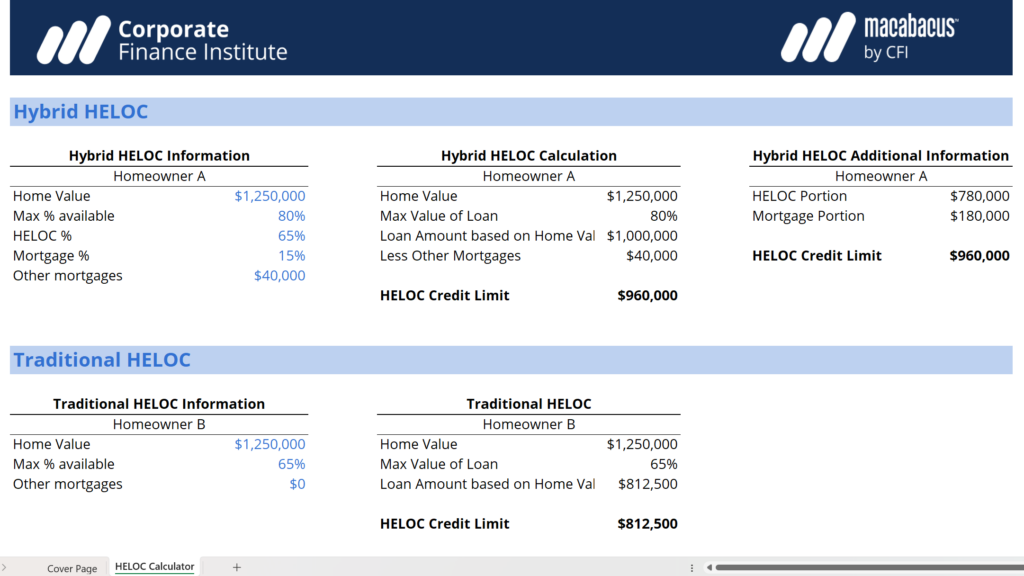
A HELOC equity calculator takes your home's current market value, subtracts your remaining mortgage balance, and shows you how much equity is available as a line of credit. Most banks let you borrow up to 80-85% of your home's value minus what you owe. The math itself is trivial. The part nobody warns you about is that the calculator output rarely matches what you'll actually get approved for. Here's the basic formula that every online tool uses: Available Credit = (Home Value × LTV Limit) Current Mortgage Balance Any Existing HELOC Balance
Where LTV limit is typically 80% or 85% depending on the lender. If your home is worth $400,000 and you owe $250,000 on your primary mortgage, an 85% LTV calculator would show roughly $80,000 in available credit. That's the number the tool gives you. Don't treat it as a guarantee. I built a quick spreadsheet version of this because the generic online calculators were producing wildly inconsistent results. One would use 80% LTV, another 85%, a third factored in property taxes and insurance into some weird debt-to-income adjustment that had nothing to do with the actual credit line. I settled on using 80% as the conservative baseline and built in a field where I could adjust the percentage per lender. The spreadsheet takes about 30 seconds to update when your home value changes. The thing that trips people up most is treating the home value field as static. If you're pulling numbers from Zillow or Redfin, those are estimates, not appraisals. I've seen cases where the Zillow estimate was $30,000 above the actual appraised value, which inflated the calculated equity by about $6,000 at an 80% LTV. That's the difference between qualifying for a $40,000 line and a $34,000 one. Always run a formal appraisal if you're within a few thousand dollars of a threshold that matters to your plans.
Another edge case that caught me off guard: some lenders subtract the estimated payoff of any second mortgages or home equity loans before applying the LTV limit. A standard calculator won't account for this unless you manually enter every outstanding lien. I had a borrower who thought she had $25,000 available based on a public calculator, but the bank's internal model deducted a $12,000 home equity loan she'd forgotten she still carried, leaving her with $13,000. Make sure you input every lien. Every single one. If you want something that handles this properly without digging through lender-specific docs, there's a free Excel template that includes fields for all liens, adjustable LTV percentages, and a column that flags when your calculated equity drops below common thresholds like $10,000 or $25,000. You can find it shared in the r/personalfinance wiki under lending tools. It's been updated a few times over the years and the author posts corrections when lenders change their policies. No sign-up required. The real limitation of any HELOC equity calculator is that it can't factor in your credit score, income verification, or employment history. Two people with identical home equity can walk away with completely different credit line amounts. One might get the full calculated amount with a 780 score and stable income. The other might get 60% of it because of a recent job change or a high debt-to-income ratio. The calculator shows your collateral capacity. It does not show your borrowing capacity.
Get the Full Details

Some lenders also use a combined loan-to-value ratio that includes your planned HELOC draw in the calculation itself. This creates a circular problem where the calculator can't give you a final number until you've already applied. The workaround is to run the calculator at 75% LTV instead of 80% or 85% to leave yourself a buffer. It underestimates slightly but it prevents the disappointment of seeing your approved amount come in thousands lower than the online tool promised. Also worth noting: draws from a HELOC often restart the clock on payment calculations. Some people calculate their available equity and immediately plan to draw the full amount, then discover that the required monthly payment on the drawn balance is significantly higher than they budgeted for. A $50,000 HELOC draw at 8% interest over a 10-year repayment period means roughly $606 per month. That number doesn't show up on the equity calculator. It only appears once you're in the application workflow. Use the calculator as a starting estimate. Run it at a conservative LTV. Subtract every lien you can find. Factor in your credit profile honestly. Then call two or three lenders and ask for a pre-qualification so you can compare actual offers against your spreadsheet numbers. The gap between the two tells you more than either number alone.