Why Most Heloc Calculators Mislead You
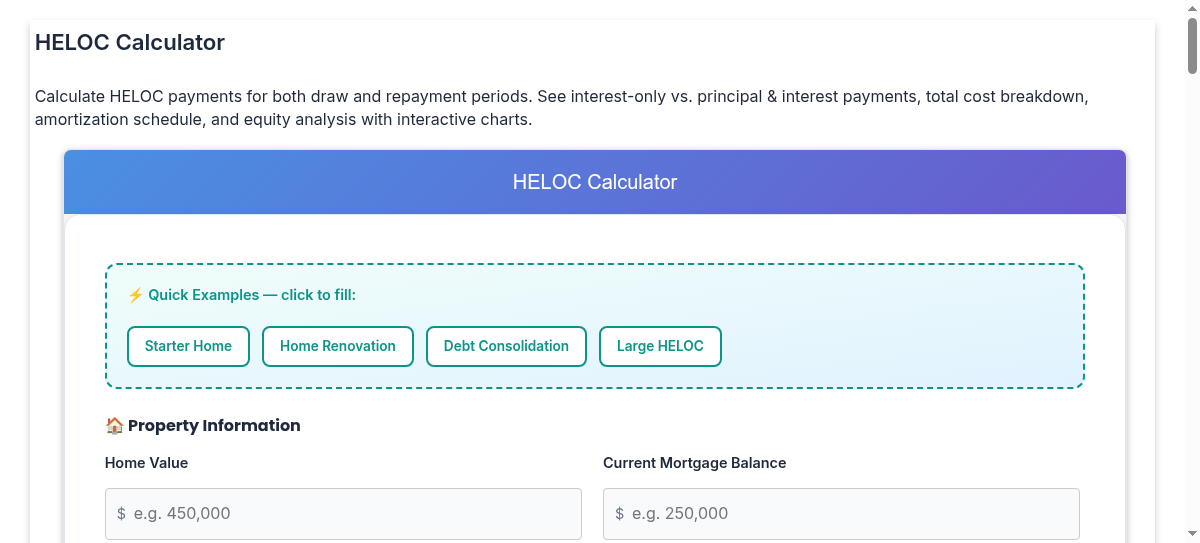
I spent three years running home equity conversions for clients before I realized most of the calculators out there were giving them false confidence. The numbers looked right on the surface. Then the underwriting came back and everything fell apart. The gap is usually in how interest is computed, not in the basic arithmetic. A proper Heloc Line Of Credit Calculator needs to account for draw periods, rate adjustments, and the compounding method your lender actually uses. Too many free tools online just multiply your balance by the annual rate and divide by twelve. That works for a fixed mortgage. It does not work for a HELOC. Start by gathering the specifics that actually move the numbers. You need the approved credit limit, the current variable rate, the length of the draw period, and the repayment period that follows. Note whether the rate is indexed to something like the prime rate with a margin added on top. Some lenders cap how much the rate can adjust each year. Others have lifetime caps. The calculator only helps if you feed it the real terms, not the marketing brochure version. Run a scenario where you draw half your available credit in the first year, then carry that balance through the repayment phase. Watch how the payment jumps when the draw period ends. This is where people get surprised. During the draw period you might only be paying interest, which makes the monthly cost look absurdly low. Once the repayment window starts, you are paying principal and interest on the full remaining balance over a much shorter timeline. The payment can triple without warning.
One calculator field that matters more than anyone admits is the compounding frequency. Daily compounding versus monthly compounding changes the effective annual rate enough to shift your total cost by hundreds over a five-year span. Enter your lender's actual compounding schedule instead of assuming monthly. I learned this the hard way with a client who had a HELOC tied to daily compounding at an 8.5 percent margin over prime. The online tool showed a payment of roughly nine hundred dollars a month during repayment. The actual statement came back at one thousand twenty-eight dollars because the accrued interest during the draw period got capitalized differently than the calculator assumed. That gap cost him an extra four thousand two hundred dollars over the life of the loan.
Edge Cases That Break Standard Calculators
Standard calculators assume a flat rate throughout the draw period. Reality rarely works that way. If your HELOC has annual rate caps or adjustment floors, you need to model those manually in a spreadsheet after the calculator gives you a baseline. I once worked through a case where the prime rate moved forty basis points in a single quarter. The lender's cap structure meant the rate only moved twenty-five basis points. A basic calculator would have projected the full forty, making the borrower panic about a payment that would never actually happen. Running both scenarios side by side showed a difference of about sixty dollars a month. Small, but wrong enough to make bad decisions. Another common failure point is early partial prepayments during the draw period. Some calculators treat any payment above the minimum as if it permanently reduces your available credit. In practice, many HELOCs are revolving. Pay down three thousand, get it back the next month when you charge a renovation expense. The calculator needs to reflect that flexibility, otherwise your payment projection will look steeper than it actually is. Check your disclosure documents for whether your line renews automatically upon repayment or requires a new commitment review.
Get the Full Details
What These Calculators Cannot Tell You
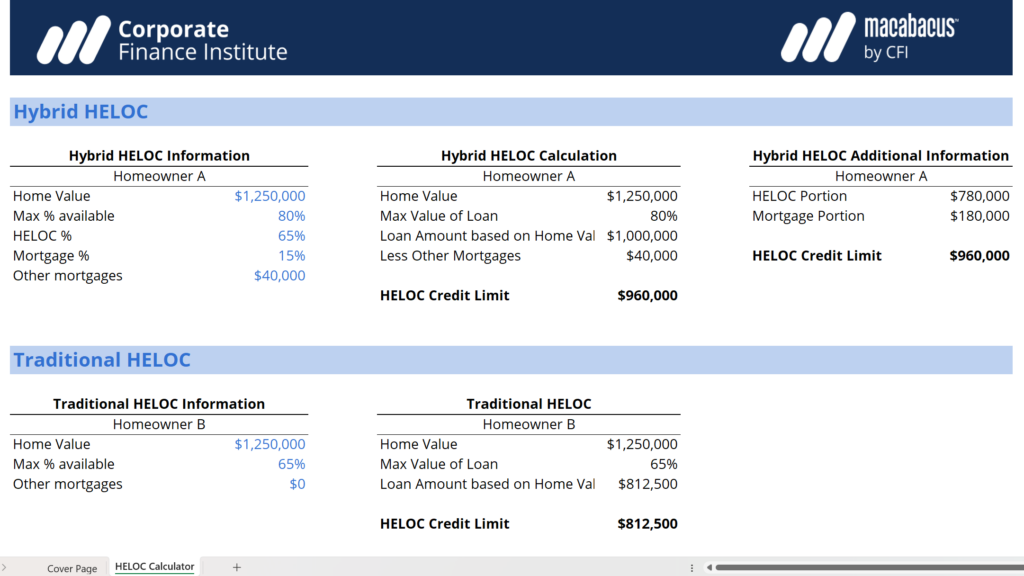
No calculator can predict your personal credit outcome. Approval hinges on debt-to-income ratios, credit score changes, and employment verification, none of which appear in any formula. A clean projection means nothing if your DTI jumped from thirty-two to forty-six because you financed a car during the application process. Use the calculator for budgeting, not as a preview of approval. Calculated payments also ignore closing costs and annual fees. Some HELOCs carry upfront origination fees between five hundred and two thousand dollars, plus possible annual maintenance charges. Factor those into your total cost analysis separately. They do not change your monthly payment, but they do change the true cost of borrowing. When a calculator gives you a number you want to trust, cross-reference it with the lender's own amortization schedule or payment estimator. Lenders are required to provide a Loan Estimate under TRID rules, and that document will show the actual payment breakdown including taxes and insurance if they are escrowed. If your calculated payment differs from the Loan Estimate by more than ten percent, dig into the assumptions you entered. You likely missed a rate cap provision, a compounding detail, or a fee that rolls into the balance.
A Practical Workflow
Run your inputs through a free Heloc Line Of Credit Calculator first to get a rough shape of the numbers. Then build a spreadsheet that models the draw phase month by month, applying the actual compounding method and any rate adjustment caps from your disclosure package. Add a separate column for any capitalized interest that shifts into the principal balance. Compare the two outputs. The spreadsheet version will almost always be higher during the repayment phase, sometimes significantly. Use that higher figure as your planning number so you are not caught off guard when the draw period closes. This approach takes about twenty minutes once you have your disclosure documents open. It prevents the most common regret I hear from borrowers: thinking they can afford a home equity strategy on paper and discovering too late that the payment structure was never what they imagined.