Working with HELOC rates isn't complicated, but it's easy to get wrong if you don't know what the numbers are actually telling you
A home equity line of credit calculator takes your credit score, the value of your home, your outstanding mortgage balance, and the current index rate plus the lender's margin to give you a rough estimate of what your interest rate will be and what your monthly payments might look like during the draw period. That's it. The output is only as good as the inputs you put in, and most people treat it like a crystal ball when it's really just a starting point for a conversation with a loan officer. I spent about four years working in mortgage operations, mostly on the underwriting side for smaller regional lenders. One thing that kept coming up was people using a Heloc Rate Calculator, getting a rate of 7.25%, and then showing up at a bank appointment convinced that's the rate they were going to get locked at. It was never that simple. The calculator doesn't know about your debt-to-income ratio, it doesn't know about your credit history details beyond the score itself, and it definitely doesn't know the specific pricing overlays your lender uses. I had one borrower last year who was approved at 8.1% after we dug into the file. The online tool had quoted him 6.875%. The gap came down to a combination of a recent hard inquiry, a cash-out purpose that flagged his LTV higher, and the fact that his lender had a pricing tier system based on credit score brackets that the generic calculator couldn't replicate. He was upset, but honestly the calculator was doing its job — it was giving him a ballpark figure, not a guarantee.
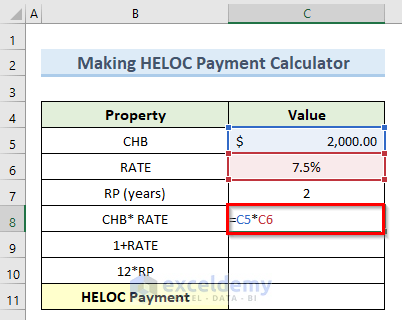
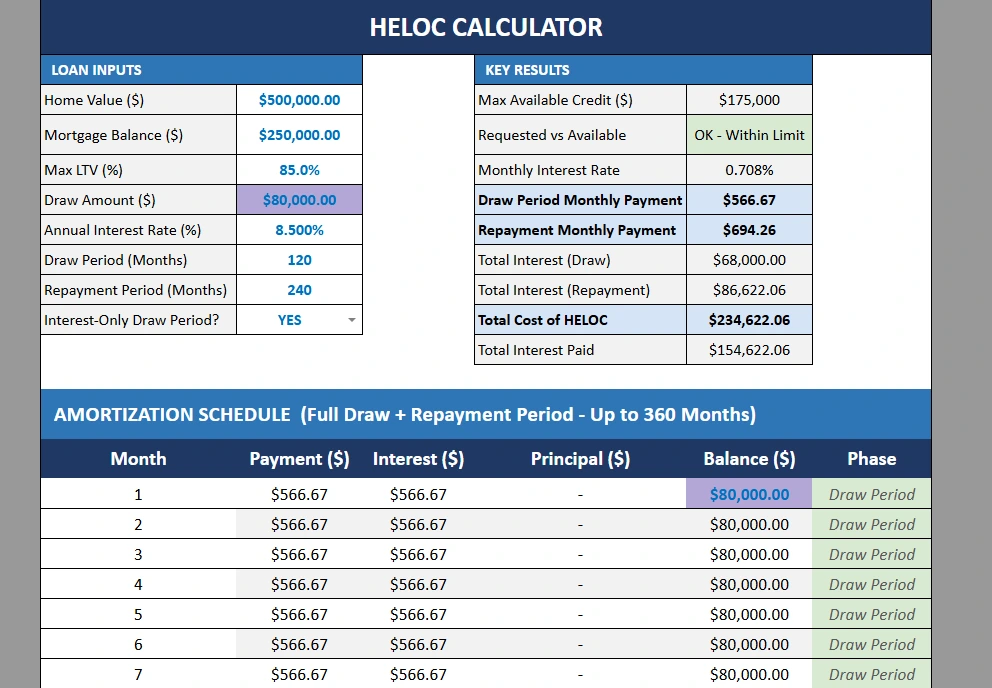
Heloc Rate Calculator
Most calculators of this type work by taking an index rate, usually the Prime rate or the One-Year Treasury, and adding a margin that's determined by your credit tier and loan-to-value ratio. The Prime-based model is by far the most common for residential HELOCs. Right now Prime is sitting around 8.50%, so a typical rate would land somewhere between 8.75% and 12% depending on where you fall on the credit and LTV spectrum. The margin alone can range from 0.25% for someone with excellent credit and low leverage to 4% or more for risk-tiered borrowers. Here's the thing most people miss: HELOC rates are often structured in two phases. During the draw period, which typically lasts 5 to 10 years, you might be eligible for an introductory teaser rate that's below the fully indexed rate. After that period ends, the loan moves into the repayment phase and your rate resets to the full Prime plus margin with no discount. A calculator usually shows you the fully indexed rate, not the teaser. I've seen multiple clients completely blindsided when their payment jumped from $400 a month to over $1,200 once the teaser expired and they still had a significant balance drawn against the line. The calculator can't predict the exact payment increase because it depends on how much you drew and how long you had it, but it can flag the structural risk if you read the fine print around rate transitions. Another nuance that gets overlooked is the compounding frequency. Some HELOCs compound daily and require monthly payments based on accrued daily interest. That means carrying a balance of $50,000 at 9% doesn't cost you exactly $450 a month. With daily compounding, you're looking at closer to $385 during the draw period if you're only paying the interest each month. The difference matters over the life of the loan, especially when you're carrying a large balance for several years. Most basic calculators don't factor in daily compounding because they're designed for quick estimates, not precise amortization schedules. If you need accuracy, you should run the numbers through an actual amortization tool or ask your lender for a disclosure package with the APR breakdown.
The biggest limitation of any Heloc Rate Calculator is that it cannot account for lender-specific pricing tiers, borrower-specific adjustments like debt-to-income ratio, or the impact of your intended use on rate eligibility. Cash-out refinancing combined with a HELOC draw in the same transaction can push your combined loan-to-value ratio into a higher risk bracket that changes your rate significantly. The calculator treats each input independently and has no way of knowing about cross-product pricing or portfolio strategy. You'll get a better answer by calling two or three local credit unions and asking for written rate quotes than by running ten different online tools and averaging the results. Credit unions in particular often have rate structures that don't show up on public calculators because they factor in your membership relationship, direct deposit history, and total banking footprint with them. One practical workaround for getting a more accurate picture is to pull your credit report first, check your exact FICO score, and then run the calculator with that score rather than the rounded version you might guess at. A difference of 20 points between 720 and 740 can shift your margin by half a point or more with certain lenders. Then take that estimated rate and call the lender directly and ask what the actual locked rate would be for your profile. Don't ask for a quote over the phone without putting your name on it, because those preliminary numbers are often the best-case scenario and not reflective of what you'll actually receive. A proper rate lock requires a completed application and documented financials regardless of how simple the product appears. The calculator is a useful screening tool if you keep it in perspective. It helps you understand the general range you're dealing with and prepares you for the conversation with a lender. It does not replace an actual loan estimate, it does not predict your final rate, and it absolutely will not tell you what your payments will be once the draw period transitions. Use it to narrow down which lenders to talk to, not to pick the right one on its own merit.
Get the Full Details