The Practical Realities of Studying the History Of Central Banking
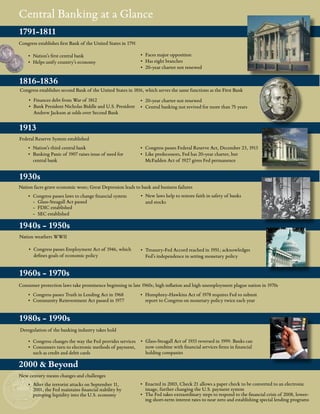
Most people approach this topic from the wrong angle. They start with dates, treaties, and the names of central bankers. That approach produces shallow understanding. The History Of Central Banking is really about power, crisis response, and the tension between public stability mandates and private profit motives. It has been that way since the Bank of England was founded in 1694, and the basic dynamics have barely changed. Central banking did not emerge from academic theory. It emerged because governments needed a reliable way to finance wars without defaulting. The Bank of England lent money to the Crown in exchange for charter privileges and the right to issue notes. That same pattern repeated everywhere: wars forced financial innovation, and the innovations were then repurposed for peacetime monetary control. The Federal Reserve was created in 1913 after a series of panics made it clear that the United States lacked a lender of last resort. The Aldrich Plan that preceded it was heavily influenced by J.P. Morgan and other private bankers who wanted a system that would protect them from runs without ceding control to the Treasury. The compromise structure with twelve regional Federal Reserve Banks still reflects that original bargain between public oversight and private banking interests. You can see the same tension in the European System of Central Banks today.
I spent roughly two years cross-referencing primary sources on this, mostly meeting transcripts from the Federal Open Market Committee before transparency reforms, Bank of England court minutes from the 1970s, and Bundesbank quarterly reports from the inflation period. The most useful material is not what ended up in textbooks. It is the internal memos and backchannel correspondence where the actual decision-making happened.
Why Most Learning Approaches Fail Here
Standard textbooks treat central banking history as a series of isolated events: the gold standard, the Great Depression, Bretton Woods, the Volcker shock. They present each one as if it stood alone. The real pattern is continuity. Every major shift in central banking has been a response to the same fundamental problem: how do you manage a currency system when confidence is fragile and political pressure is constant? Consider the 19th-century free banking era in the United States. Textbooks call it chaotic. The deeper reality is that it was a functional decentralized system that produced its own clearing mechanisms and note-verification networks. The Panic of 1907 exposed its vulnerability to systemic shocks, which is exactly why the Fed was created. The lesson is not that decentralization was bad. The lesson is that it works well until a crisis of sufficient scale makes coordination necessary. Another common mistake is treating the gold standard as some kind of stable baseline that was abandoned for ideological reasons. The gold standard of the 19th century was rigid in theory and highly flexible in practice. Countries routinely suspended convertibility during wars and adjusted their monetary bases accordingly. The interwar attempt to restore it at pre-war parities was the mistake, not the abandonment itself. That restoration attempt is what deepened the Great Depression across Europe.
Get the Full Details
I ran into a specific problem when trying to trace the exact timeline of the Bank of Japan's quantitative easing decisions in 2001. The official records are clean and organized, but they leave out the informal consultations between the Ministry of Finance and the BOJ Policy Board that shaped the final decision. The workaround was to read the memoirs of individual board members alongside the published meeting records and cross-reference dates with newspaper archives from Yomiuri and Nikkei. It took about three weeks of work that the official documents alone could never support.
Key Turning Points That Actually Matter
Ricardian equivalence, which you will encounter in advanced macro courses, is largely irrelevant to how central banks operate. The theoretical argument that government debt does not affect aggregate demand because rational agents save for future taxes has no practical bearing on monetary policy. Central banks do not set interest rates based on whether the private sector is forward-looking. They set them based on inflation expectations, output gaps, and financial stability conditions. The Phillips curve relationship between unemployment and inflation held enough empirical stability from the 1950s to the early 1970s that policymakers treated it as a reliable menu of choices. Milton Friedman's critique that expected inflation would eventually shift the curve was correct, and the stagflation of the 1970s proved him right. But the deeper insight that most people miss is that the breakdown was not just about expectations. It was about supply shocks and the political impossibility of maintaining tight monetary policy long enough to break inflation expectations without triggering a severe recession. Bretton Woods is usually presented as a fixed exchange rate system that collapsed because of structural imbalances. The more useful way to understand it is as a system of managed float with capital controls. Countries maintained near-fixed rates against the dollar, but intervention and occasional realignments were routine. The collapse in 1971 was less a systemic failure than the moment the implicit constraints became impossible to maintain given US fiscal policy and Vietnam War spending.
How to Study The History Of Central Banking Effectively
Start with the institutional architecture before the ideological debates. Understand what problem a central bank was designed to solve in any given era, then trace how that mandate expanded or contracted. The mandate drift from price stability alone to financial stability, climate risk, and industrial policy in various jurisdictions is a recent development that most introductory material glosses over. Primary sources matter more than secondary summaries. The Federal Reserve's historical documents page has thousands of digitized items. The Bank of England's archive includes minutes going back to the 1700s. The BIS publishes annual reports that go back to 1950 and contain remarkably candid assessments of global monetary conditions. Reading these directly is uncomfortable at times. The prose is dry, the acronyms are dense, and the institutional self-confidence can be grating. That is exactly why they are valuable. The weakness of this approach is that primary source research requires substantial time and access to archival materials that may not be digitized. Some central banks, particularly in emerging markets, have limited historical records available online. The workaround is to use academic working papers that cite those records, though you should always verify the citations independently when possible. Secondary literature from economic historians tends to be more reliable than general interest books on the subject.

The biggest blind spot in most histories of central banking is the treatment of non-Western systems. The People's Bank of China operates under fundamentally different constraints and political logic than the Federal Reserve or the ECB. The Reserve Bank of India navigates a currency managed economy with significant capital controls. Ignoring these systems produces an incomplete picture that is increasingly inadequate as global financial architecture shifts.