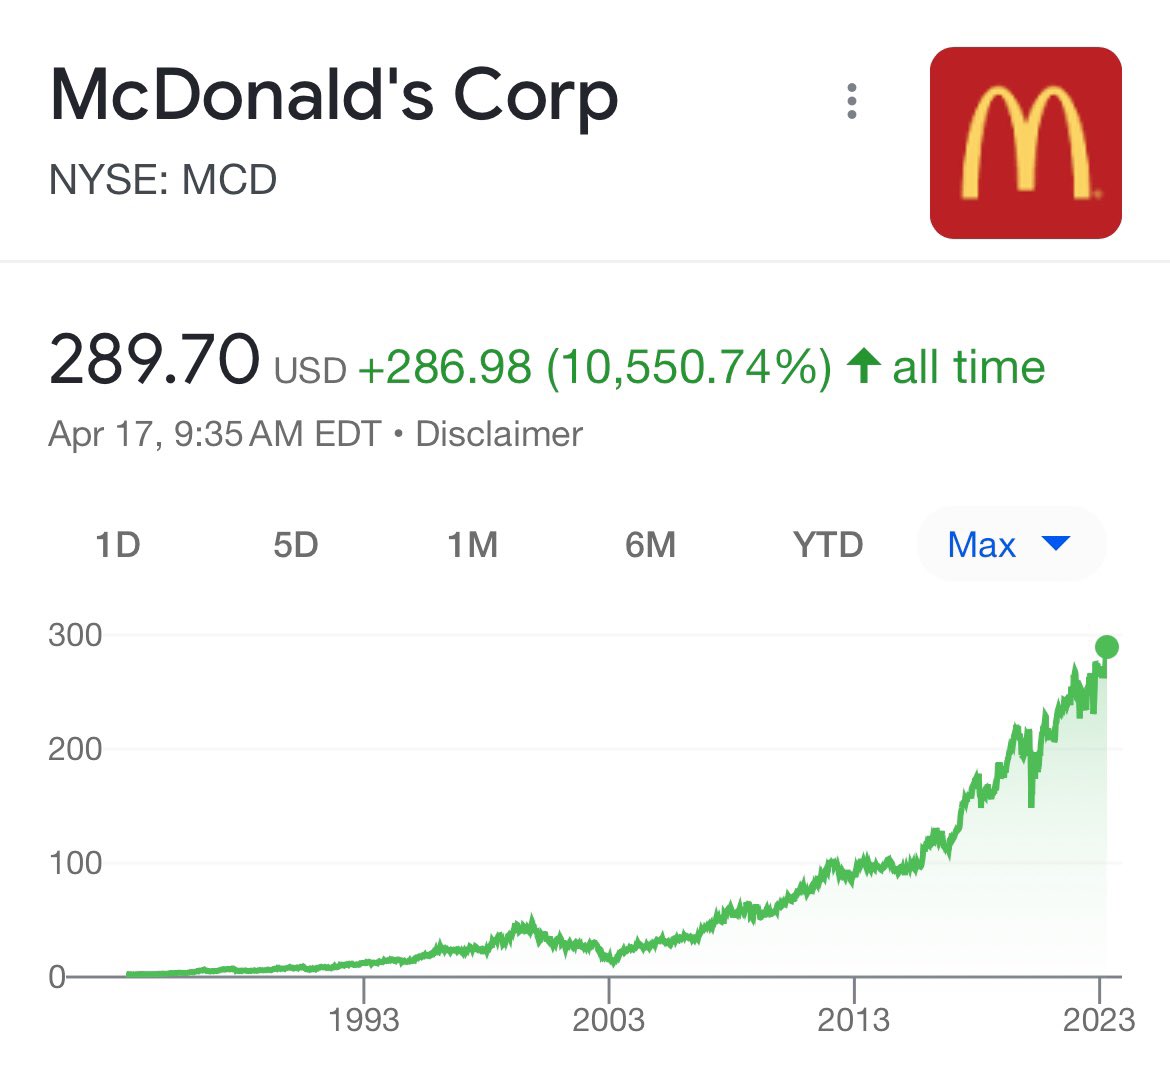
Watching MCD Through Decades of Volatility
The McDonald's Corporation ticker is MCD. If you're digging into the History Of McDonalds Stock, you will quickly realize this is not a stock that moves wildly on earnings alone. It is a bond proxy with a dividend that has been raised for over forty consecutive years. That fact alone changes how you read the tape. People treat it like a safe sleep-well investment until the market decides it is not. McDonald's went public on April 21, 1965 at $2.30 per share on the New York Stock Exchange. Ray Kroc forced the IPO to fund expansion because the company was burning cash opening stores faster than internal capital could support. The split-adjusted price back then is not particularly useful for real trading decisions, but it helps explain why early shareholders sit on returns that look almost absurd from a modern perspective. The first major inflection happened in 1987, when the company restructured after years of sluggish growth. They replaced the CEO, refocused on core markets, and the stock began its long grind higher. I have tracked this ticker through two full bull markets and one brutal bear cycle, and the pattern is clear: MCD drops hard when same-store sales miss, and it recovers slowly because the business is heavy on real estate and light on margin expansion. You do not get surprise pops from cost-cutting here.
Another significant event was the 2015-2016 period, when the stock fell nearly 30 percent because international franchising growth stalled and the CFO admitted the company had been underinvesting in store-level renovations. The board brought in Steve Easterbrook, who pushed the "Accelerating the Arches" plan. The stock recovered, but it took two years of grinding sideways action before investors got their money back. That is the MCD rhythm. Patience is mandatory. The 2020 crash is probably the most well-known recent event. The stock dropped about 35 percent in six weeks when COVID hit and restaurants shut down. What surprised nobody who actually read the filings was how fast it recovered. By mid-2020, drive-thru traffic held up better than expected, and the asset-heavy model where McDonald's owns or controls a massive amount of the real estate became a liability on paper before flipping back into an advantage as lease income stabilized. The stock was back to pre-crash levels by late 2020.
How I Actually Track This Stock
I do not buy charts. I read the 10-K. Specifically, I look at three lines: Same-Store Sales by segment (U.S. vs. International), the Occupied Restaurant Royalty and Rent line in the operating results, and the capital expenditure schedule. Those three numbers tell you everything. The rest is noise. When I was managing a small concentrated portfolio a few years back, I ran into a problem tracking the split-adjusted historical returns through my broker's platform. The data provider had a glitch where the 1987 restructuring splits were not applied consistently across certain date ranges. I ended up with a chart that showed a fake gap that looked like a catastrophic drop, which would have spooked anyone looking at the raw display. The workaround was straightforward: I pulled the raw price data directly from the SEC EDGAR database using the corporate action codes, recalculated the splits manually using a spreadsheet with the exact split ratios from the 10-K amendments, and rebuilt the chart from scratch. It took about forty-five minutes instead of relying on whatever the broker's default settings produced. If you are doing serious research on the History Of McDonalds Stock, do not trust a single data source. Cross-reference Yahoo Finance against the SEC filings. Brokers average out the discrepancies, which is fine for casual investors but misleading if you are trying to backtest a strategy over five decades.
Get the Full Details
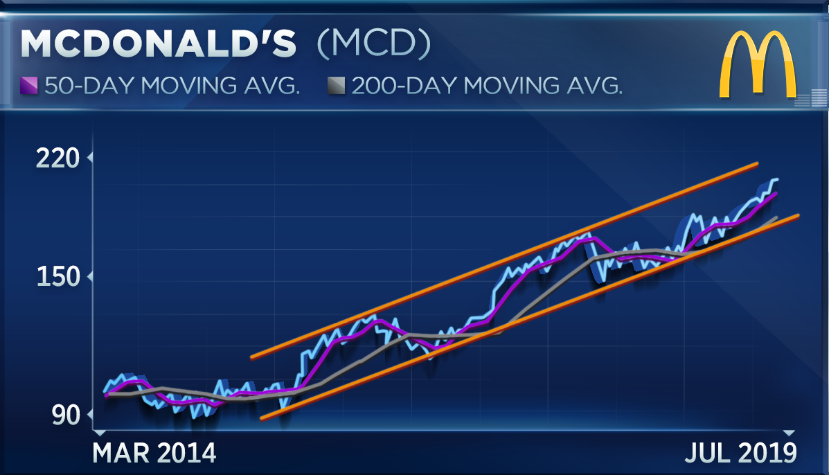
Counter-Intuitive Things About MCD Nobody Talks About
Most people think McDonald's stock is low-beta and therefore stable. It is not. The beta drops during calm markets but spikes above 1.2 during recessions because the business carries fixed lease obligations and the market treats it like a consumer discretionary name when fear hits. I learned this the hard way in early 2022 when rate-hike anxiety pushed MCD down alongside growth stocks despite having zero exposure to interest-rate-sensitive debt structures. The stock was punished for being a stock, not for being a bad business. The second thing beginners miss is the franchise model. Roughly 93 percent of McDonald's restaurants are franchised. This means the revenue that matters most to the stock is not hamburger sales directly. It is the royalty and rent income, which is a percentage of franchisee revenue. When people talk about "McDonald's sales dropping," what actually matters is whether franchisees' same-store sales drop. Corporate margins can stay flat even if unit economics weaken slightly because the cost structure is already baked into the franchise relationship. Watch the franchise-level margins, not just the top-line systemwide sales figure.
What the Dividend Actually Means for Your Returns
McDonald's has increased its dividend every year since 1979. That is roughly fifty years of compound growth at rates that are modest but consistent. The current yield sits around 2.2 to 2.5 percent depending on the share price. If you are buying MCD purely for the dividend, the math works until the payout ratio gets compressed by share buybacks or capital expenditure needs. In 2023 and 2024, the company was spending heavily on menu innovation and digital infrastructure, which trimmed free cash flow. The dividend remained safe, but the payout ratio tightened from about 60 percent to closer to 70 percent. That is manageable but worth watching quarterly. The buyback program runs simultaneously with the dividend increases. McDonald's has been repurchasing shares aggressively since 2020, which reduces the share count and mechanically boosts earnings per share even when net income growth is flat. This is a legitimate reason the stock can climb during periods of mediocre operational performance. It also means the EPS figures you see in annual reports are partially a accounting fiction driven by buybacks rather than pure business growth.
Where This Strategy Breaks Down
The biggest weakness in treating McDonald's as a perpetual hold is valuation risk. At a P/E above 25 times earnings, the stock becomes expensive for a business with single-digit organic revenue growth. I have seen analysts recommend MCD at those levels and then watch the stock stagnate for three years while the multiple compresses back to the mid-teens. The dividend does not protect you from that. A 2.3 percent yield on a stock that falls 15 percent in multiple compression is a loss, not a gain. Another scenario where this approach fails completely is when the company faces a structural market shift. The international franchise model depends on real estate costs staying favorable in developing markets. If China or India sees a sustained surge in commercial lease rates, the franchisee margin squeeze could force McDonald's to subsidize rent and compress royalty income. This has not happened yet, but it is the kind of black swan that the historical data does not protect you from.
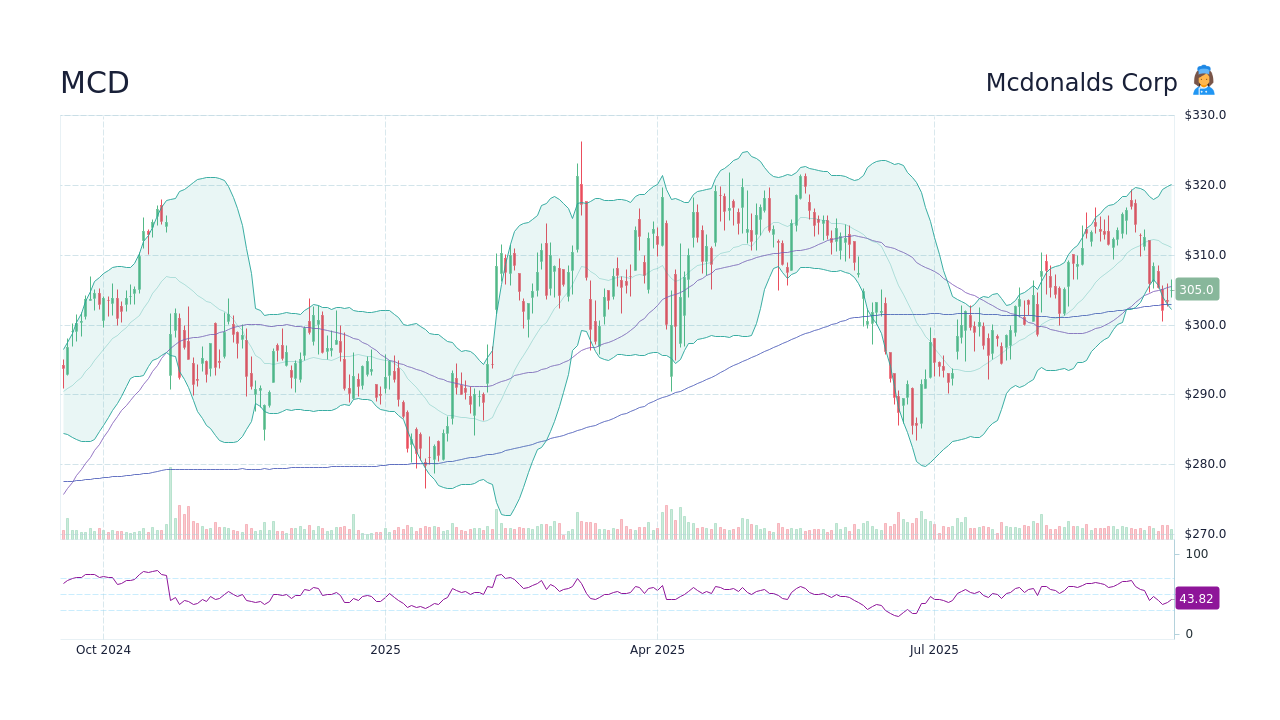
Practical Steps to Research the History of McDonald's Stock Yourself
Start with the SEC EDGAR database and pull every 10-K going back to 1980. Use the corporate actions section to identify every split and dividend change. Export the annual revenue, operating income, and free cash flow into a spreadsheet. Build your own total return curve by adding reinvested dividends at the ex-dividend date price. This manual process takes about two hours for a complete dataset but produces a far more accurate picture than any pre-built chart you will find online. Most data providers smooth over the dividend reinvestment timing, which creates small but compounding errors over decades. For real-time tracking, set up alerts on same-store sales reports. These come out quarterly and are the single most impactful data point for the stock price. A beat or miss of even 0.5 percent can move the share price 3 to 5 percent in a single session. Do not trade the news blindly. The market often prices in expectations before the report drops, and the actual move depends on whether management's forward guidance shifts. Read the conference call transcript carefully. The tone of the CEO and CFO regarding future capital allocation is more informative than the headline number. The takeaway is simple. McDonald's is a long-term compounding machine if you buy at a reasonable multiple and hold through the cycles. It is a value trap if you pay up during periods of market euphoria. The History Of McDonalds Stock is full of examples where both outcomes played out, depending entirely on entry price and holding period. Nothing more complicated than that.


