Building an Amortization Schedule from Scratch
The standard Excel formula for a mortgage payment is PMT(rate, nper, pv). That gives you a single number, but the real work is building out the schedule where every row breaks down principal, interest, and remaining balance. Most people stop at the monthly payment and miss the part that actually matters for decision-making. I built my first one in 2012 for a client who wanted to compare a 15-year versus a 30-year refinance. They kept looking at the monthly payment difference and missing the total interest cost over the life of the loan. The amortization schedule makes that obvious if you actually calculate it properly instead of eyeballing it.
Home Loan Amortization Xls Setup
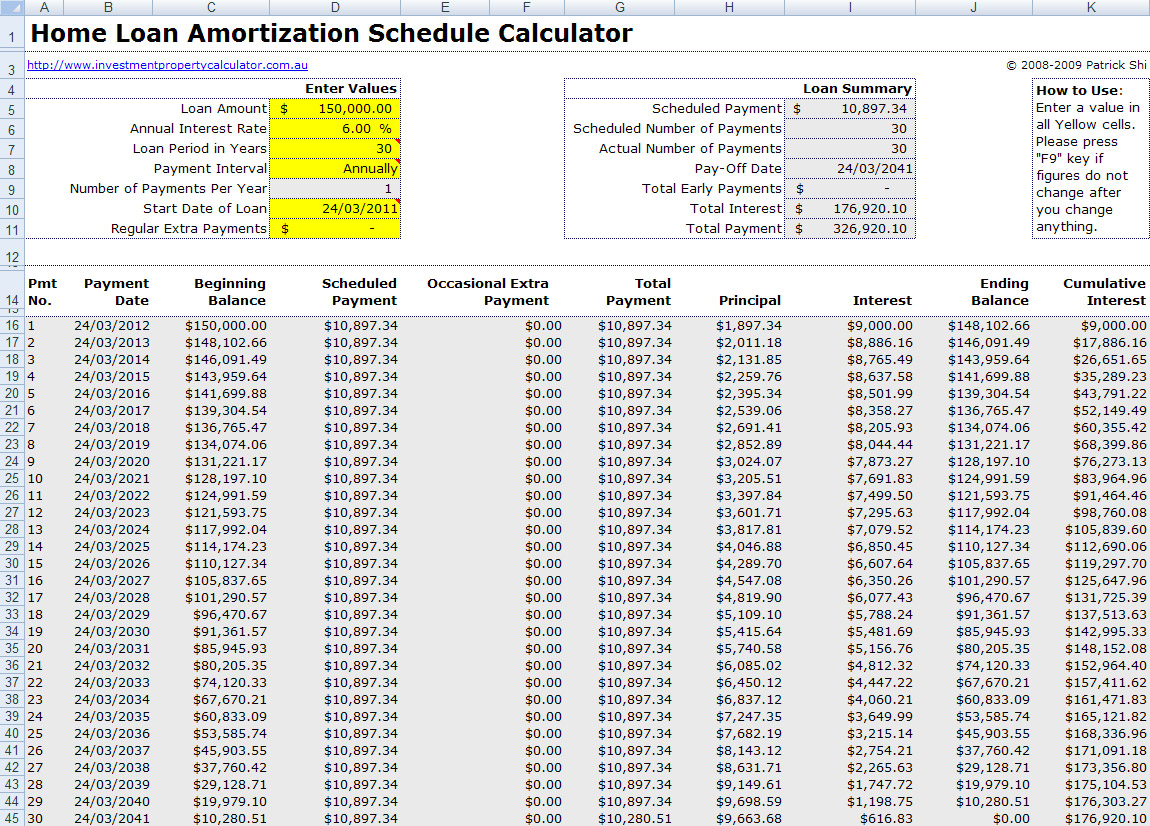
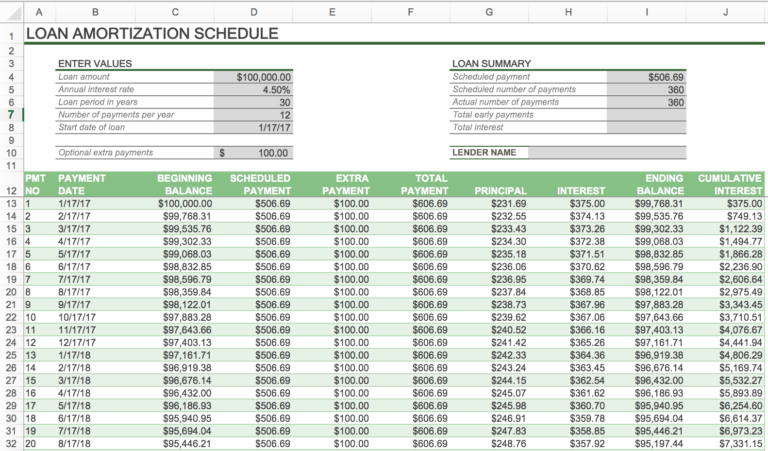
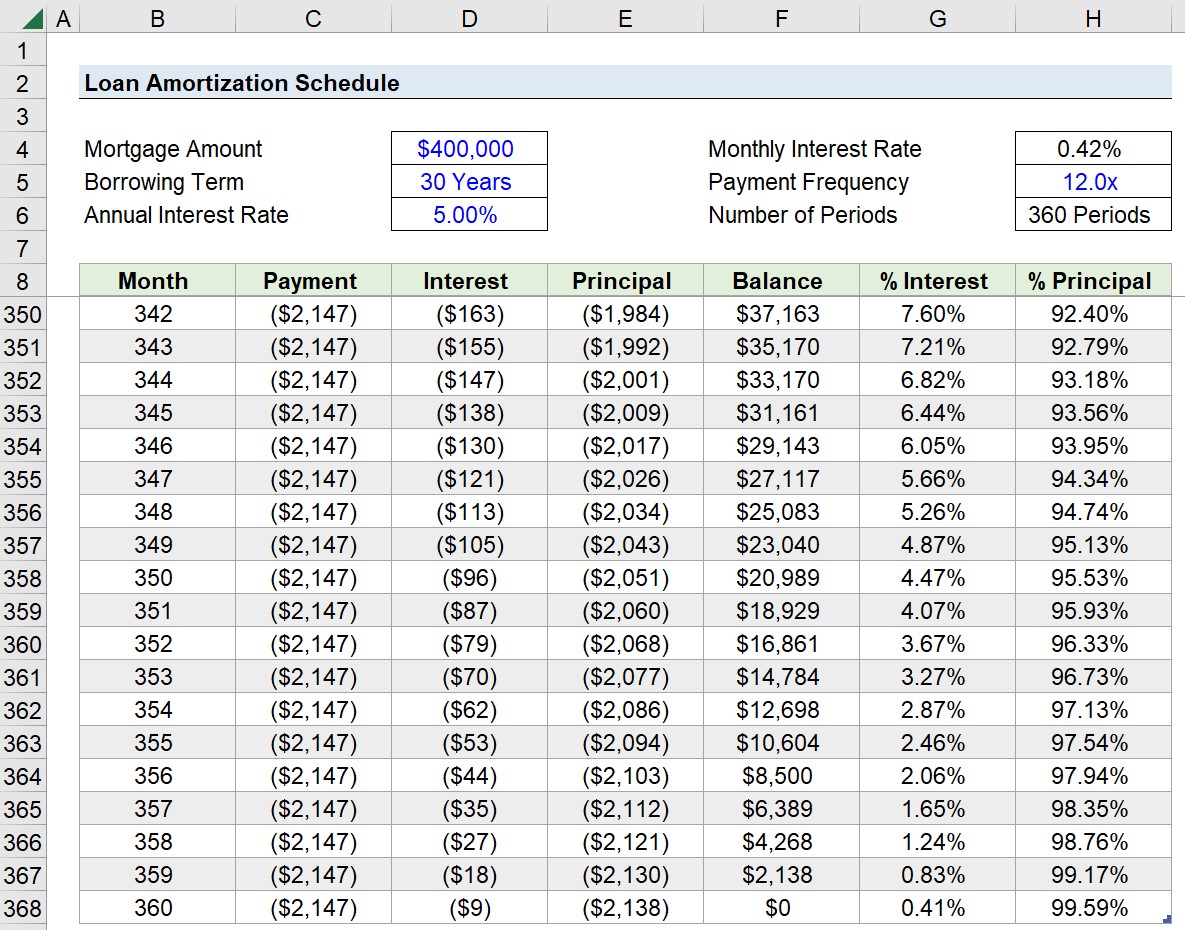
Here's the structure I use. Column A is the payment number. Column B pulls the date by adding one month to the previous row using DATE(year, month+1, day). Column C is the starting balance, which for the first row is your loan amount and for subsequent rows references the ending balance from the row above. Column D calculates interest using =ROUND(B2*rate/12,2). Column E is your fixed monthly payment from PMT. Column F is principal, which is E minus D. Column G is the new balance, which is B minus F. Drag that down for however many periods you need and you have a complete schedule. The ROUND function is not optional. Without it, floating-point errors accumulate and your final balance won't hit zero. You'll end up a few cents off and someone will question the math unnecessarily. One thing I ran into repeatedly: people forget to adjust the rate input for monthly compounding. If your annual rate is 6.5%, you divide by 12 in the formula, not multiply. I've seen this mistake cause payment differences of $40 to $60 per month, which sounds small until you compound it across 360 payments.
Common Problems and Workarounds
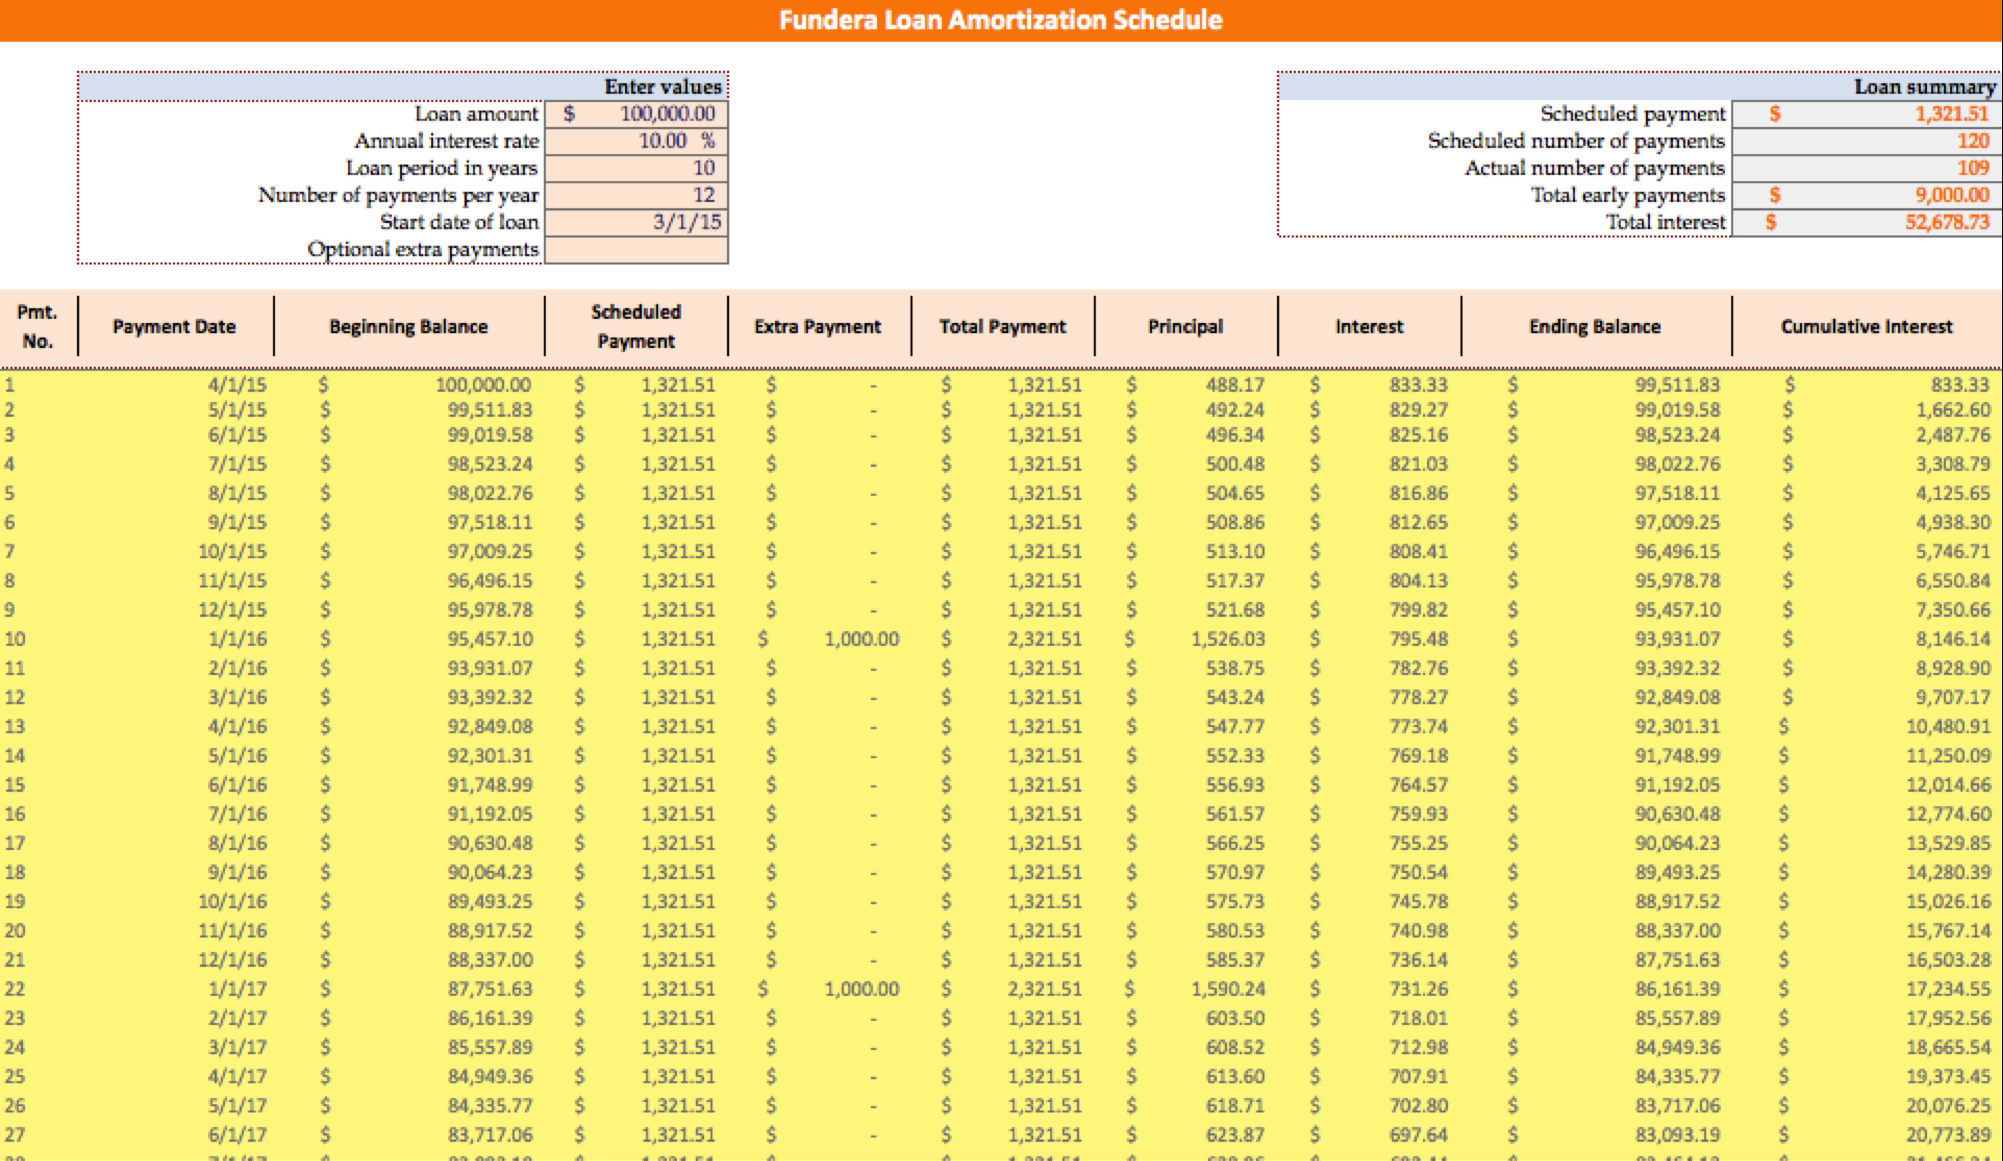
The most common issue I deal with is when someone tries to use their amortization schedule to model early payoff or extra payments. The basic structure breaks because every row depends on the row above it. Add a lump sum payment in month 24 and suddenly your entire schedule after that point is wrong. The workaround is to add columns for additional principal payments and then recalculate the interest portion based on the adjusted balance each month. It adds complexity but it's necessary if you're actually going to use this for planning purposes. I usually add a column for "extra principal" and modify the balance formula to subtract both the regular principal and the extra amount before carrying the balance forward. Another edge case: loans with irregular first periods. Some loans don't close on the first of the month, which means the first payment covers a shortened or extended initial period. The interest calculation changes because you're not getting a full 30-day period. I handle this by calculating daily interest for the first period using =BALANCE*daily_rate*days_in_period and then switching to the standard monthly formula for subsequent rows.
Get the Full Details
There's also the issue of tax-affected payment analysis. If you're modeling after-tax cash flow for an investment property, you need to factor in the mortgage interest deduction. The schedule itself doesn't do this automatically. I add a separate section that sums the interest column year by year and applies the marginal tax rate to estimate the actual tax benefit. This is where the spreadsheet becomes useful for actual financial planning instead of just being a curiosity.
Limitations to Be Honest About
A simple amortization spreadsheet has significant blind spots. It assumes a fixed rate throughout the entire loan term. If you're dealing with an ARM, you need to rebuild the schedule at each adjustment date with the new rate and recalculated payment. That's doable but it requires either multiple sections in your spreadsheet or conditional logic that gets messy fast. It also doesn't account for escrow. Property taxes and insurance are typically bundled into the monthly payment, and those amounts change over time. A proper analysis would need separate inputs for tax rate, insurance cost, and any escalation assumptions. Most basic templates skip this entirely. Prepayment penalties are another thing that doesn't appear in any standard formula. If the loan you're analyzing has a penalty clause that declines over time, you need to model that separately. I've seen people commit to refinancing based on a spreadsheet that didn't include a 3% prepayment penalty in years one through seven, which completely reversed the projected savings.
For basic comparison purposes between two fixed-rate loans, a simple Home Loan Amortization Xls works fine and takes about 20 minutes to set up if you know what you're doing. For anything involving variable rates, prepayment strategies, or tax considerations, you're better off using dedicated mortgage software or hiring someone who builds these for a living. The spreadsheet approach becomes unreliable once the variables multiply beyond what you can reasonably track in a flat grid. The biggest practical use I find for these spreadsheets is showing borrowers the difference between making one extra payment per year versus paying the standard amount. The math is straightforward to model and it tends to open people's eyes faster than any verbal explanation about how principal reduction accelerates over time.