What Home Loan Calculator Compare Actually Does
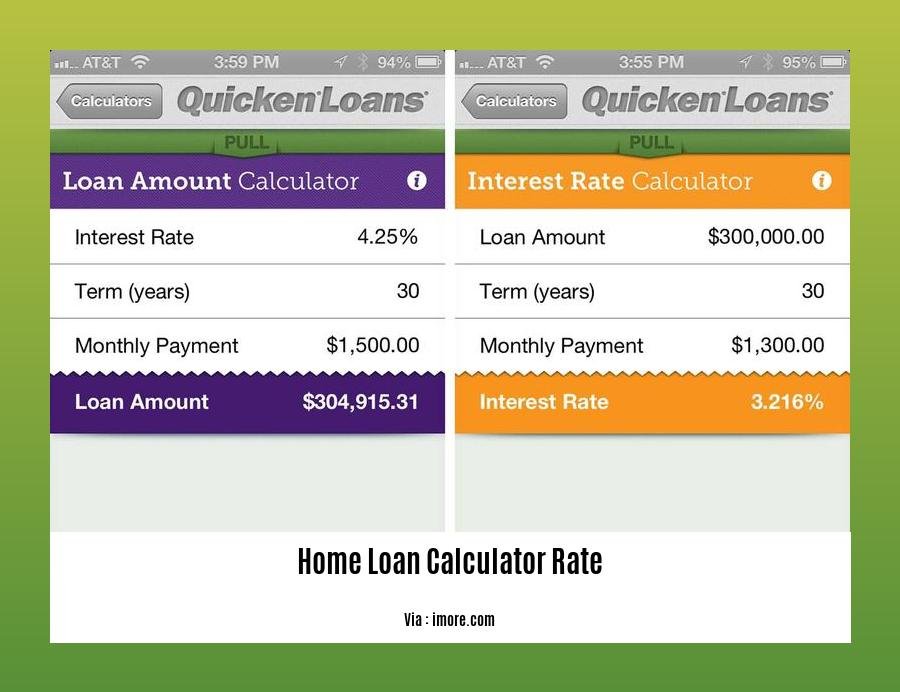
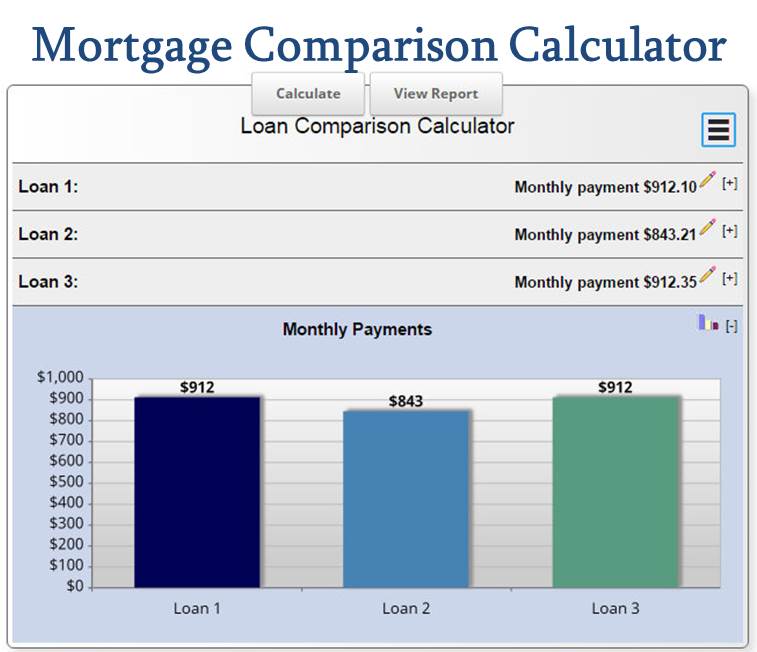
A Home Loan Calculator Compare tool lets you plug in different loan scenarios side by side so you can see how interest rates, down payments, loan terms, and monthly payments change across multiple lenders or loan types. Most of these calculators generate a comparison table and sometimes amortization schedules for each option you enter. The idea is to stop guessing and get numbers on screen. The basic workflow is straightforward. You open the calculator, enter your home price, down payment percentage, credit score range, and desired loan term. Then you input rate quotes from different lenders or loan programs — usually a conventional 30-year fixed, a 15-year fixed, and maybe an ARM. Hit calculate and you get side-by-side monthly payments plus total interest paid over the life of each loan. That's the surface-level use. Here's where people mess it up. They only compare the monthly payment and ignore the annual percentage rate, or APR, which includes lender fees, origination charges, and mortgage insurance. A loan with a slightly higher rate but lower fees can end up costing less overall than a zero-fee loan with a rate point higher. I've seen borrowers choose the cheaper-looking payment only to discover they were thousands ahead by picking the other option.
Another thing most people skip is factoring in private mortgage insurance. If your down payment is under twenty percent, PMI is usually tacked onto your monthly payment until you hit that equity threshold. Some calculators include this automatically. Many don't. When mine didn't, I had to manually add one point two five percent of the loan amount annually divided by twelve to the payment field. That changed the comparison significantly. Here's a practical example. Say you're looking at a four hundred thousand dollar home with six percent down. That gives you a three hundred seventy-six thousand dollar loan. Lender A offers seven point two five percent with one point five points in fees. Lender B offers seven point fifteen percent with no fees. A naive comparison based purely on rate would pick Lender B. But when you run the full numbers including the cost of those points, Lender A's monthly payment ends up being roughly thirty dollars higher, yet the total interest over thirty years is about eight thousand dollars less because the point system buys you a better rate upfront. Down payment strategy matters more than people think. Going from five percent down to ten percent doesn't just increase your equity. It can drop you into a different mortgage insurance bracket or eliminate it entirely depending on the loan type. FHA loans have a twist here — their mortgage insurance premium is required for the life of the loan regardless of how much equity you build, which fundamentally changes the comparison math. Conventional loans drop PMI at twenty percent equity automatically.
The trick with any comparison calculator is to keep every variable constant between options except the ones you're actually testing. If you change the loan term on one and the rate on the other, the output becomes noise. I set up a spreadsheet alongside the calculator to lock down property taxes, homeowners insurance, and HOA fees so those don't get mixed into the payment comparison. Some online tools lump those into the total monthly payment field and then your side-by-side view is comparing apples to oranges.
Get the Full Details
Common Pitfalls and Where These Calculators Fall Short
These tools are useful but they have real blind spots. They rarely account for closing cost variations between lenders beyond what you manually enter. They don't factor in how your debt-to-income ratio might disqualify you from the lower-rate option at a given lender. And almost none of them show you the break-even point for buying discount points — that's something you have to calculate separately. I ran into a specific issue last year where a borrower was comparing a five hundred thousand dollar conforming loan against a jumbo option. The calculator showed the jumbo rate was only two tenths of a percent higher. What it didn't show was that the jumbo loan required a six hundred eighty credit score minimum and a two hundred fifty thousand dollar reserve requirement. Our borrower had a six hundred sixty score and wasn't going to qualify. The comparison was irrelevant from the start. This is why I always cross-reference the calculator output with actual pre-approval requirements before getting too attached to any numbers. Another edge case involves adjustable-rate mortgages. The calculator will show you the initial teaser rate and maybe the cap structure, but it won't accurately model what your payment looks like after the first adjustment if rates move significantly. I've worked around this by running the ARM scenario through at three different rate environments — current, plus two hundred basis points, and plus four hundred — to get a sense of the range rather than trusting the single number the calculator produces.
If you're comparing refinances rather than purchase loans, the calculus shifts entirely. Your existing loan balance, remaining term, and whether you're doing a cash-out refi all change the comparison dynamics. Purchase loan calculators sometimes handle this poorly because they're built around a full loan amount rather than a paydown scenario. I use a separate amortization estimator for refinance comparisons and only use the Home Loan Calculator Compare for purchase scenarios where the variables are cleaner. The best use case for these tools is narrowing your search to two or three qualified lenders and running the same parameters through each to find genuine differences. They're not great for browsing dozens of rates because most free calculators let you enter only two or three options at a time. Beyond that, the data becomes harder to read and the accuracy drops because you're carrying more manual entry burden. One last thing that isn't obvious — tax implications. Mortgage interest deductions have been capped at seven hundred fifty thousand dollars of acquisition debt since the TCJA, and standard deductions have risen. For many buyers in higher tax brackets, the effective after-tax cost of a higher-rate loan can be surprisingly competitive with a lower-rate option because the interest shelter works differently depending on your bracket. The calculator won't tell you this. A quick check with a CPA or using an after-tax cost spreadsheet will save you from picking the wrong option based on pre-tax numbers alone.