Why You Need a Proper Washington State Home Loan Calculator
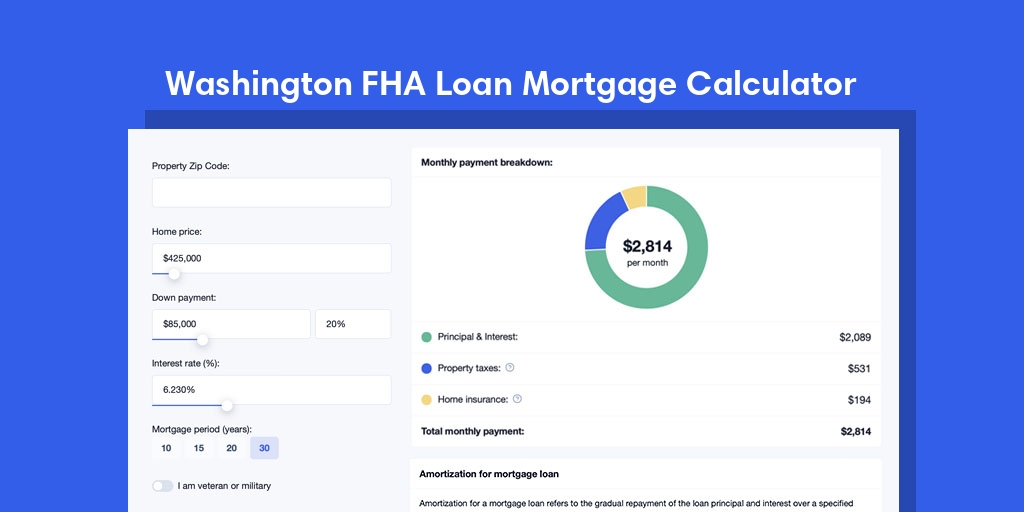
Most people grab a generic mortgage calculator off Google and plug in their numbers, then wonder why their actual monthly payment is $200 higher than expected. Washington has specific property tax rates, transfer taxes, and disclosure requirements that change the math significantly compared to a national average. A Home Loan Calculator Washington State gives you a more realistic picture because it accounts for Puget Sound region taxes, potential homeowners association fees, and the state's unique mortgage recording tax structure.I spent years running numbers for buyers across King County and Spokane. The first time someone brought me a calculation from a basic calculator, I almost laughed out loud. They'd been budgeting on $1,800 a month when the real number was closer to $2,150. Property taxes in Snohomish County alone can add several hundred dollars. The gap usually comes from ignoring Washington's real estate excise tax and local assessment variations. I switched everyone to a state-specific calculator after that, and it saved me from having awkward conversations later when budgets didn't hold up.
How to Use a Home Loan Calculator Washington State
Get your calculator first. There are free versions online that are decent, and some paid tools offer more granular breakdowns. Once you have one, here is the process. Start by entering the purchase price of the home. Then input your down payment percentage. Washington lenders typically look for at least 5 to 20 percent depending on the loan program. If you have a first-time buyer program through the Washington State Housing Credit Authority, that changes things too, so factor that in early.Next, enter the interest rate. Don't guess. Call at least three lenders and get actual quotes. Rates vary by credit score, loan type, and market conditions. A quarter-point difference on a 30-year fixed loan in the $450,000 range changes your monthly payment by roughly $80 to $100. That compounds significantly over the life of the loan. Now comes the part most people skip. Property taxes. Washington county assessors determine assessed values, and these vary wildly. King County averages around 0.9 percent of assessed value annually, while some rural counties run lower. Enter the most recent property tax amount from the listing or the county assessor's website. Do not use the national average of 1.1 percent unless your research confirms it. I once had a client who used the national average on a home in Spokane County where the actual rate was 0.68 percent. He overestimated his monthly payment by nearly $150 and almost walked away from a good deal.
The Hidden Washington-Specific Costs Most Calculators Miss
Washington has a few costs that appear on closing but get left out of basic calculators. The mortgage recording tax is one. It runs about 0.57 percent of the loan amount in most counties. On a $400,000 loan, that is roughly $2,280 sitting in closing costs. Some counties like King have slightly different rates, so verify the exact figure for your area.Then there is the real estate excise tax, or RET. Sellers typically pay this at closing, but it is baked into the purchase price. It matters when you are comparing homes across county lines because some jurisdictions impose additional local RET surcharges. I ran into this when a buyer was looking at a home in Thurston County versus Pierce County. The same home price had different tax implications, and a generic calculator completely missed the nuance. Homeowners association fees are another blind spot. If the property is in a condominium or planned unit development, the HOA monthly fee can range from $100 to $500 or more. StrongHOA fees sometimes include insurance, water, and maintenance, which affects your actual housing cost. Always confirm with the seller or listing agent what the HOA covers before you lock in a budget.
Advanced Pitfalls When Calculating Your Washington Mortgage
One counter-intuitive thing about Washington mortgages is the way escrow shortages get handled. Lenders require escrow accounts for taxes and insurance in most cases, but if your property tax reassessment jumps at the start of the year, your monthly escrow payment can be recalculated mid-year. I saw this happen repeatedly in areas near new developments where assessed values spiked after surrounding construction. Your calculator will show a stable payment, but the actual statement from the lender may increase by several hundred dollars once the tax reassessment rolls through. Factor in a buffer of at least 5 to 10 percent for tax increases, especially in rapidly appreciating markets like parts of Snohomish and King Counties.Get the Full Details

Another thing people get wrong is how points affect the effective rate. Discount points lower your interest rate, but they also increase your closing costs upfront. A common mistake is looking only at the monthly payment without considering the break-even point. If you pay two points to drop your rate from 6.75 percent to 6.25 percent on a $500,000 loan, you are spending $10,000 upfront to save maybe $60 a month. That is a break-even period of over 16 years. Unless you plan to stay in the home well beyond that, points rarely make sense. I tell clients to run the break-even calculation before committing to any point purchase.
When a Calculator Falls Short
No calculator, no matter how Washington-specific, will give you a perfectly accurate number until you are under contract. The final number depends on your credit score, debt-to-income ratio, loan program selection, and the appraised value of the home. If the appraisal comes in low, your loan amount changes, and so does everything else. Calculators are estimates, and you should treat them as such. They are useful for initial budgeting and comparison shopping, but they are not binding.If you need precision, work with a loan officer who can run a Loan Estimate using actual rate locks and your full financial profile. A Home Loan Calculator Washington State gets you in the ballpark, but only a formal pre-approval gives you the exact figure. I recommend using the calculator first to set realistic expectations, then moving quickly to a lender once you find a property that fits your numbers. In a competitive market like Seattle or Bellevue, hesitation costs more than a slightly inaccurate estimate.