Building an Extra Payment Mortgage Calculator in Excel
Most people don't actually need to buy software for this. A properly structured Excel sheet will do the job better than half the paid tools out there, mostly because you can see every number and catch your own mistakes before they compound. I built my first one back in 2013 and have refined it several times since.Home Mortgage Calculator Extra Payment Excel Setup
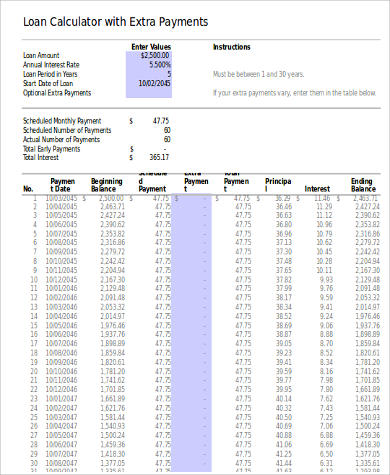
Start with the raw loan details. Create a section near the top with labeled cells for Principal Balance, Annual Interest Rate, Original Loan Term (months), and Monthly Payment. These are your inputs. Everything below them is derived. I use a light yellow fill on input cells so I always know what I can change without breaking the model. The monthly payment formula is where people mess up. Use PMT, not a hand-written amortization formula. The structure is: =PMT(rate/12, nper, -pv)
Rate is your annual percentage rate divided by 12. Nper is the total number of payments over the original term. PV is the principal amount, entered as a negative so the result comes out positive. This gives you the baseline payment before any extra principal goes in. Now build the amortization schedule. Column A is the payment number. Column B is the date. Column C is your regular monthly payment. Column D is the interest portion, which equals the previous balance multiplied by the monthly rate. Column E is the principal portion, which is column C minus column D. Column F is the new balance, which is the previous balance minus column E. Drag that down for the full term. Here is where the extra payment logic lives. Add a column called Extra Payment. If you want to test different scenarios, put your extra amount in a single cell at the top and reference it. If you want to vary the extra payment month by month, fill that column manually. The key adjustment is that your principal column becomes: regular principal portion plus the extra payment. The balance then drops faster, which reduces the interest in the next period, which frees up more of the regular payment for principal. It cascades.
I ran into a specific problem a couple years ago that took me half a day to track down. I was building a calculator for a client who was making biweekly payments instead of monthly, and tacking on extra principal on top of that. The model showed a payoff date that was about eight months earlier than an independent online calculator. The discrepancy came from how Excel handles the PMT function versus the actual compounding. PMT assumes end-of-period payments. The online tool I was comparing against was using a slightly different day-count convention. I ended up just abandoning PMT for the base case and building the entire schedule manually from first principles — interest = balance × (annual rate / 365) × days in period. It was slower to set up but mathematically bulletproof. That is probably the single most important thing I can tell you: PMT is convenient but it can introduce small errors depending on your lender's actual computation method. For most residential mortgages it is close enough, but if you are doing this for actual financial decisions, verify against your loan disclosure documents. Once the schedule is built, add a summary section that pulls the key numbers. Total interest paid with the extra payments versus without. The payoff date. The total principal paid down by year. I use a simple pivot or just SUMIFS formulas to aggregate by year. That summary is what actually convinces people to make the extra payments, because seeing the total interest drop from, say, $187,000 to $94,000 over the life of a 30-year loan at 6.5 percent is something that sticks with you. One counter-intuitive thing most people miss: the timing of extra payments matters far more than most calculators show. If you throw an extra $500 at the principal on payment one versus payment twenty-four, the difference is not trivial. Interest is calculated on the remaining balance. Hit it early and you save interest on that $500 for every remaining month. I once saw someone structure their model to only apply extra payments at the end of the year, which basically neutered the impact. If your lender allows it, apply extras as soon as possible after each regular payment clears.
Get the Full Details

Another thing people get wrong is thinking that pre-paying the same dollar amount every month has a constant effect. It does not. The benefit is front-loaded. The first extra principal payment you make saves you the most interest because it reduces the balance that future interest is calculated on. By year fifteen, an extra $500 a month is doing significantly less work than it was in year one. This is why the summary by year matters — it shows the diminishing returns in real numbers. There are limitations to be honest about. Excel models like this assume the interest rate never changes. If you have an adjustable-rate mortgage, you need to rebuild the schedule at each adjustment date or add a separate branch for each period. It gets messy fast. Also, most lenders do not let you apply partial extra payments without specific instructions — some will just treat them as a prepayment of the next month's bill rather than pure principal reduction. Your calculator will look great but the real-world outcome could be different if you do not confirm how your servicer actually handles the money. Always call and ask whether extra principal payments are applied immediately to reduce the amortization schedule or if they sit in a suspense account for a billing cycle. If you need this to handle ARMs or complex scenarios, stop trying to force it into one big spreadsheet. Build separate sheets for each rate period and link them, or move to a proper financial modeling tool. Excel is fine for fixed-rate residential loans with straightforward extra payment strategies. Beyond that, the model becomes fragile and you spend more time maintaining it than you save in analysis time.
To get started, create the input section, lay out the amortization table with the columns I described, add your extra payment column, and drag the formulas down. Test it against your actual loan statement for the first six months. If the numbers match, you have a working model. If they do not, go back and check your day-count convention and whether your lender compounds daily or monthly. That is usually where the divergence happens.