How to actually figure out what you walk away with after selling your house
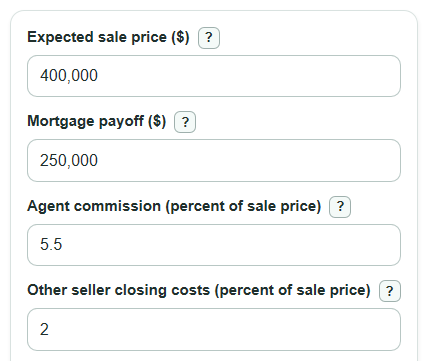
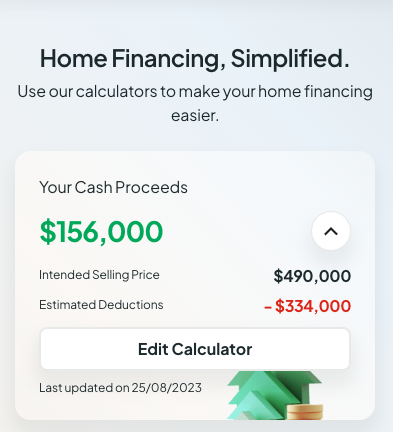
Most people think selling a home is just listing price minus mortgage. That's roughly half the battle and usually the wrong half. The real math involves transfer taxes, title fees, agent commissions that eat six to seven percent, prorated property taxes, and whatever escrow holdbacks your county throws at you. If you're not tracking these, your closing statement will look nothing like your expectation.I've watched folks get stung by surprise costs dozens of times. One guy in my area sold a condo and had no idea his HOA was charging a transfer fee of twelve hundred dollars. Another seller didn't factor in the local documentary stamp tax on the deed, which in some counties runs point one percent of the sale price. These aren't theoretical items. They show up on your HUD-1 or Closing Disclosure and they come out of your pocket. Before you run numbers, you need to understand what goes into them. A solid Home Proceeds Calculator asks for your expected sale price first. That's your starting point. From there it pulls out the commission, whichever comes to mind first for your area, and subtracts closing costs. What most calculators miss, and what you need to add manually, are the variable costs like home warranty, inspection repairs, staging, and mover fees. These aren't fixed. They depend on the condition of your property and how long you plan to list it. Here's the practical way I do it. Take your sale price, subtract the commission at your negotiated rate. Then subtract the payoff amount on your current mortgage, which you get from your lender thirty days before closing. Next, pull a list of typical closing costs in your county. That number varies wildly. In Florida it might be three percent. In New York it could be closer to four. Add in any seller-paid repairs, the home warranty if you're offering one, and the transfer taxes. What's left is your estimated net proceeds.
I run everything through a simple spreadsheet because online tools often default to national averages, and your actual costs rarely match an average. My spreadsheet has columns for commission, title insurance, escrow fees, prorated taxes, and whatever else comes up during the listing process. When I finish, I usually have a range, not a single number, because the final figure depends on negotiations that happen right before closing.
The edge case nobody warns you about
There's one scenario where calculators completely break down. It happened to me with a seller who owned a property outright, no mortgage. She expected the proceeds to equal the sale price minus the usual six percent commission. What she didn't account for was a mechanic's lien from an old contractor who did work two years prior. The lien sat on the title, invisible until the title search came back. It ate four thousand dollars. That's not something a calculator can predict. It's a research problem, not a math problem. Another headache is capital gains tax. If you haven't lived in the home for at least two of the last five years, you may owe federal tax on the profit. The exclusion is up to twenty-five thousand dollars for single filers and fifty thousand for married couples filing jointly. After that, the rate is either fifteen or twenty percent depending on your income bracket. Some calculators ask if you qualify for the exclusion. Most don't ask at all. You need to figure this out yourself or talk to a CPA before you list.
Get the Full Details

What good calculators actually do
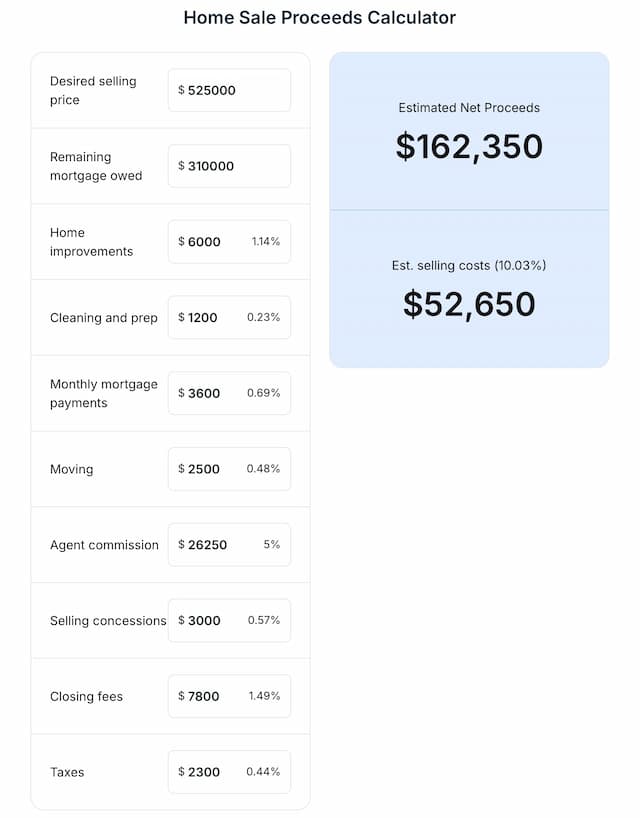
A useful Home Proceeds Calculator should break out every line item on the settlement statement. Commission. Title search. Recording fees. Transfer taxes. Owner's title policy. Lender's title policy if you're assuming debt. Prorated HOA dues. Any credits the buyer negotiates. The best ones also let you adjust each variable so you can see how changing the commission rate or the repair budget affects the final number. I've used free tools from real estate sites and they're fine for rough estimates. They usually assume standard commission splits, which works if you're not renegotiating. They also rarely account for state-specific fees. If you're in Texas, you need to know about the affidavit of value and the recording surcharge. If you're in California, document transfer tax is calculated differently by county. Generic calculators miss these details. Local ones sometimes include them, but you have to verify that the data is current. There's also the matter of seller concessions. These are credits the seller gives the buyer to cover closing costs or repairs. A common mistake is treating concessions as extra expenses when they're really just shifting where money goes. Concessions don't vanish from the transaction. They reduce your net proceeds dollar for dollar, same as any other cost. Just make sure the calculator tracks them separately so you can see the impact on your bottom line.
When to stop guessing and start verifying
Two weeks before closing, request a Good Faith Estimate or Closing Disclosure from your title company. Compare every line item against your spreadsheet. You'll spot discrepancies immediately. This is also when you discover things like outstanding homeowner fees, special assessments, or utility balances that need to be settled before transfer. These costs are small individually but add up fast. If your calculator shows a positive number but your actual closing statement is thinner, something slipped through. Common culprits include unrecorded liens, back taxes from the previous owner that somehow rolled into your escrow, or a miscalculation on prorated property taxes. Taxes are especially tricky because they depend on the assessment date, which varies by jurisdiction. Some counties prorate based on the fiscal year. Others use the calendar year. Get this wrong and you'll be off by a few hundred dollars at minimum. I don't rely on any single tool for the final number. I run three different calculators, cross-check the results, and then build my own model in Excel. It takes maybe twenty minutes, and it catches errors that automated systems consistently miss. The main thing to watch is double-counting. Some calculators include transfer tax in the closing cost column and also list it separately. Once you notice the pattern, you can adjust accordingly.
A few hard truths
No calculator gives you a guaranteed number. The market changes between listing and closing. Buyers renegotiate. Inspection findings create new costs. Your appraisal might come in low and force you to adjust the price. All of these shift your proceeds after you've already done the math. The best you can do is build a range and plan for the low end. Another reality is that your actual commission is negotiable. Six percent isn't law. Agents in competitive markets often accept four or five percent on higher-priced homes. If you're working with a cash buyer or a traditional sale with no financing contingency, you can leverage that. Just make sure the calculator you're using reflects the rate you've agreed to, not the default rate the tool assumes. Finally, remember that proceeds aren't the same as profit. If you bought the home five years ago and refinanced twice, your basis includes the purchase price, closing costs from that purchase, and any capitalized improvements. Subtract that from your net sale price and you get your taxable gain. That calculation requires records, not formulas. Keep receipts for roof replacements, kitchen remodels, and structural work. Those additions increase your basis and reduce your tax liability.