How House Payments Actually Work in Missouri
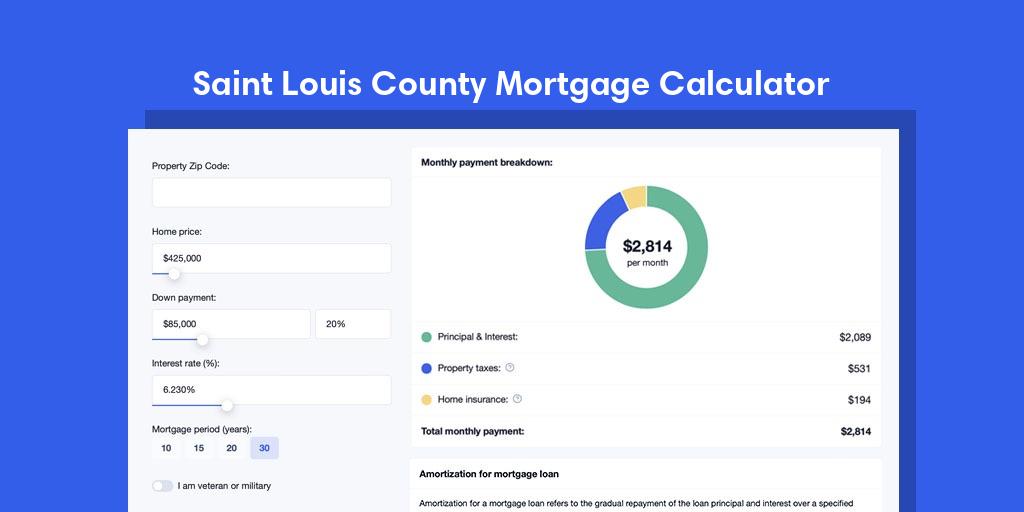
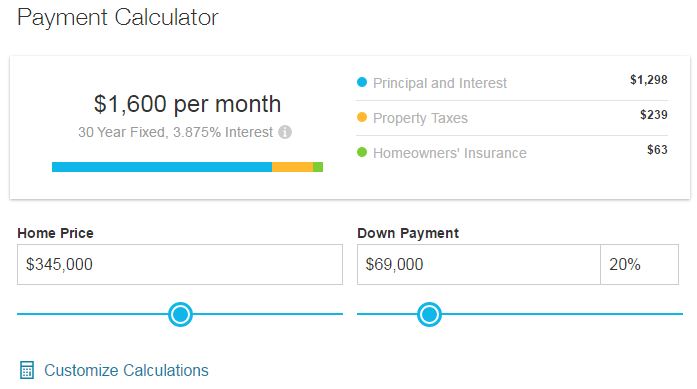
The monthly payment on a Missouri home isn't just principal and interest. If you're looking at a $250,000 house in St. Louis with a 20% down payment and a 6.5% rate, your P&I comes out to roughly $1,269. But the actual check you write to the escrow account will be closer to $1,580 once you add property taxes, homeowners insurance, and possibly PMI. That gap matters. Most first-time buyers in this state calculate one number and then get surprised when closing costs and escrow push the real monthly outflow much higher. A House Payment Calculator Missouri tool that only inputs price, rate, and term is going to give you a number that looks clean on paper and means nothing in practice. The calculators that actually work need to pull in county tax rates, which vary wildly across the state. St. Charles County sits around 0.87% of assessed value annually. Jackson County, where Kansas City sits, runs closer to 1.1%. Platte County pushes past 1.4%. If your calculator doesn't let you input a specific county or zip code, it's not going to be useful for more than a rough ballpark.
Running a House Payment Calculator Missouri Step by Step
Start by gathering three pieces of information before you open any tool. Your target purchase price, your available down payment percentage, and the county where the property sits. Then find the current mortgage rate for the loan type you're considering—conventional, FHA, VA. Each program carries different requirements and rate points that affect the monthly number significantly. Input the purchase price and down payment. The calculator will show you the loan amount. Enter the interest rate and loan term, typically 30 years for most residential purchases in Missouri. Now comes the part most free calculators skip. You need to add the annual property tax. Take the home value, multiply by the county's millage rate, and divide by 100. Divide that annual figure by 12 to get the monthly tax portion. Add monthly homeowners insurance, which in Missouri averages between $80 and $150 depending on coverage and location. If your down payment is under 20%, throw in PMI, which runs roughly 0.5% to 1% of the loan amount annually on conventional loans. I worked with a client last year who was looking at a home in Greene County near Springfield. The online calculator he found showed a monthly payment of $1,420. It turned out the property had a specialized tax district overlay that added roughly $45 a month to the tax line. The calculator had no way to account for that. We manually added it after running the base numbers, and the real payment came to $1,612. That $192 difference was enough to push him over his lender's debt-to-income limit on a few loan programs. He ended up looking at a different property in a lower-tax zone instead.
What Most People Miss About Missouri Property Taxes
Missouri assesses property at a fraction of market value. Residential property is assessed at 19% of fair market value. So a $300,000 home has an assessed value of $57,000. The tax rate you see quoted for a county applies to that assessed value, not the full purchase price. Some calculators online apply the rate to the full price, which inflates the tax estimate by roughly five times. Always verify whether the tool uses assessed value or market value as its base. Another thing that catches people off guard. Missouri has homestead exemption provisions that can reduce your taxable assessed value, but only after you've established primary residency and filed the proper paperwork. A brand-new buyer won't get that reduction in the first year. Plan your initial payments without it. The exemption can shave anywhere from $5,000 to $25,000 off the assessed value depending on age and disability status, which translates to maybe $40 to $100 a month in property tax savings once it's in place.
Get the Full Details
Limitations of Online Calculators
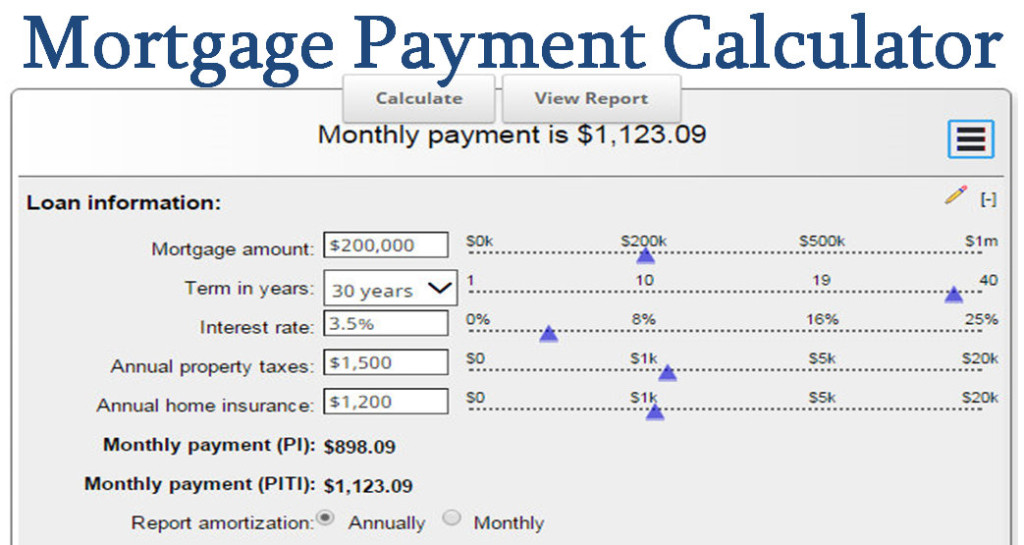
Free calculators on mortgage lender websites are useful for quick estimates but they operate on generalizations. They typically pull average tax rates for a state rather than specific county data. They rarely account for special assessments, HOA fees, or flood insurance requirements, which are common in parts of Missouri along the Missouri River and Mississippi River floodplains. If the property sits in a designated flood zone, you'll need NFIP or private flood insurance, adding another $100 to $300 monthly depending on elevation and distance to water. When the numbers get close to your budget ceiling, stop relying on a browser calculator. Run the figures through your lender's own underwriting worksheet or ask for a Loan Estimate. That document will show the exact taxes, insurance premiums, and any lender-required items based on the actual address and your credit profile. A Loan Estimate takes about 15 minutes to generate once you've submitted a formal application, and it's binding on the lender for ten days. That's as close to an accurate monthly payment number as you're going to get before closing. If you're comparing multiple properties across different counties, build a simple spreadsheet. Columns for purchase price, down payment, loan amount, interest rate, monthly P&I, county tax rate, annual insurance, PMI if applicable, and any HOA or flood insurance. The total row at the bottom will show you the real monthly obligation for each option. That takes about twenty minutes to set up and saves you from making offers based on numbers that don't reflect reality.