The Math Nobody Warns You About
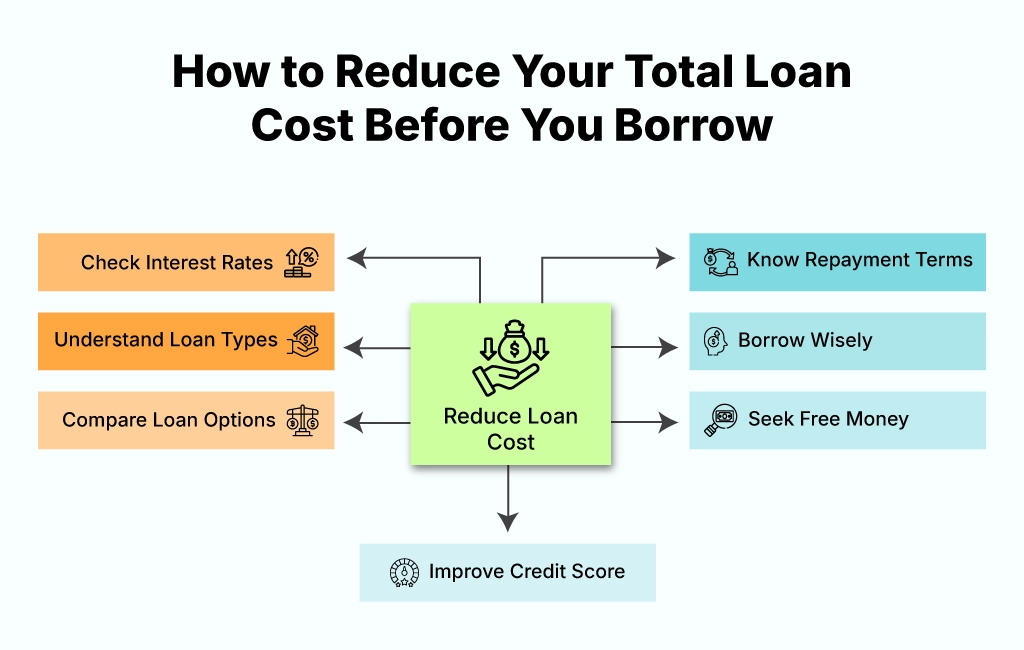
Most people look at their monthly payment and assume that's the only number that matters. It isn't. The total cost of a loan is the sum of every dollar you'll ever hand to the lender, principal included. That number can be 30 to 50 percent higher than the amount you actually borrowed, depending on rate and term. I learned this the hard way back in 2018 when I refinanced a home equity line. The monthly payment dropped by $200, which felt like a win. I didn't catch that extending the term by seven years would add roughly $18,000 in interest over the life of the loan. That extra cost sat there invisible until I ran the numbers on a spreadsheet at 2 AM. There are only a handful of actual levers you can pull, and most of them are boring. The big ones are the interest rate, the loan term, and the timing of your payments. Everything else is secondary. Let me walk through what actually moves the needle. This is the single highest-impact decision you will make. A quarter-point difference in rate can change your total interest paid by thousands over a standard 30-year mortgage or even a 5-year auto loan. I've seen borrowers accept the first rate the lender offers without shopping around. Don't do that. Get quotes from at least three sources within a concentrated window — ideally within 14 days, because credit bureaus treat multiple inquiries of the same type within that period as a single hit. That protects your score while you compare.
Here's a detail most calculators skip: points. Paying discount points upfront lowers your rate, but you have to stay in the loan long enough to break even. On a $300,000 mortgage, one point costs $3,000 and might drop your rate by 0.125 percent. That saves you roughly $53 a month. You'd need about 57 months just to recover the cost. If you plan to move or refinance before that, points are a waste. I once advised a client who sold her house 18 months after closing with points baked in. She lost the entire investment with no recovery. Simple as that.
Shorten the Term Without Breaking Your Budget
A shorter term means fewer payments, which means less interest compounds against you. Going from 30 years to 15 years on a mortgage typically cuts your total interest by more than half. The monthly payment jumps, obviously. But here's the counterintuitive part: if you keep your 30-year payment amount and throw the difference at principal, you effectively create a 15-year payoff without the lender requiring it. I've done this manually on several loans for myself and clients. You just set up an extra principal-only payment equal to what your payment would be on the shorter term, minus your actual required payment. The lender applies it directly to principal, not to future interest. The pitfall here is prepayment penalties. Some auto loans and a smaller number of mortgages carry them, especially in the first two to three years. Read the disclosure schedule before you commit. I found one in 2021 on a used car loan that charged a 2 percent fee on any principal payment over $5,000 in the first 36 months. The borrower had planned to pay down the car quickly to avoid depreciation eating his equity. The penalty ate most of the savings. We restructured the payoff plan to stay under that threshold and still saved money, but it required reworking the schedule every quarter.
Get the Full Details

Make Payments More Frequently Than Monthly
Most loans calculate interest daily or monthly based on your outstanding balance. If you switch from monthly payments to biweekly payments, you end up making 26 half-payments per year, which equals 13 full payments instead of 12. That one extra payment per year shaves years off the term and thousands off total interest. It's not a trick. It's arithmetic. On a $250,000 loan at 6.5 percent over 30 years, switching to biweekly saves roughly $38,000 in interest and cuts the payoff down to about 23 years. The catch is that not all lenders support automatic biweekly processing. Some will accept the payments but process them as regular monthly installments, which destroys the benefit. I had a client in 2022 who set up biweekly payments through his lender's portal and never noticed that his account was still billing monthly. He caught it six months later when he reviewed his amortization schedule and saw zero difference. He switched to manual biweekly payments directly to the principal balance and recovered the lost ground over the next few years. Always verify how the lender is actually applying your payment frequency.
Target Principal First, Always
Whenever you have extra money, direct it at principal. Not at fees. Not at escrow. Principal. This reduces the balance that accrues interest going forward, which is the whole mechanism that saves you money. The order of operations matters too. Pay minimums on all loans first, then attack the highest-interest debt with whatever's left. This is the avalanche method and it's mathematically optimal for minimizing total cost. The snowball method — paying off the smallest balance first — has psychological benefits but costs you more in interest over time. I worked with a borrower who had three student loans: one at 4.2 percent, one at 5.8 percent, and one at 7.1 percent. She was emotionally attached to the smallest one because it had the lowest balance. We talked her out of it. The 7.1 percent loan was costing her $43 more per month in interest than the 4.2 percent one despite having a similar balance. She switched to the avalanche approach and saved about $6,200 over the life of the portfolio. She admitted later that it felt counterintuitive but the numbers didn't lie.
Watch for Ancillary Fees That Inflate Cost
Origination fees, underwriting fees, application fees, service charges, late payment fees — these stack up. An origination fee of 1 percent on a $400,000 loan is $4,000 that goes nowhere except the lender's pocket. It increases your effective interest rate even if the quoted rate looks competitive. I've seen borrowers fixated on the rate miss a 0.75 percent origination charge that bumped their actual cost to borrow by nearly 0.1 percent. That matters over a long term. Some fees are negotiable. Underwriting and processing fees, in particular, often have wiggle room. I once got a lender to remove a $350 processing fee and reduce the origination from 1 percent to 0.5 percent simply by asking and pointing out a competing offer. The loan officer needed the business. It happens more often than people think. Late fees are another trap. Missing a single payment by a few days can trigger a $25 to $50 charge, and in some cases a rate increase on variable loans. Set up autopay for at least the minimum amount to avoid that.

Consider Refinancing Only When the Math Works
Refinancing can reduce your total cost if you're getting a materially lower rate and you'll stay in the loan long enough to offset the closing costs. The breakeven calculation is straightforward: divide your total closing costs by your monthly savings. That gives you the number of months until refinancing becomes net positive. If the breakeven is 30 months and you plan to sell in 18, don't refinance. I've seen people refinance without doing this calculation, which is how they end up paying more in fees than they save in interest. There's also the issue of resetting the clock. Refinancing a remaining 20-year balance into a new 30-year term might lower your payment, but you're extending the interest accumulation period significantly. On a $200,000 balance at 5 percent, refinancing to a 30-year at 4.5 percent drops your payment by about $250 a month. But you'll pay roughly $27,000 more in total interest because you're spreading it over 10 extra years. If you want the lower payment without the extra cost, take the new loan at 20 years instead. The payment will be higher than the refinanced 30-year option but still lower than your original loan, and you'll save thousands compared to the longer term.
Use a Proper Amortization Schedule
Stop estimating. Pull the actual amortization schedule from your lender or build one in a spreadsheet. It shows you exactly how much of each payment goes to principal versus interest at every point in the loan's life. Early payments are almost entirely interest. That's why extra principal payments in the first few years have disproportionate impact. I built a comparison model for a client in 2023 showing that an extra $200 per month in principal during years one through five of his 30-year mortgage would save him $22,400 in interest and cut seven years off the payoff. The same $200 per month starting in year 20 would only save him about $4,100. Timing matters enormously. Most online calculators won't show you this nuance. They give you a total interest figure but not the time-weighted distribution. If you want to make informed decisions about when to throw extra money at the loan, the schedule is essential. It takes about ten minutes to set up and it pays for itself immediately in better decisions.