What a Family Trust Actually Is
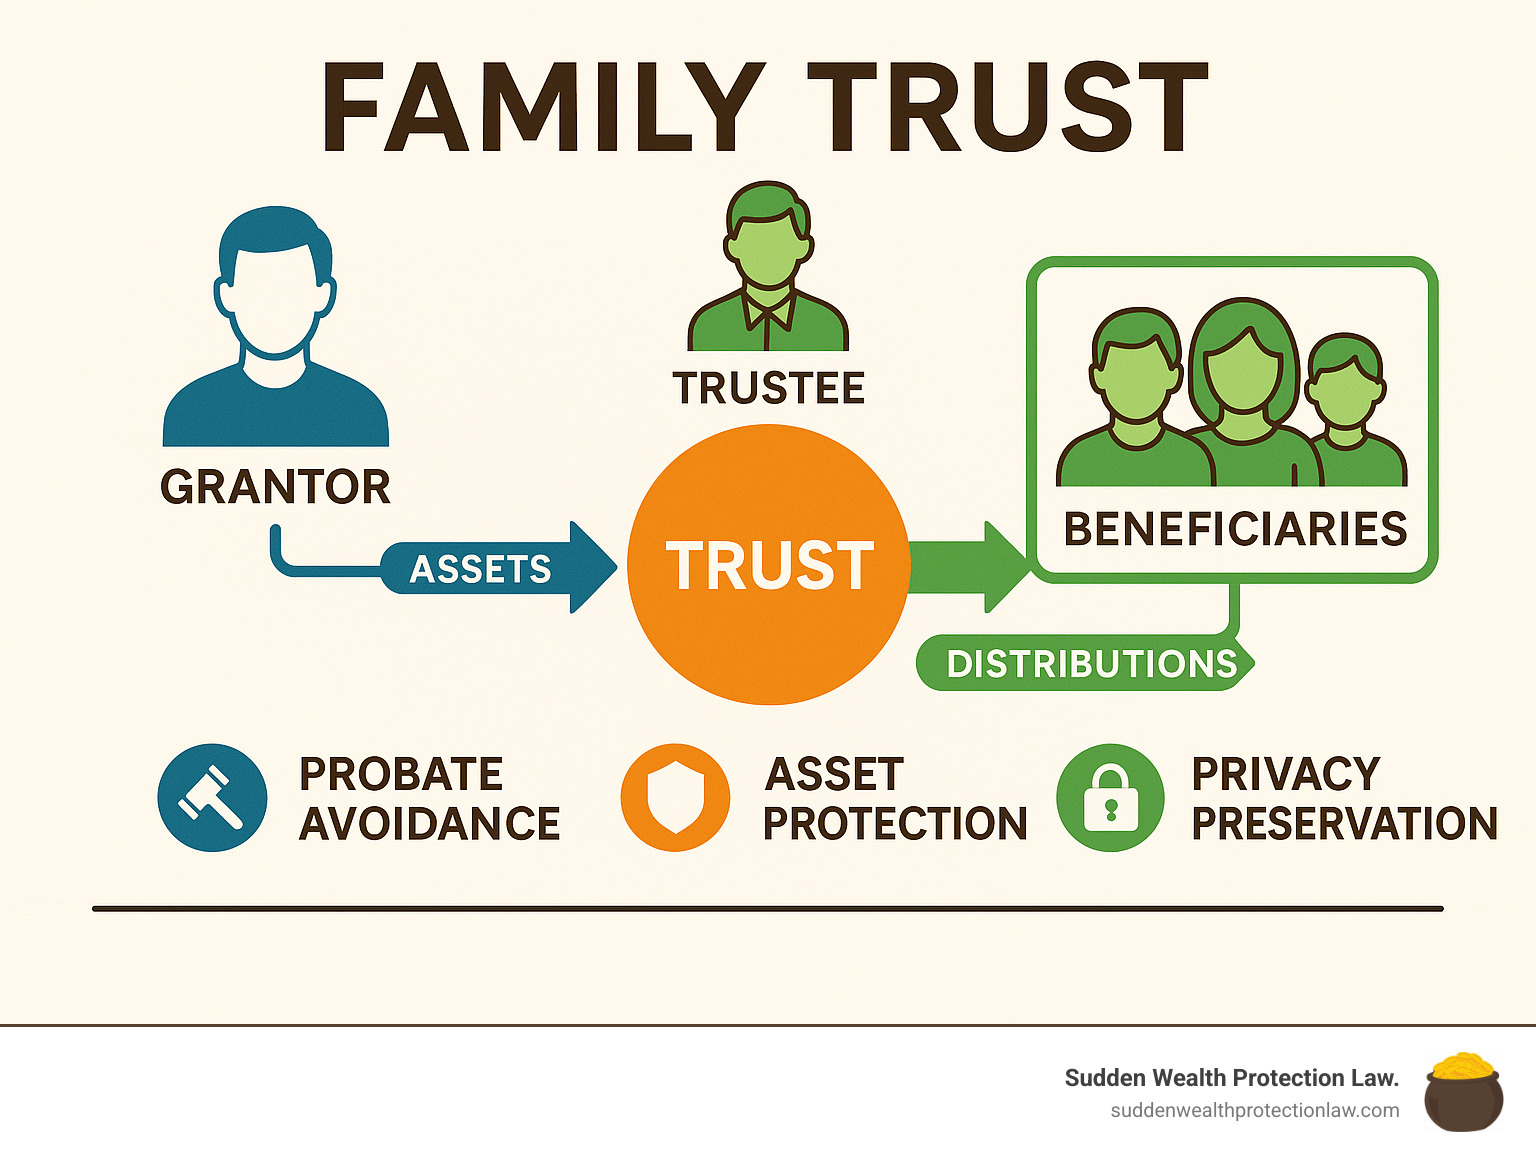
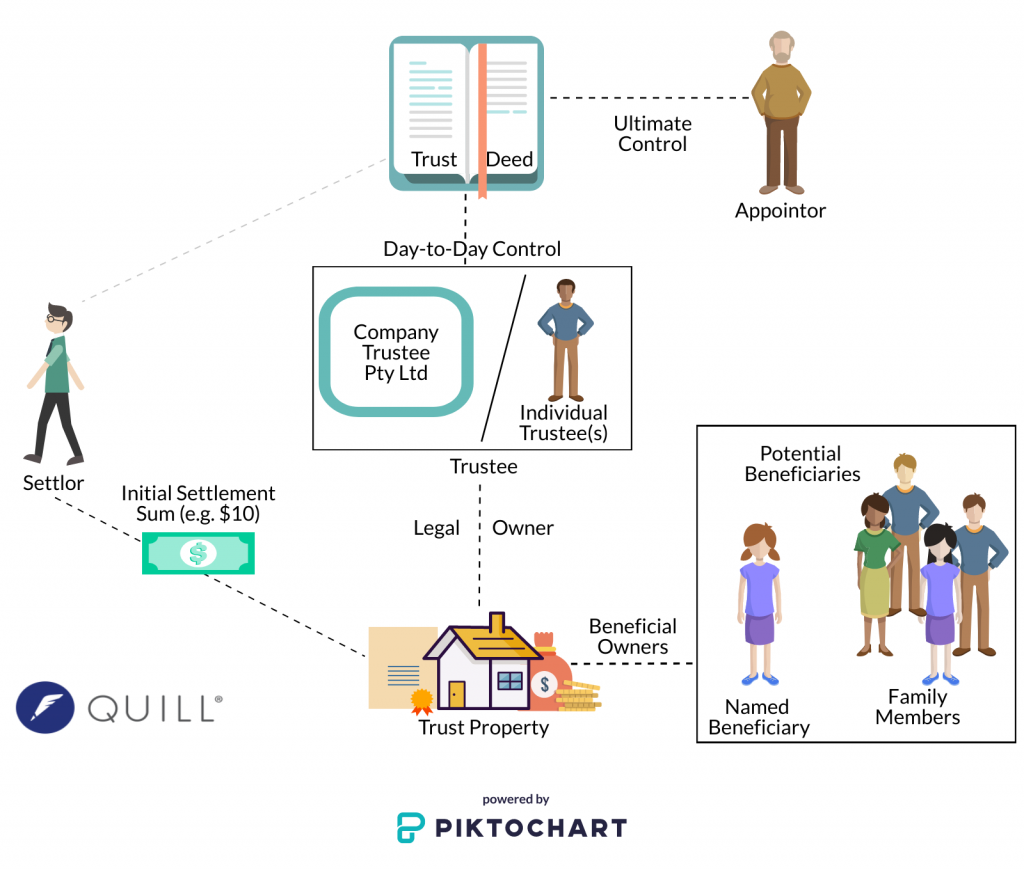
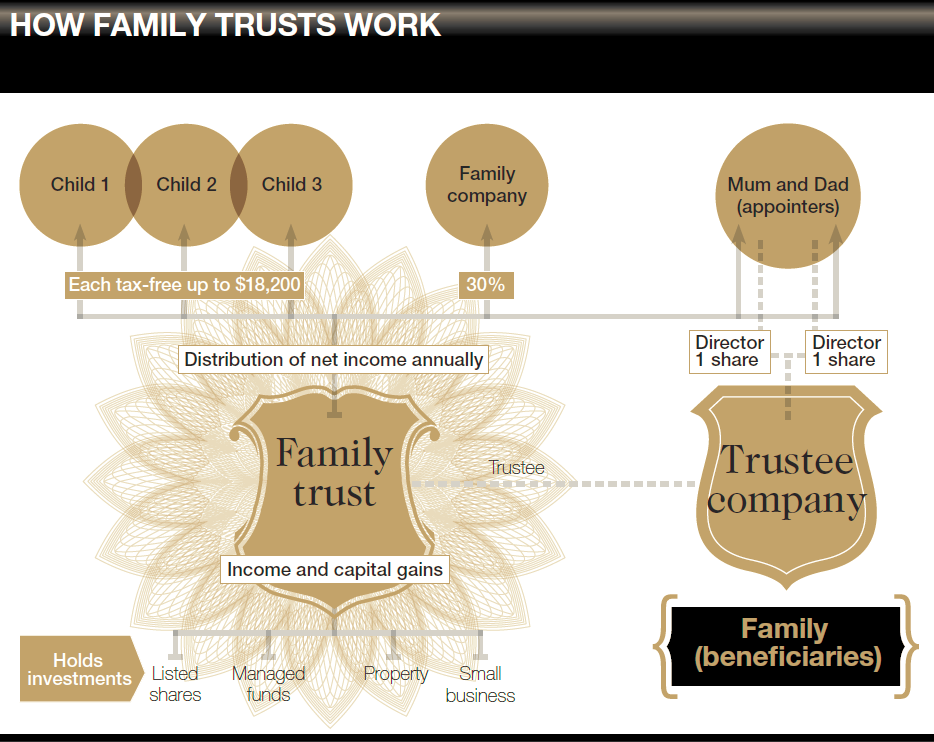
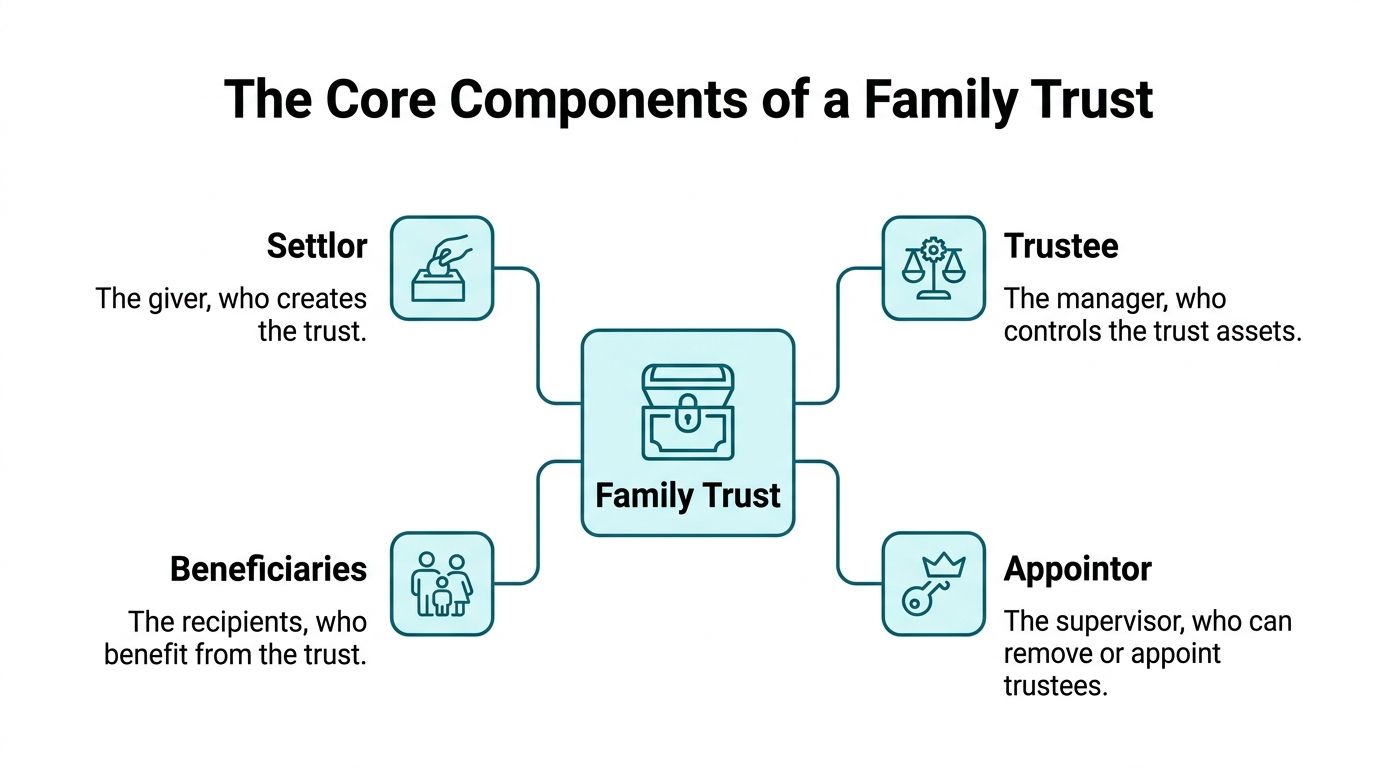
A family trust is a legal arrangement where a third party, called a trustee, holds and manages assets for the benefit of designated beneficiaries. The person who creates the trust and funds it is the grantor or settlor. You transfer ownership of your assets from yourself into the trust, and the trustee follows the terms you write to manage those assets. It sounds like a lot of paperwork for a simple idea, but the mechanics matter more than people expect. The process starts with drafting the trust document. Your attorney will lay out who gets what, when they get it, and under what conditions. Then you retitle your assets into the trust name. That means changing the deed on your house, updating beneficiary designations on retirement accounts where possible, and transferring ownership of investment accounts. Until you actually retitle assets into the trust, the trust document itself is basically a piece of paper with good intentions. I have seen this happen constantly. People pay a lawyer twenty thousand dollars to draft a trust, forget to retitle their brokerage account, and then wonder why their estate still goes through probate. Here is the part that trips most people up: a revocable living trust gives you almost no tax advantages during your lifetime. You still file your own 1040 using your Social Security number. The trust is a disregarded entity for tax purposes while you are alive and the trustee. The real benefits come later, after death. Avoiding probate is the main one, but so is controlling how and when your heirs receive assets. If you leave a million dollars directly to a twenty-two-year-old in a will, they get a check and the court has no further say in it. If you put that money in a trust with staggered distributions at twenty-five, thirty, and forty, you are deciding the terms long after you are gone.
I worked through a case a few years back where the grantor had funded the trust with real estate but forgot to retitle a rental property in Oregon. The title company had messed up the deed transfer two years earlier and nobody caught it. When the estate went to probate, that Oregon property was caught in limbo because the local court refused to accept the out-of-state trust as proof of ownership. The workaround was filing a quiet title action in the Oregon circuit court, which added six months and about eight thousand dollars in legal fees on top of everything else. The lesson was straightforward and brutal: after every asset transfer, verify the recording. Do not assume the deed went through because the closing package looked complete.
The Mechanics Inside the Document
Trust documents are longer than most people realize because the drafter has to anticipate failure modes. What happens if a beneficiary inherits when they are already in bankruptcy? What if they get divorced? What if they die before receiving their full share? The answer to all of these questions lives in spendthrift clauses, drug and alcohol provisions, and successive beneficiary designations. A well-drafted trust includes a spendthrift provision that prevents a creditor from reaching the trust assets while they remain undistributed. Once the trustee makes a distribution to the beneficiary, those dollars become fair game. That distinction matters more than most families understand. There is also the issue of successor trustees. Naming your spouse as co-trustee and your adult child as successor sounds logical on paper. But consider what happens if both incapacitate simultaneously or if your child is the primary beneficiary and also the sole trustee. That is a conflict of interest that can undermine the whole structure. I recommend naming a professional fiduciary or a corporate trustee as co-successor, even if your family member handles the day-to-day decisions. It costs more but it prevents the beneficiary from having unilateral control over their own inheritance while also being the person who decides whether they actually get the money. Governance structures inside trusts are another area where people cut corners. Some trusts include a trust protector, which is a person with the authority to modify or terminate the trust without going to court. This is useful when laws change or circumstances shift dramatically. A friend of mine had a trust protector clause that allowed the protector to relocate the trust to a different state if the original jurisdiction raised its fees or changed favorable statutes. That clause saved the family roughly forty thousand dollars in annual trust administration costs when Delaware revised its trust law unfavorably for certain structures.
Get the Full Details

When a Family Trust Does Not Help
The biggest misconception is that a trust protects you from creditors while you are alive. It does not. A revocable trust offers zero asset protection because you control the assets and can revoke the trust at any time. Courts view those assets as yours anyway. If you need actual creditor protection, you need an irrevocable trust with genuine third-party control and no retained powers that would make the assets yours in the eyes of the court. And even then, states like Nevada and Delaware offer the strongest protections, while other states actively weaken irrevocable trust shields. Estate tax exemption is another area where expectations are wildly inflated. The federal estate tax exemption sits at $15 million per individual as of my last update, which means the vast majority of Americans will never face it. Some people pay thousands to set up credit shelter trusts or QTIP trusts for tax reasons, and they are solving a problem they do not have. I have watched couples spend fifteen thousand dollars on sophisticated tax-minimization trust structures when their combined estate was four million dollars and would have owed zero federal estate tax even if everything went to the worst case scenario. The money was better spent on making sure their actual assets were properly titled into the basic revocable trust they already had. Retirement accounts do not play nicely with trusts either. Naming a trust as the beneficiary of an IRA or 401(k) triggers required minimum distributions based on the oldest beneficiary's life expectancy, and if the trust is not drafted with the right language, it could force a complete distribution within ten years or even five, depending on when the account owner died. The SECURE Act changed this landscape significantly. I have seen beneficiaries lose hundreds of thousands of dollars in tax-deferred growth because the trust was not drafted with IRC Section 401(a)(9) look-through provisions that let the IRS look through the trust to the actual human beneficiaries for distribution purposes.
What You Actually Need to Get Started
You need an estate planning attorney, not a software package, unless your situation is genuinely simple. A pour-over will alongside your trust catches any assets you missed or acquired after the trust was created. The pour-over will directs those stray assets into the trust at death, but they still go through probate first. That is why funding the trust during your lifetime matters more than the will itself. Keep a trust funding schedule. It is a simple spreadsheet listing every asset, its current title, and the date it was transferred into the trust. Update it whenever you buy or sell something significant. I use a shared cloud folder with my clients where they upload copies of recorded deeds, new account statements showing the trust as owner, and confirmation emails from title companies. It takes about ten minutes a month and prevents the kind of gaps that cause problems later. Annual review meetings with your attorney and accountant catch drift. Life changes, laws change, and trust provisions that made sense five years ago may not make sense today. A twenty-minute call to update beneficiary designations or add a new child as a beneficiary can prevent a disaster that would otherwise require court intervention. Most attorneys offer annual check-ins for a flat fee, and it is worth every dollar compared to the cost of fixing a broken trust after everyone is gone.
A family trust is a tool, not a solution. It solves specific problems around probate, control, and distribution timing. It does not solve tax problems for most people, it does not protect living assets from creditors in a revocable structure, and it does not function correctly unless you fund it properly. The gap between drafting a trust and having a working trust is the funding step, and that is where the majority of failures occur.