The Math Behind Making It
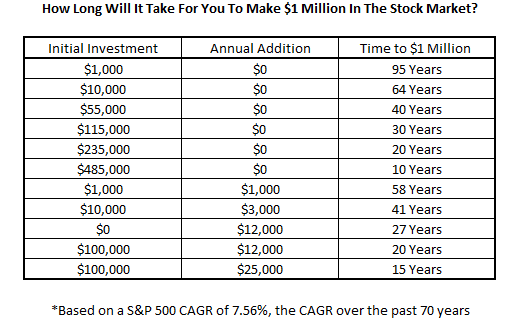
Saving a million dollars sounds like a distant goal until you look at the numbers. The timeline depends almost entirely on how much you invest each month and what kind of returns you can sustain over time. Most people underestimate the power of compounding because they think in short bursts rather than decade-long stretches. I ran these calculations for years when I was advising clients on retirement planning, and the results are about what you would expect: time is the single biggest variable, and the difference between ten years and twenty years is massive. At an 8% annual return, which is a reasonable historical average for a balanced stock-heavy portfolio, investing $1,000 per month gets you to a million dollars in roughly 30 years. Double that to $2,000 a month and you cut it down to about 23 years. Invest $5,000 monthly and you are looking at 17 years. These numbers assume consistent contributions and no withdrawals, which is important to keep in mind. The reality for most people involves job changes, market downturns, and the occasional emergency drain that throws the schedule off. Here is a practical example from my own experience. A client came to me about eight years ago wanting to reach a million by age 55. He was 42, making about $95,000 a year, and he had roughly $80,000 already invested. We mapped out a contribution plan of $2,500 per month, split between a 401(k) and a taxable brokerage account. At an assumed 7.5% return, the projections showed him hitting the target around age 58 instead of 55. The gap wasn't huge, but it forced a conversation about either lowering his timeline expectation or increasing his monthly contribution to $3,200, which was stretching his cash flow. We went with the higher number and adjusted his budget, cutting discretionary spending he didn't even realize he had that much of.
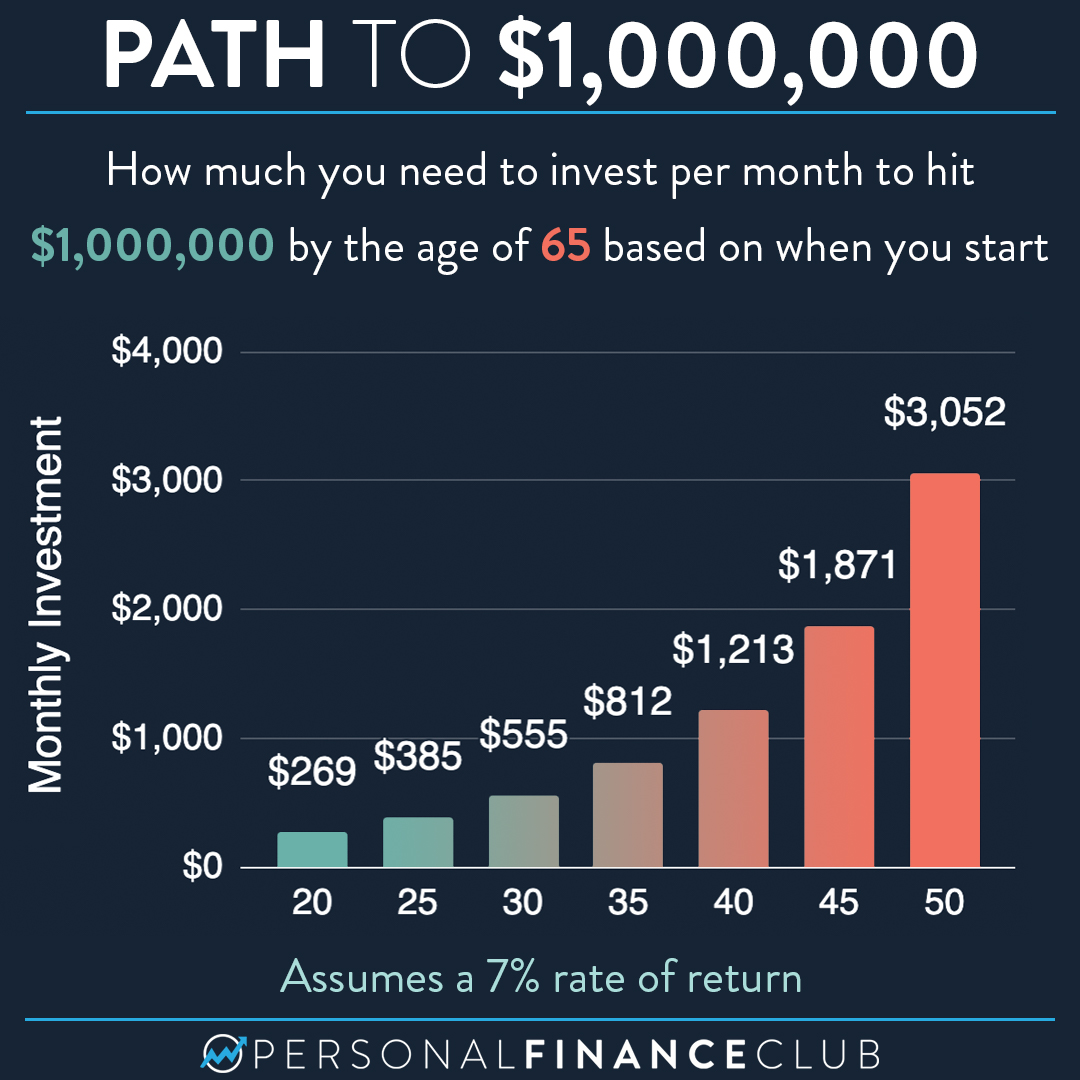
The key insight that most beginners miss is that early contributions matter disproportionately more than later ones. A dollar invested at 25 is worth roughly three times a dollar invested at 40, assuming the same rate of return. This isn't hype, it's just arithmetic. If you are under 30 and haven't started, you aren't doomed, but you will need to contribute more aggressively than someone who began earlier. Starting later doesn't make the goal impossible, it just compresses your options and leaves less room for error. Another counter-intuitive point is that higher returns don't always mean faster timelines. Chasing 15% annual returns sounds attractive until a market correction wipes out two or three years of gains. A steady 8% portfolio with discipline consistently beats a volatile strategy that promises more but delivers less over a full cycle. I watched several clients burn through aggressive investments because they couldn't handle the drawdowns. The ones who stuck with index funds and rebalanced annually were the ones who actually crossed the finish line. There are also scenarios where the math simply doesn't work within a reasonable timeframe. If you are carrying high-interest debt above 8%, investing aggressively while paying 20% on credit cards is a losing strategy. Clear the debt first, then redirect those payments into investments. I had a client in her late thirties who was putting money into a Roth IRA while carrying $18,000 in credit card debt at 22% interest. We paused the IRA contributions entirely, paid off the balance in nine months using a consolidation strategy, and then doubled her investment rate. She reached a million about four years sooner than she would have otherwise.
The timeline also shifts dramatically if you have an income that grows. Someone starting at $60,000 a year and raising their savings rate by 5% annually will outpace someone who saves the same dollar amount for three decades. Salary growth is an underutilized tool in wealth building because people tend to spend it rather than save the difference. A modest 3% raise that goes into investments rather than lifestyle creep adds up to a meaningful edge over time. Market timing won't save you, and neither will trying to pick individual stocks. The data across decades of research consistently shows that buy-and-hold index investing outperforms the majority of professional fund managers and far more retail traders. You don't need to understand complex financial models to reach a million. You need a simple plan, automatic contributions, and the patience to let it run. The hardest part isn't the math, it's staying consistent when the market drops 30% and everyone around you is panicking on social media. If you want a concrete starting point, pick a monthly contribution that feels tight but manageable, set up automatic transfers on payday, and check the account once a year to rebalance. Anything more frequent than that usually leads to emotional decisions that hurt your returns. The clock starts ticking the moment you make that first contribution.
Get the Full Details