What Determines Your Borrowing Capacity
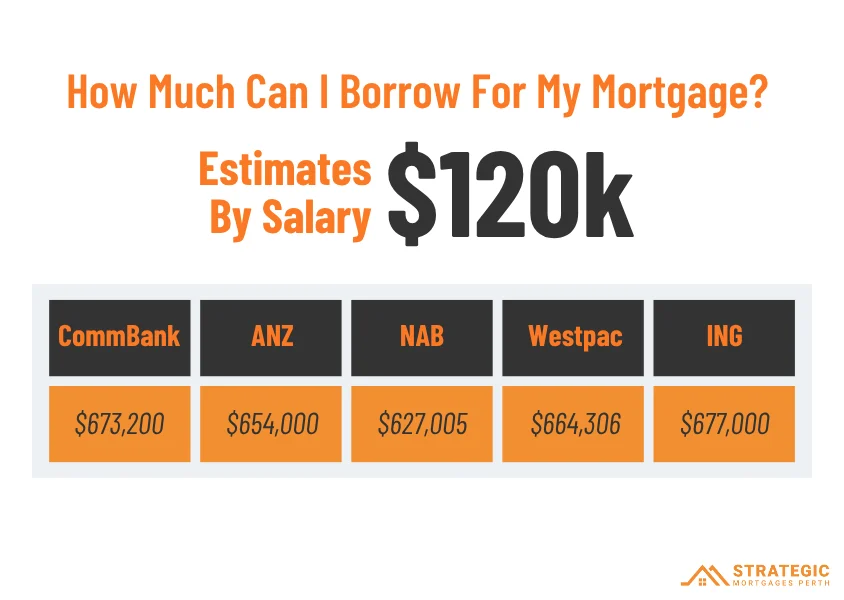
Lenders don't just hand out money because you have a decent income. The actual number they'll lend you comes down to a few mechanics that most people misunderstand, and getting these wrong can cost you weeks of wasted time and a bunch of credit checks. There are two main lenses a lender uses. First is your servicing calculation — they apply an interest rate buffer to your income and expenses to see if you can afford repayments if rates jump. Second is their internal policy limits on debt-to-income ratios. These vary between lenders. Some are aggressive, some conservative. The range between the two ends can easily be $50,000 to $150,000 on a typical first-home buyer's profile. Most people think borrowing capacity is about how much house they want. It's actually about how much house they can service without triggering a repayment stress test. The buffer rate is the real invisible ceiling. Currently most lenders use a service rate of around 7.5% to 8% on top of the actual product rate when calculating affordability. So if the going rate is 6%, they're assessing you at roughly 13.5%. That sounds steep. It is. And it's by design.
How Much Can I Borrow For A House
Here's how the actual calculation works in practice. You take your gross annual income. Subtract your annual living expenses, which lenders pull from your bank statements rather than what you claim. Divide the remainder by the monthly repayment per $100,000 borrowed at their service rate. Multiply by however many hundreds of thousands fit. That's your rough number. Then the lender runs their own internal assessment on top of it, and that's where people lose another 10 to 20 percent. Let me give you a concrete example. Say you earn $95,000 a year, have $38,000 in annual expenses after reviewing your actual spend, and you're looking at a $600,000 loan. At a 13.5% service rate, the monthly repayment per $100,000 is roughly $1,380. Your surplus is $1,633 per month. That gives you about $470,000 on paper. But the lender's internal policy might cap your debt-to-income ratio at 5.5x, which would push the ceiling to $522,500. The lower number wins. Always. I've seen this trip people up constantly. A client of mine came to me pre-approved for $720,000 from a big bank. They were excited. Their broker then ran a second assessment with a different lender and the number dropped to $635,000. Same income. Same job. Same apartment. The difference was how each lender calculated disposable income and what they counted as a "liability." The first bank hadn't counted a $4,200 annual gym membership or the personal loan he'd been paying down for two years. Minor debts get ignored by some lenders and heavily weighted by others. This is why two pre-assessments for the exact same situation can produce wildly different numbers.
The fix is straightforward but most people skip it. Get a second assessment from a different lender before you make any offers. Preferably from a broker who shops around, not someone tied to one institution. The extra hour you spend on this saves you from building false confidence in a number that might not hold.
Get the Full Details

Common Pitfalls That Shrink Your Number Without You Noticing
Credit cards and overdrafts. Lenders typically calculate a monthly liability of 3% to 5% of your total revolving credit limit. Even if you carry zero balance, that $15,000 in available credit gets treated as a $450 to $750 monthly obligation. Pay off those cards, close unused accounts, and your borrowing capacity can jump by $20,000 to $50,000 overnight. Most people don't realize this applies. Guarantees on other people's loans. If you've cosigned a car loan for your brother, that payment shows up in your assessment. It doesn't matter that you aren't the primary borrower. The liability attaches to you. I had a case where a client had a $28,000 guarantee on a relative's vehicle loan that nobody had mentioned. The lender counted it as a $650 monthly obligation. Removing the guarantee — which required the relative to refinance — bumped her capacity by approximately $38,000. This is obscure enough that even experienced borrowers overlook it. Your deposit size interacts with something called Lenders Mortgage Insurance, or LMI. If you put down less than 20%, most lenders require LMI. This doesn't directly reduce your borrowing number, but it eats into your cash reserves and can push you into a tighter position once settlement hits. Some lenders will factor LMI premiums into their servicing calculations, which further compresses what they'll offer you.
Self-employed borrowers face an entirely different set of rules. You can't just present your tax return and expect a clean assessment. Lenders typically look at two years of tax filings, but they don't always trust the net profit figure. Many will add back certain deductions, depreciation, and owner allowances to arrive at an "adjusted" income number. This adjusted figure can be significantly higher or lower than your stated profit, and the variation between lenders is enormous. I've seen the same self-employed applicant get assessed at $82,000 income by one lender and $110,000 by another, purely based on how each one treated superannuation contributions and business expenses. The workaround for self-employed people is to prepare a detailed explanation letter for each application, showing exactly how you've calculated your income, what deductions you're claiming, and why your Adjusted Taxable Income is the most reliable figure. Attach your tax returns, Notice of Assessment, and bank statements for the last 12 months. It adds about 20 minutes to each application but can mean the difference between a $90,000 and a $130,000 assessment.
What Lenders Actually Look at Beyond Income
Your credit file matters, but not the way most people think. A single missed payment won't necessarily tank your borrowing capacity. Multiple missed payments, collections accounts, or active bankruptcies will. More importantly, hard credit enquiries stack up. Every loan application generates one. Six enquiries in three months looks like financial distress to most underwriters. Space your applications out. Wait at least 30 days between lenders unless you're doing a simultaneous assessment with a broker. Employment stability is another quiet factor. Being in your current job for less than six months raises flags. Changing industries within the last two years raises more. Contract workers and commission-based earners get assessed at a reduced income figure — typically 80% to 90% of their average earnings — because the income isn't guaranteed. Temporary visa holders face additional restrictions. Some lenders simply won't touch certain visa subclasses. Existing assets can work in your favor if you structure them correctly. Equity in an investment property or even a paid-off car can be used as security. But here's the counter-intuitive part: carrying debt against those assets actually reduces your borrowing capacity more than you'd expect. A $200,000 investment property with a $120,000 loan on it doesn't give you $80,000 in usable equity for borrowing purposes. The lender will apply a haircut to the valuation and then assess the remaining loan as a liability against your income. The net effect is often smaller than expected.
When the Standard Assessment Fails Completely
There are situations where the standard calculation just doesn't work. If you have significant unsecured debt, a low deposit, variable income, or a complex financial situation, mainstream lenders will often give you a conservative number or decline outright. This is where non-concessional lenders come in, and they exist for a reason. Non-concessional lenders operate with different criteria. They're more flexible on debt-to-income ratios, they consider your actual cash flow rather than just your tax return, and they're willing to work with commission-heavy incomes, recent job changes, and higher existing liabilities. The trade-off is the interest rate. Expect 0.5% to 1.2% above the concessional market rate. On a $600,000 loan over 30 years, that's an extra $150,000 to $200,000 in total interest. Significant, but sometimes the only way to enter the market at all. Another path is using a guarantor. A family member with equity in their home can stand as guarantor on part of your loan, effectively replacing the 20% deposit. This avoids LMI entirely and can boost your borrowing capacity because the lender views the secured portion as lower risk. The risk to the guarantor is real though — if you default, they lose equity. I've seen this work well, and I've also seen it destroy family relationships. Don't discuss this option lightly with anyone.
Property developers and investors sometimes use a strategy called cross-collateralization, where multiple properties secure a single loan facility. This can consolidate debt and improve cash flow, but it creates a dangerous concentration of risk. If one property underperforms, it drags the whole facility down. Restructuring becomes extremely difficult because the loans are tied together. Use this only if you have a specific, documented reason for it. It's not a general optimization strategy.
Practical Steps to Maximize Your Number
Get your bank statements ready. Not the summarized version from your app. The full PDF statements from the last 12 months, every transaction included. Lenders will scrutinize these for unexplained deposits, gambling transactions, and spending patterns. Having them organized before you apply saves three to five business days on processing. Pull your credit report. Check it yourself through one of the free bureaus. Look for accounts you don't recognize, incorrect balances, or enquiries you didn't authorize. Dispute anything that's wrong before you apply. A corrected credit file can improve your assessment by 5% to 10% in some cases. Pay down revolving credit. I mentioned this earlier, but it bears repeating because people forget. Clear credit card balances before you apply. Close accounts you don't use. Reduce your total available credit. The 3% to 5% calculation applies to your total limit, not just what you owe. Bringing a $20,000 limit down to zero and closing the account can free up $8,000 to $15,000 in borrowing capacity depending on your income level and the lender's assessment methodology.
Time your application strategically. If you're expecting a bonus, commission payout, or tax refund, wait until it's deposited and settled in your account before applying. Lenders typically want to see the funds sitting there for 30 to 60 days. A fresh deposit that disappears in a week gets flagged. Money that stays in the account gets counted as savings, which improves both your deposit position and your liquidity assessment. Use a mortgage broker who understands the difference between pre-approval and formal assessment. A pre-approval is a preliminary number based on information you provide. A formal assessment involves the lender verifying everything independently. The gap between these two stages is where deals fall apart. I've watched contracts collapse because the formal assessment came back $40,000 below the pre-approval figure. The borrower had assumed the pre-approval was binding. It isn't. Nothing is binding until unconditional approval is issued in writing.
The Reality Check
Borrowing capacity is not a fixed number. It's a range that shifts depending on which lender you approach, how your financial documents are presented, and what the current interest rate environment looks like. The gap between the most favorable and least favorable assessment for the same person can be large enough to change which suburb you can afford, which property type is realistic, and whether you need LMI at all. Don't fall in love with a pre-approval number. Treat it as a starting point, not a ceiling. Run the assessment through at least two lenders before you make an offer. If you have any unusual income, debt, or employment history, budget an extra two to three weeks for the process. Most standard applications settle in 10 to 14 business days. Complicated ones take longer, and the lenders that spot complexity early tend to be the ones that handle it better. And one final thing that nobody tells you: your borrowing capacity can shrink after you've been approved if interest rates rise significantly. Some lenders include a clause that allows them to reassess your capacity if their service rate benchmark increases. It's rare, but it happens. The 2022 to 2023 rate environment saw several lenders pull back on existing pre-approvals when their internal stress testing thresholds shifted. Factor that risk in. It changes how conservative you should be about stretching to the limit.