Construction Financing Isn't One Price
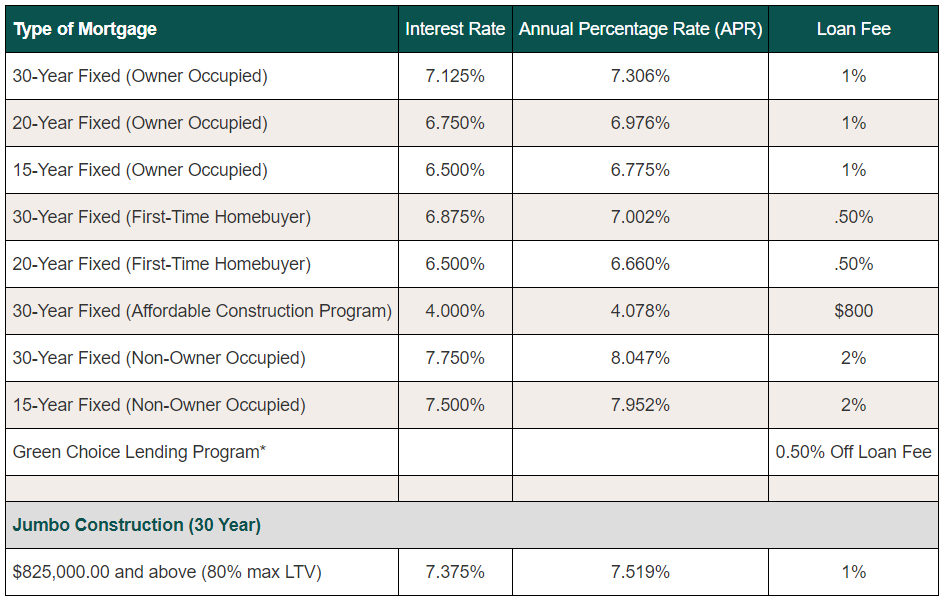
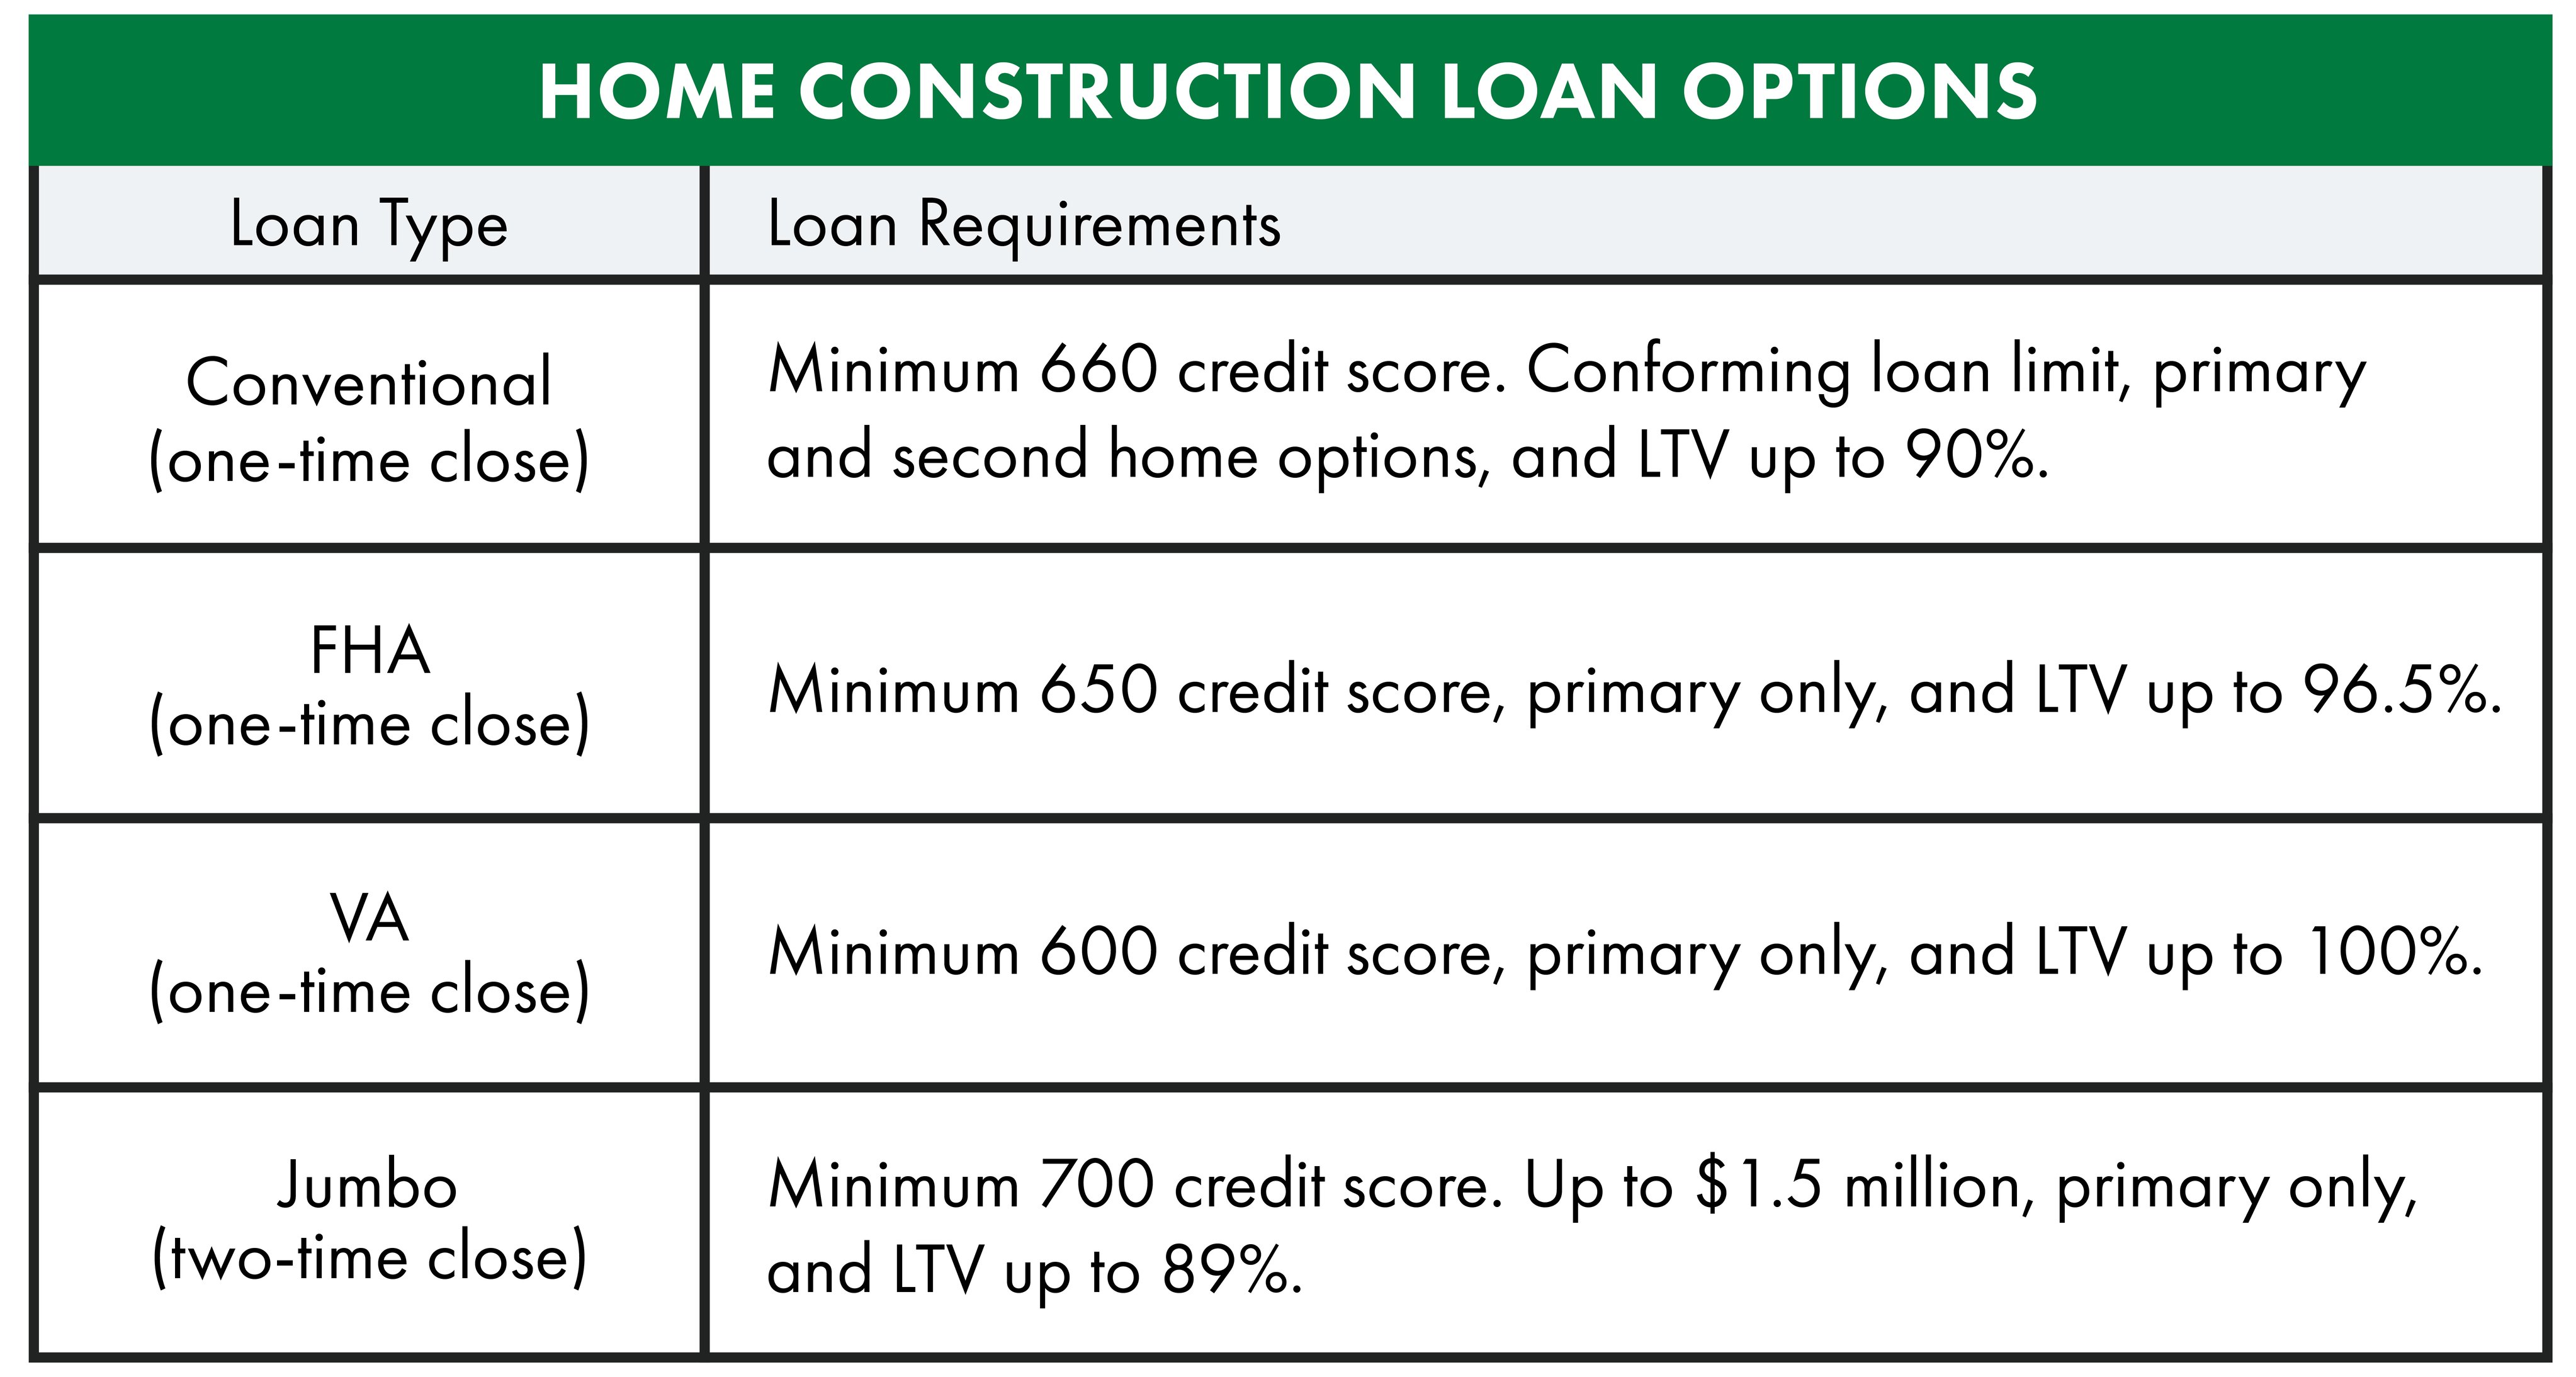
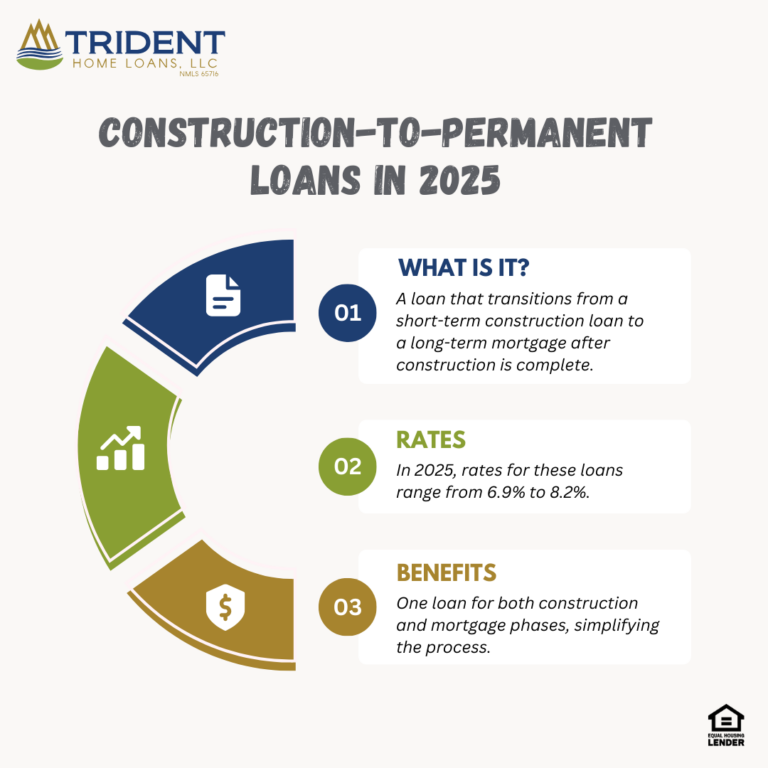
People ask me at least once a week what a construction loan costs, and the real answer is always a range with a bunch of moving parts. I just walked someone through a project last month where two loans for the same size build ended up $18,000 apart over the life of the loan because one had a higher draw inspection fee structure and the other locked rate early enough to avoid a market shift. The short version: expect a total cost that lands somewhere between 105 and 145 percent of what you would pay on a standard site-built home loan, and I will explain why it varies so much below. The most common question I get is about the interest rate itself, and that usually sits between 6.5 and 9.5 percent right now depending on your credit profile and where the money is coming from. But that is only one piece. The real cost includes origination fees, which typically run 1 to 3 percent of the total loan amount, appraisal fees around $750 to $1,250, and more importantly draw inspection fees that accumulate over the life of the build. Those inspections happen every time the builder asks for a portion of the money, and most projects see between four and eight draws, which means you are paying $150 to $300 per inspection, often stacked on top of engineering or third-party monitoring fees that can add another $2,500 to $6,000 for larger custom homes. What nobody tells you upfront is that construction loans are short-term by design, usually 12 to 18 months, and then they convert to a permanent mortgage. That conversion step is where people get hit with double closing costs if they do not structure it right. I had a client who refinanced from a construction-to-perm into a separate permanent loan and paid two sets of appraisal, title, and attorney fees because his lender did not offer a true one-closing construction-to-permanent product. That added about $6,200 to his total cost that could have been avoided entirely with a different loan structure from the start.
Where the Real Money Goes
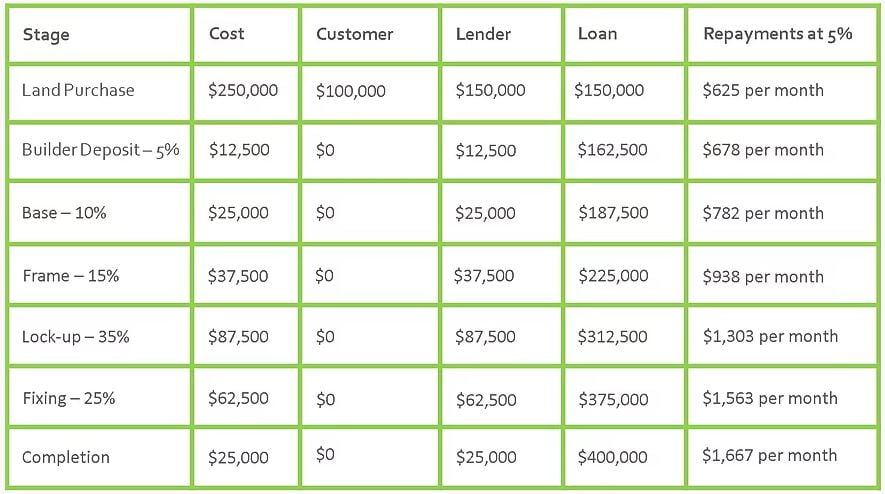
Interest during the construction phase is charged only on what has been drawn, not the full amount, and that changes the math significantly. If you borrow $400,000 for a 14-month build but only have about $220,000 outstanding on average during that period, you are paying interest on roughly $220,000, not $400,000. At 7.5 percent that works out to approximately $12,800 in interest during construction instead of the $30,000 you would pay if the full balance was drawn immediately. That is actually one advantage of this type of financing compared to pulling a home equity line or using hard money lenders who charge interest on the full amount from day one. Origination fees are where the big variance lives. Some lenders charge a flat 1 percent, others bundle it into points, and a few advertise zero origination while making it up through a higher interest rate or mandatory mortgage insurance. I learned this the hard way on a project in Tennessee where the broker quoted me 0.5 percent origination and 7.25 percent rate, but when I pulled the actual commitment letter the rate was 7.75 percent with a 1.5 point charge tucked into the lender credit section. That extra half point plus the inflated rate cost my client an additional $3,400 over the construction period alone before he even owned the house. Title and escrow work differently too. In many states construction loans require a separate title search and policy for the construction phase and then another for the permanent phase, even on a one-closing loan. That is not universal but it happens often enough that you should confirm with your lender whether dual title costs apply before you sign anything. Expect to pay $800 to $1,500 per title policy in most markets, and some lenders will waive the second one if you stay with them through conversion.
The Edge Cases That Make or Break the Budget
Soil and environmental testing is one area where people consistently underestimate cost. A standard Phase I environmental assessment runs about $1,200 to $2,500, but if the site has any history of agricultural use, nearby industrial activity, or uncertain drainage patterns you could be looking at a Phase II with soil borings that adds $4,000 to $12,000. I worked a project in Georgia where the county required percolation tests for a septic system that ran $3,800 because the standard test failed on clay soil and needed three backup tests at different depths. The builder had not included that in the budget and my client almost pulled the permit because the contingency was tapped out on framing changes. Rate lock timing is another silent budget killer. Most construction loans let you lock the construction rate for 60 to 90 days and then lock the permanent rate 45 days before projected completion, but delays are common. A 30-day weather delay pushed one of my clients past their permanent rate lock window and they were forced to pay a 0.25 percent extension fee, which on a $450,000 loan added about $1,125 to the total cost. If you are building in a market with long supply chains or labor shortages, budget an extra 0.15 to 0.25 percent for potential rate lock extensions. Appraisal risk during construction is something most people ignore until it is too late. Lenders order an after-improved value appraisal before funding the final draw, and if comparable sales in the area have softened even slightly your loan could fall short. I saw a case in Colorado where the final appraisal came in $22,000 below the contract price because a couple of nearby sales dropped in the six months since the initial purchase appraisal. The borrower had to bring $11,000 in cash to closing because construction loans do not allow the lender to reduce the permanent mortgage amount retroactively without renegotiating the whole deal.
Get the Full Details
Practical Ways to Keep the Total Cost Down
Start with pre-approval from a lender that offers true one-closing construction-to-permanent loans rather than two separate transactions. This eliminates duplicate closing costs, usually saves $4,000 to $8,000 in fees, and locks your permanent rate earlier in the process so you are less exposed to market movement during the build. Regional credit unions and community banks often have better terms for this product than national online lenders, though they may have slower draw processing times that can delay builder payments. Negotiate the origination fee before you commit. Many lenders have room to move on points, especially if you have strong credit and a low loan-to-value ratio. I always recommend asking for a Loan Estimate from at least three lenders and comparing the total closing cost column, not just the interest rate. Two loans with the same rate can have a $5,000 difference in total fees if one lender packages origination into points and the other charges it as a separate line item. Build a 10 to 15 percent contingency into your construction budget specifically for cost overruns that trigger additional draws and therefore additional interest. A $400,000 loan with a 12 percent contingency means you have $48,000 in reserve, and having that available prevents the awkward conversation where the builder stops work because the draw request was denied due to insufficient remaining balance. Interest on those contingency draws is still charged at your construction rate, so plan for an extra $2,000 to $4,000 in interest costs if you use more than half of your contingency.
Consider a construction-only loan followed by a separate permanent mortgage only if your credit profile or project details make the one-closing product unavailable. This route typically costs more overall because of the dual closing expenses, but it gives you the flexibility to shop for the best permanent rate after the build is complete and you have established the property value. Some builders actually prefer this model because it simplifies their payment schedule and reduces the risk of delayed draws from a lender managing both phases.
When Construction Financing Does Not Make Sense
There are situations where this product is the wrong tool and people stick with it anyway because it seems like the only option. If you are buying a spec home or a builder-grade subdivision model where the construction is already completed or nearly complete, a standard mortgage or renovation loan is almost always cheaper and faster. The additional inspection fees, longer underwriting timeline, and higher rates on construction loans rarely justify the complexity when you are not actually funding a build from the ground up. Similarly, if your project budget is under $150,000 for the construction phase, some lenders will decline to write the loan or charge a minimum origination fee that makes the effective rate prohibitively expensive. I had a client in Missouri who wanted to build a small ADU behind an existing home for about $120,000 and was quoted a 2.5 percent minimum origination fee, which on that loan size worked out to $3,000 or 2.5 points, making the effective annual cost closer to 11 percent including fees. A home equity line of credit or a personal loan from a credit union ended up costing less overall despite the higher stated rate on the HELOC. Market timing matters too. When construction material costs are rising faster than home values in your area, the after-improved appraisal risk becomes real and you could end up underwater on your permanent mortgage even though you paid fair market price during construction. If you are building in a market where home prices have grown more than 5 percent year over year, this risk is manageable. In a stagnant or declining market, you should budget an additional 3 to 5 percent contingency specifically to cover potential appraisal shortfalls at conversion.