What Actually Drives the Price
Public liability insurance premiums vary wildly depending on how your business operates, how much revenue you bring in, what you're covering, and where you're based. There is no flat rate. A freelancer writing copy at home pays significantly less than a construction contractor working on commercial sites. The difference can be anywhere from a few hundred dollars to tens of thousands per year. The core factors insurers weigh include your annual turnover, the nature of your work, claims history, the limit of cover you select, and whether you need coverage for products, completed work, or both. Location matters too. Operating in a high-litigation jurisdiction like the US or Australia tends to push premiums higher than in places with more restrained legal environments. How Much Is Public Liability Insurance really comes down to risk assessment. Insurers are trying to estimate the probability and potential cost of a claim against you over the policy period. If you run a small landscaping business, for example, they know there is a reasonable chance someone could get injured on your equipment or your work could cause property damage. That gets priced in.
Typical Cost Ranges by Business Type
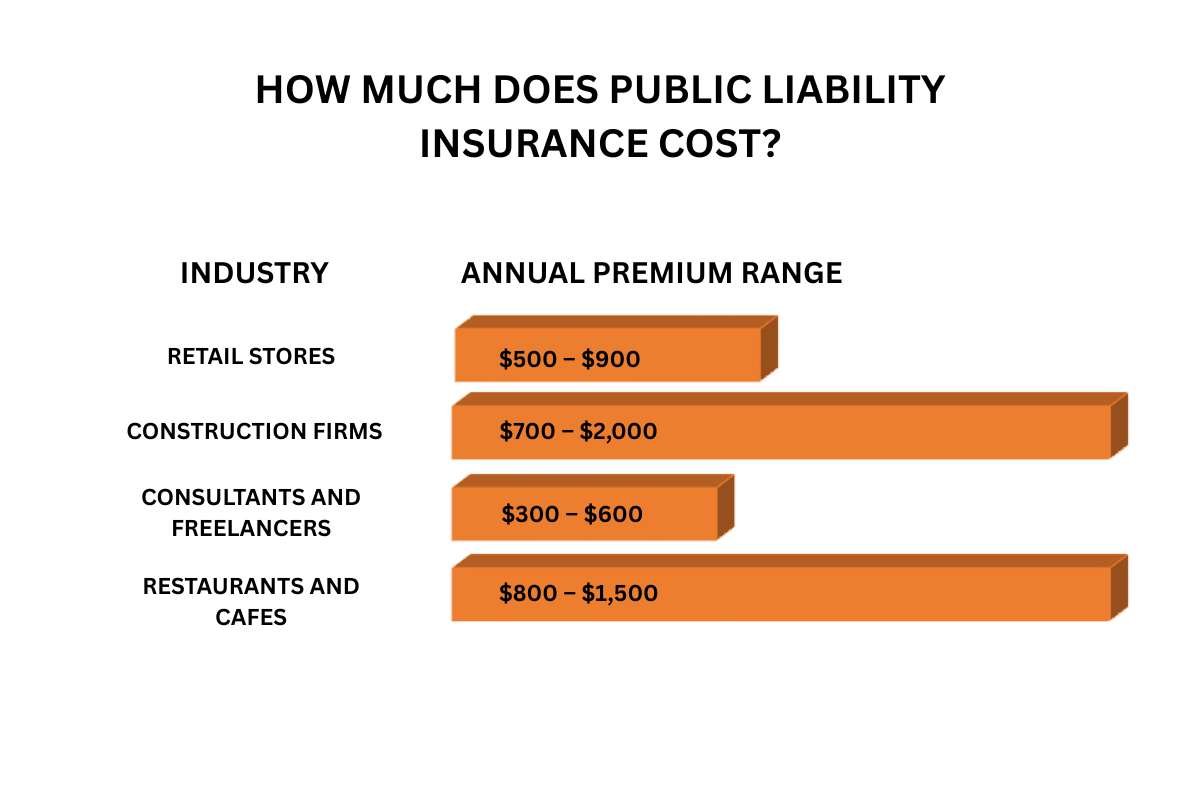
Here is what I have seen across different sectors, roughly speaking: Small service-based businesses like consultants, designers, or IT professionals typically pay between 300 and 1,500 dollars annually for a 1 million dollar limit of cover. These businesses have low physical risk exposure. Most claims would stem from advice-related issues rather than bodily injury on site. Maintenance and tradespeople—plumbers, electricians, painters—usually fall into the 500 to 3,000 dollar range for similar limits. Their risk profile is moderately higher because they work on client premises with tools and equipment around.
Construction contractors, event organizers, and businesses that regularly interact with the public in physical spaces often see premiums between 1,500 and 10,000 dollars or more. A builder doing residential renovations with a 2 million dollar limit might pay around 2,500 to 4,000 dollars a year depending on the scale of projects and past claims. Event management is a separate beast entirely. One-off events can sometimes be insured per-day for 100 to 500 dollars, but a company running multiple events annually will need a comprehensive policy that runs several thousand. Insurers scrutinize these heavily because a single incident at a public event can generate massive third-party claims.
Get the Full Details
How I Figured Out the Real Cost
A few years back I was advising a client on insurance for a small events company. They had been quoted 8,000 dollars annually by a mainstream broker and were frustrated. I noticed the quote included products liability and completed operations coverage when they only needed public liability for a specific three-day festival. By narrowing the scope and specifying exact dates, locations, and attendance figures, the premium dropped to about 1,200 dollars for that event alone. The annual policy was renegotiated at 3,400 dollars instead. The key insight most people miss is that insurers price based on worst-case assumptions unless you give them precise details. Vague business descriptions lead to inflated premiums. Providing exact activities, square footage, expected attendance, and contract terms can materially reduce costs.
What Most People Get Wrong About Coverage Limits
Choosing a higher limit does not always mean proportionally higher cost. Jumping from 1 million to 2 million dollars in coverage might increase your premium by only 20 to 40 percent, not double it. Insurers view the additional 1 million as incremental risk because most claims settle well below that threshold. The biggest price jumps tend to happen when you go from standard limits into specialized or excess layers above 5 million. Another counter-intuitive point: having a clean claims history matters more than the size of your business in many cases. A small cleaning company with three claims in two years will pay more than a much larger firm with ten years of zero claims. Don't underestimate the long-term financial impact of filing even small claims. Some insurers apply surcharges for up to five years after a claim.
When Standard Policies Fail You
Standard public liability policies have significant gaps that catch people off guard. Most exclude professional advice or design errors. If a consultant's recommendation causes a client financial loss, that is not covered under a standard PL policy. You need professional indemnity insurance separately, and combining both can sometimes be done through a bundled policy at a modest discount. Another common gap is contractual work. Some policies require you to disclose all contracts above a certain value. Failing to do so can void coverage when you need it most. I have seen contractors denied claims because they did not report a single large project to their insurer, and the policy wording explicitly required notification of contracts exceeding 50,000 dollars. Volunteer work is another area where policies commonly fall short. If you run a nonprofit and your volunteers cause damage while working, a standard business PL policy may not extend to them. You need to verify whether volunteer coverage is included or purchase an endorsement.

Practical Steps to Get an Accurate Quote
Gather your annual revenue figures, a clear description of all business activities, any contracts over a set threshold, details of past claims, and the minimum coverage limit your clients or contracts require. Present this information upfront when requesting quotes rather than filling in forms blindly. Get at least three quotes from different types of providers. Brokers can be useful for complex businesses, but direct insurers and online platforms often offer competitive rates for straightforward operations. The brokerage model adds a commission layer that sometimes shows up in the premium. Read the exclusions carefully before buying. A cheap policy with narrow coverage is worse than a slightly more expensive one that actually covers your situation. Check what is excluded: intentional acts, contractual liability, pollution, employee injuries (those fall under workers compensation), and motor vehicle incidents are commonly excluded from standard PL policies.
The bottom line is that the cost depends entirely on your specific risk profile and how well you articulate it to the insurer. Getting an accurate price requires honesty about what you do, precision in describing your operations, and a willingness to shop around rather than accepting the first quote you receive.