Working with nominal GDP in practice
Nominal GDP is the raw output value of everything produced in an economy at current prices. That's it. No adjustments for inflation, no smoothing, just the sum of all final goods and services valued at whatever price tags were attached on the day they sold. Most people I talk to confuse this with real GDP, and that confusion shows up fast in spreadsheets. The formula is straightforward, but the data work isn't always: Nominal GDP = (Current Price × Current Quantity) for every final good and service produced in a given period.
Break it down. You take each final good or service, multiply its price in that same year by the quantity sold in that same year, then add everything together. The key word is "current." Both the price and the quantity must come from the same time period. Mix a 2019 price with a 2023 quantity and you're not doing nominal GDP anymore, you're just making a mess. I've seen junior analysts pull sector-level output data from one vintage of a government dataset and price indices from a later revision, then wonder why their numbers don't match the headline figure. It happened to me early on when I was building a regional breakdown for a pension fund client. The state published revised quantity estimates six months after releasing new price data, and I had already locked in my model with mismatched vintages. My fix was to go straight to the source microdata and rebuild the year-by-year price-quantity pairs from the original survey responses instead of relying on the summarized tables. It added about three hours to the work but saved me from presenting garbage to a room full of portfolio managers. The expenditure approach is the version most people encounter:
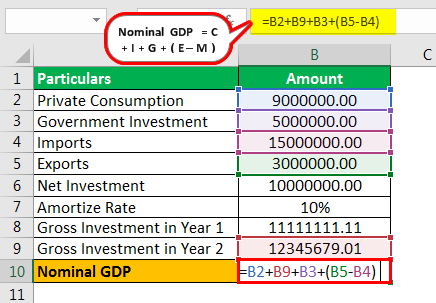
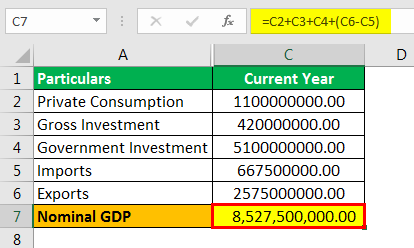
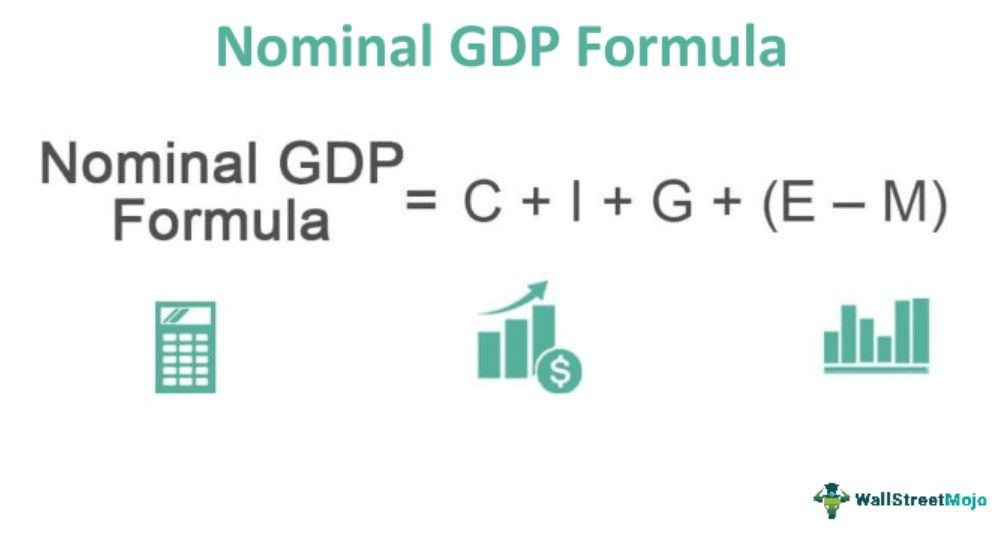
Nominal GDP = C + I + G + (X M) Consumption plus gross investment plus government spending plus net exports. Every component measured in current dollars. This is the method used by the BEA, StatCan, and most national statistical offices for their quarterly releases. It's also where most errors creep in, because the components come from different surveys with different release schedules and revision cycles. Take government spending as an example. It includes all government consumption and investment but explicitly excludes transfer payments. If you include Social Security or unemployment benefits in G, your nominal GDP will be overstated. I once had a model that inflated nominal GDP by roughly 4 percent for two consecutive quarters because someone on my team included all federal outlays rather than filtering to actual government consumption and investment. The fix was straightforward but tedious: I pulled the BEA table 1.1.5 breakdowns and rebuilt the G series line by line instead of using a summary figure from a press release.
Get the Full Details

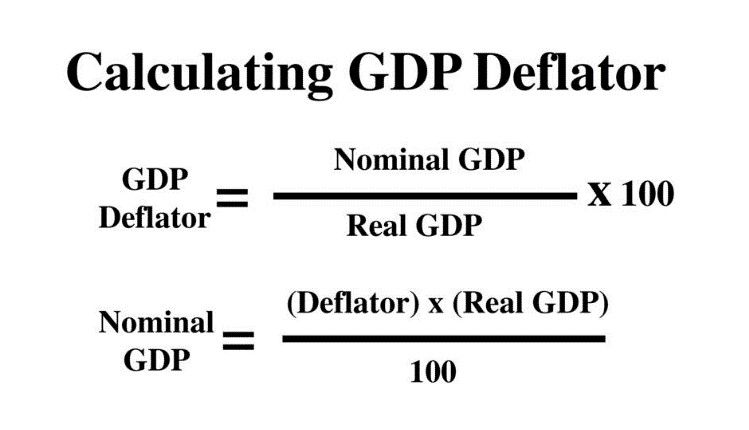
Here's a concrete example. Let's say an economy produces only two goods: wheat and bicycles. In 2024, wheat sells at $3 per bushel and 10,000 bushels move. Bicycles sell at $500 each and 2,000 are sold. Nominal GDP for 2024 is (3 × 10,000) + (500 × 2,000) = 30,000 + 1,000,000 = $1,030,000. Nothing fancy. The calculation is trivial. Getting the underlying numbers right is where the work lives. One thing beginners consistently miss: nominal GDP includes intermediate goods only indirectly through their contribution to final output. If a bakery buys flour to make bread, you don't add the flour separately. The bread's retail price already captures the flour's value. Double-counting intermediate transactions is the single most common error I see in student papers and in entry-level industry models. The value-added approach exists precisely to avoid this, but for nominal GDP calculated via the expenditure method, you sidestep the problem entirely by focusing on final purchasers. Another counter-intuitive point: nominal GDP can rise even when real output falls. If inflation is severe enough, the price effect can overwhelm a decline in quantities. I worked on a project tracking hyperinflation scenarios where nominal GDP grew 340 percent year-over-year while real GDP contracted 12 percent. The headline nominal figure looked like explosive growth until you ran the deflator. This is exactly why comparing nominal GDP across years without adjusting for price changes is misleading, but it's also why nominal GDP matters for certain applications, like debt-to-GDP ratios, where the relevant question is whether the economy can service debt in current dollar terms.
When you're actually computing this from raw data, the practical workflow usually looks like this. You gather quarterly or annual national accounts data from the relevant statistical agency. You verify that all components use the same base year for quantity measures if you need consistency, though nominal GDP by definition does not chain or seasonally adjust the price component. You check for catalogued revisions. National statistical agencies revise historical data constantly, and a number you pulled six months ago may have changed by a meaningful margin. Always note the vintage date on your data extract. For country-level work, the IMF's World Economic Outlook database and the World Bank's national accounts tables are reliable starting points. They publish nominal GDP in current US dollars and in current local currency. Use the local currency figures if you're doing cross-country comparisons that require a common price level adjustment later. The USD-converted figures introduce exchange rate noise that has nothing to do with domestic production. There are also edge cases where nominal GDP as a concept breaks down or becomes nearly impossible to calculate accurately. Informal and underground economic activity is never fully captured. In countries with large subsistence agriculture or unreported cash transactions, the gap between actual production and measured nominal GDP can be substantial. I spent a quarter working on a projection model for a Southeast Asian economy where the informal sector was estimated at roughly 25 percent of recorded GDP. Any nominal GDP figure for that country should come with that context attached, or it's essentially a partial measure presented as complete.
Another limitation: nominal GDP doesn't tell you about distribution, environmental costs, or welfare. A country can have rising nominal GDP while median household income stagnates and ecological degradation accelerates. That's not a flaw in the calculation, it's a limitation of what the metric represents. People sometimes treat nominal GDP growth as a proxy for prosperity, and that's a category error. If you need a downloadable template for computing nominal GDP from raw data, the BEA provides free Excel-based input-output tables and annual input-output use tables on their website. StatCan offers similar data through their CANSIM archive. For a quick calculation framework, you can build a simple spreadsheet with columns for product, current price, current quantity, and the price-quantity product, then sum the last column. I maintain a basic template that handles the C+I+G+(X-M) aggregation with automatic checks for transfer payments and intermediate goods, but honestly, any clean national accounts dataset will let you skip that effort entirely unless you're working with raw survey data. The main bottleneck in this work is data latency and revision. Quarterly nominal GDP estimates are preliminary for at least two release cycles. A Q1 figure released in April will likely be revised upward or downward by July, and again in October. If you're doing real-time analysis or forecasting, you need to track the revision pattern, not just the initial estimate. The initial release is a snapshot, not the final word. I've learned to tag every nominal GDP figure with its release vintage and revision status, which adds about ten minutes of bookkeeping per dataset but prevents embarrassing presentations when the final number comes out five percent away from the first release.
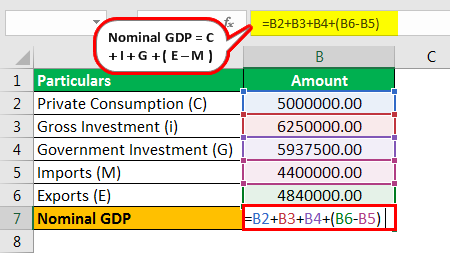
Bottom line: calculate nominal GDP by multiplying current prices by current quantities across all final goods and services, or by summing current-dollar expenditure components. Verify your data vintages, watch for double-counting, and remember that the number is a price-valued output measure, not a comprehensive economic health indicator. The math is elementary. The discipline is in the data handling.