The Basic Math Is Simple, Getting It Right Is Not
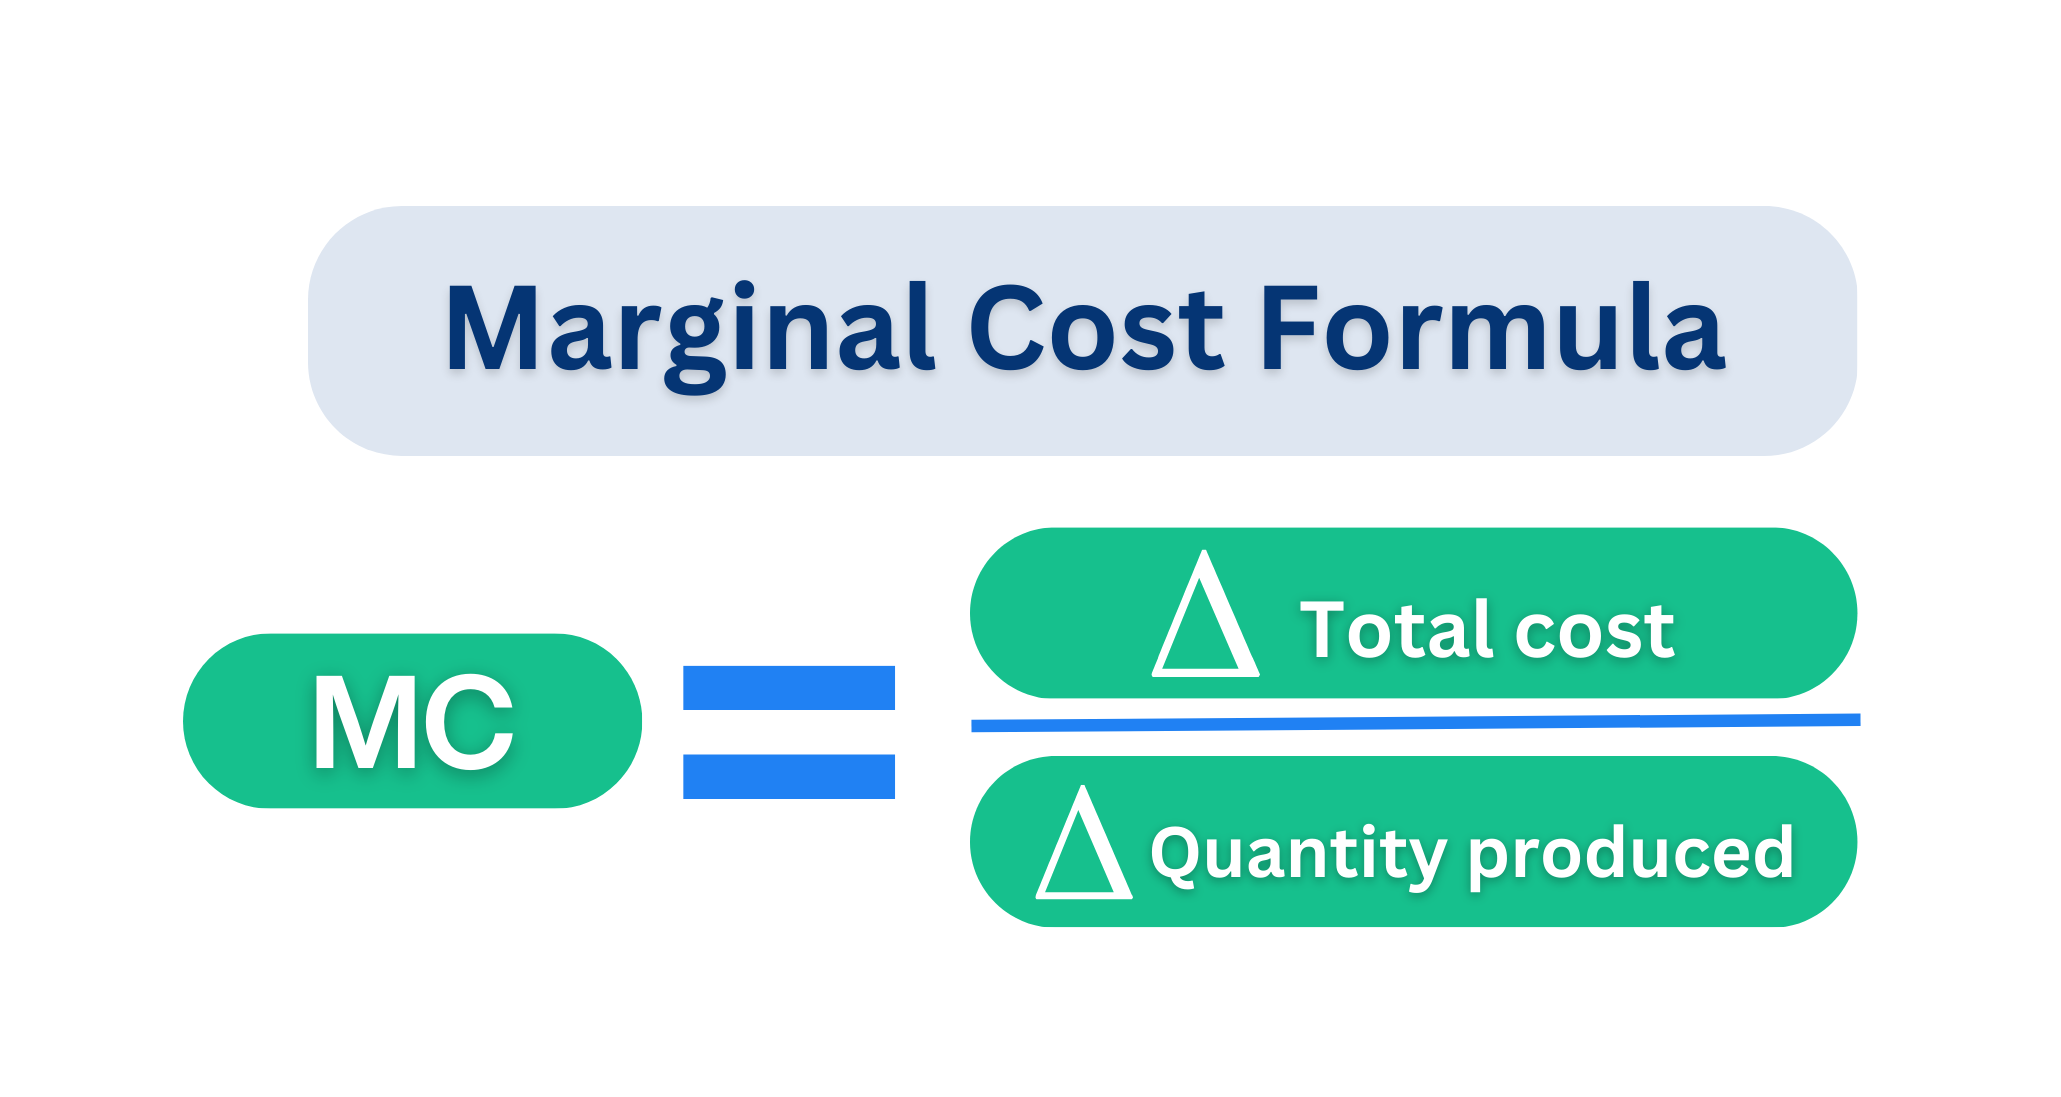
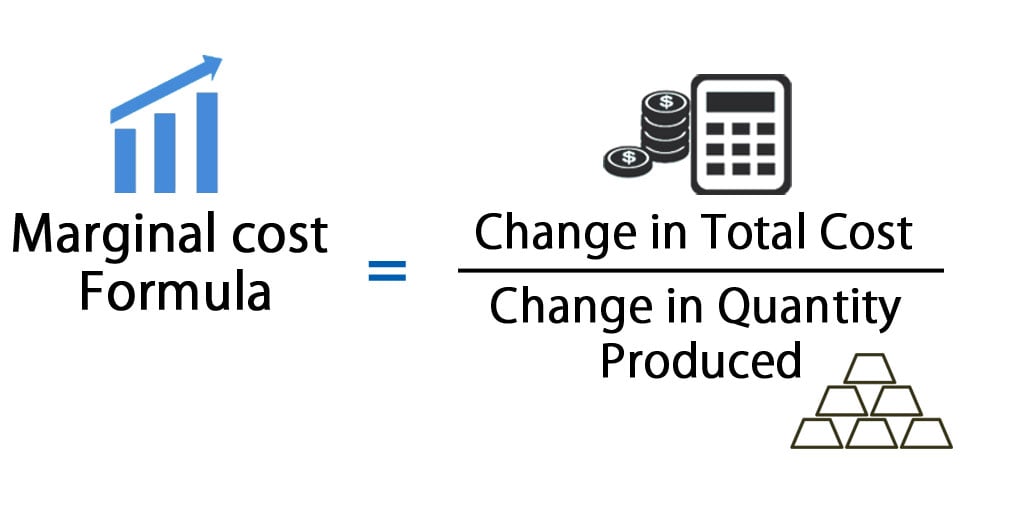
Marginal cost is the change in total cost divided by the change in quantity. That's it. If producing one more unit costs $4.50 instead of $4.10, your marginal cost just jumped. The formula itself takes five seconds to write down. The part people actually struggle with is figuring out what "total cost" means in practice, because accounting data doesn't hand you clean numbers on a silver platter. MC = TC / Q Delta TC over delta Q. Change in total cost, change in quantity. When quantity changes by exactly one unit, you can drop the denominator and just use the difference in total costs. Most introductory textbooks present it that way, which is fine for homework and completely useless if you're actually trying to price a product.How To Find The Marginal Cost In Real Production
In a spreadsheet environment where you have clean per-unit cost data, finding marginal cost is straightforward. You pull your total cost at quantity 100, then total cost at quantity 101, subtract, and you're done. The problem starts the moment you move beyond single-unit increments or deal with batch production where you can't actually produce just one more unit without committing to a whole batch. I spent three weeks trying to nail down marginal cost for a manufacturing line that ran in batches of fifty units. The accounting system gave me total costs at batch intervals—batch 1, batch 2, batch 3—but there was no way to get a cost figure for batch 1.5 or for producing forty-nine units instead of fifty. If I just took the difference between batch totals and divided by fifty, I was getting an average, not a marginal. The marginal cost of the last unit in a batch can look completely different from the marginal cost of the first unit in that same batch, especially when you're dealing with overtime labor or material waste that kicks in after a certain threshold. The workaround was to break total cost into variable and fixed components first. I mapped out what changed when we moved from one batch size to the next—direct materials, direct labor hours, machine time—and what stayed flat. Then I calculated the cost of the incremental units within the batch rather than treating each batch as an opaque black box. This took longer upfront but gave me a number I could actually trust when making pricing decisions.Where People Go Wrong
The most common mistake is confusing average total cost with marginal cost. Average total cost smooths everything out across all units produced. Marginal cost only cares about the next unit. At low volumes, these two numbers can be wildly different. If your fixed costs are high and you're spreading them over ten units, your average cost might look reasonable while your marginal cost is telling you that producing the next unit is prohibitively expensive once you factor in the overtime premium or the extra raw material order. Another trap is using historical cost data without adjusting for scale effects. If you've been producing at a certain volume for months, your past cost figures reflect that level of operations. Jumping to a different volume—say, doubling output—means your cost structure likely changes. Bulk material discounts might lower per-unit costs. Or you might need a second shift, which raises labor costs significantly. Past data alone won't capture that shift unless you model it explicitly.A Practical Walkthrough
Let me walk through a concrete example with actual numbers so you can see how the calculation behaves under different conditions. Say your total costs look like this:Producing 100 units: $2,400 total cost Producing 101 units: $2,428 total cost
Marginal cost of the 101st unit: $2,428 minus $2,400 equals $28. That's the actual marginal cost at that point. Now compare that to going from 100 to 200 units:Producing 200 units: $4,100 total cost
The change in total cost is $1,700. The change in quantity is 100. Divide those: $17 per unit. But this isn't the marginal cost of a single unit. It's an approximation across a range. The real marginal cost at unit 101 might be $28, and by unit 200 it could be $12 or lower, depending on whether you hit economies of scale or started incurring additional overhead. The $17 figure is useful as a rough estimate but misleading if you treat it as the cost of any specific unit. If you need precision for decision-making, smaller quantity increments give you tighter results. The jump from one unit to the next is the gold standard. When that's impossible, use the smallest increment your data allows and note the limitation.