Getting Your License And Capital Sorted
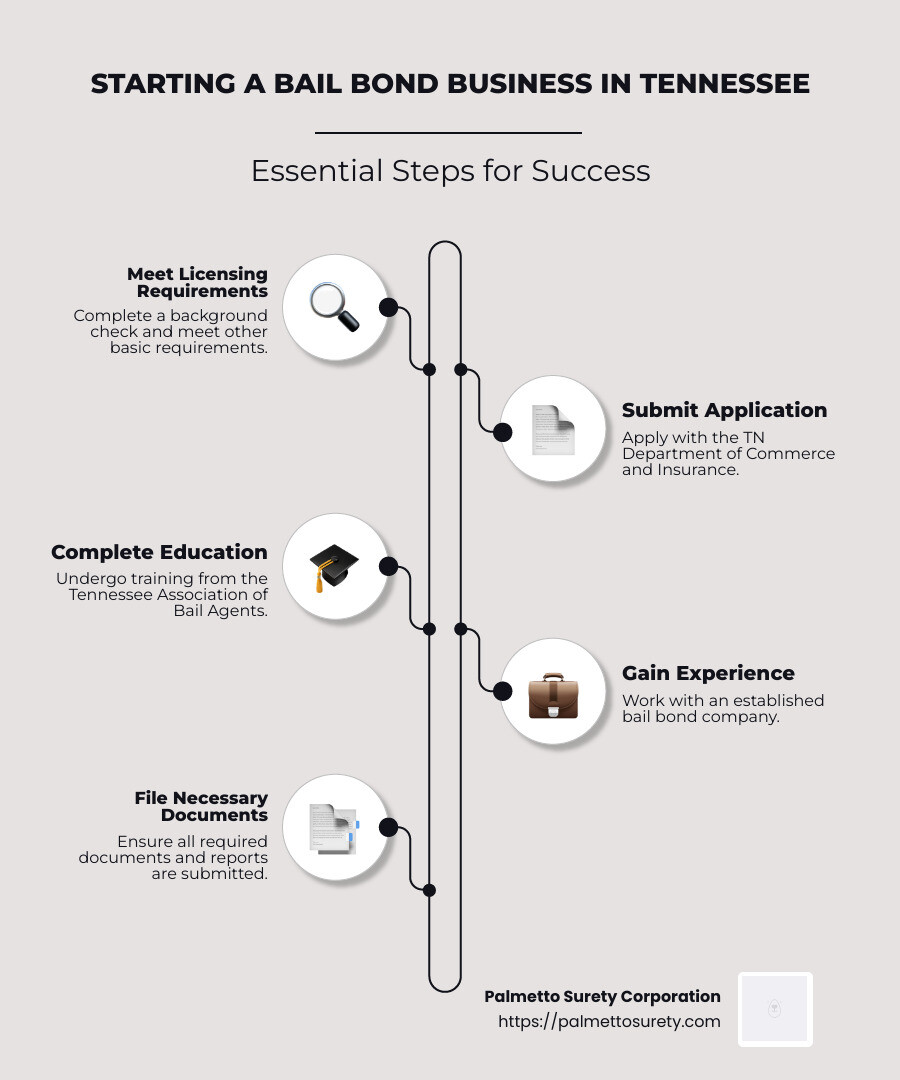
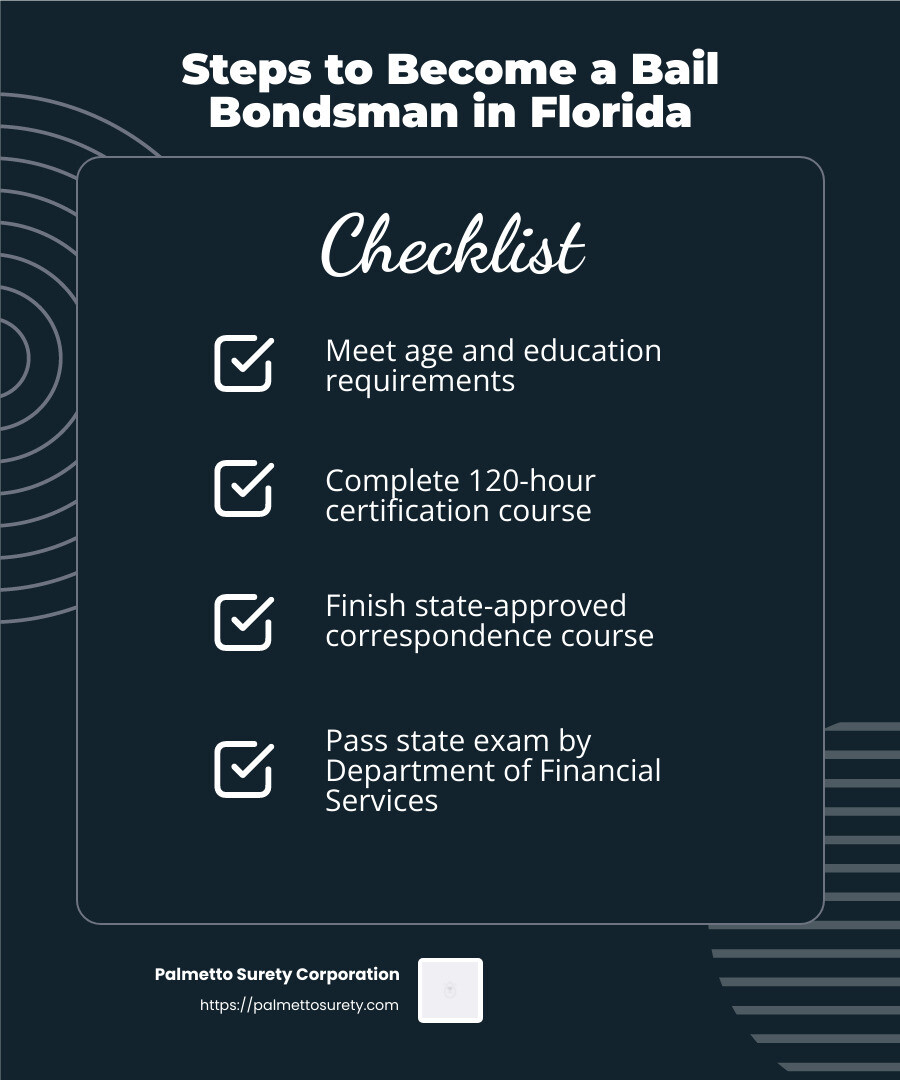
The actual path to How To Start A Bail Bonds Business starts with figuring out what your state even requires, because they vary wildly. Some states ban commercial bail bonding entirely — California, Illinois, Kentucky, Oregon, Wisconsin are the big ones. Then you have states like Florida where the barrier to entry is relatively low, and states like Texas where the paperwork is longer but the market is larger. Check your state's department of insurance or the bail bond regulatory body first before you spend any money. In most states that allow it, you need a license, a surety bond, and a designated collateral agent if your state requires one. The license application usually involves a background check, fingerprinting, and sometimes a formal exam. For California, you pass a state exam and maintain a $25,000 surety bond. In Texas, the exam is separate, the license runs for two years, and the premium tax alone is 2.5% of every premium you collect — something beginners routinely forget to budget for. Then there is capital. You need enough cash to post bonds before clients pay you back, which is the fundamental mechanics problem of this business. Most agents keep a minimum of $10,000 to $25,000 in liquid reserves. The more serious operators maintain a line of credit with a surety company that can cover larger bonds quickly. Without that, you are turning down work every time a felony case comes across your desk with a five-figure bail amount.
What No One Tells You About Surety Companies
Getting a contract with a surety company is the step where most new agents hit a wall, and it is not well documented. Surety companies are not banks. They do not lend you money. They issue the actual bond that guarantees the court the defendant will appear. You, the bail agent, are the one collecting the premium — typically 10% in most states — and the surety is on the hook for the full face value if the defendant absconds. Here is the part that catches people off guard: surety companies underwrite you the same way a lender would. They look at your personal credit score, your net worth, and your track record. A new agent with a 620 credit score is going to get either a very limited line of authority — maybe $5,000 per bond — or a flat denial. I learned this the hard way. My first application with a regional surety was rejected after they pulled my credit and saw a collection account from 2014 that I had completely forgotten about. The workaround was to pull my own credit report, identify every negative item, get them resolved or formally disputed in writing, and reapply three months later with supporting documentation attached to the application. The second application was approved within a week for a $20,000 line of authority. Another counter-intuitive thing: your line of authority does not scale linearly with your reputation. Some sureties give new agents a $10,000 line and then refuse to increase it no matter how clean the production looks. The workaround for that is to build relationships with multiple sureties from the start. Do not put all your bonding capacity with one company. Spread it across two or three so that when one refuses to bump your limit, you still have capacity elsewhere.
Setting Up Operations That Actually Work
Once you have your license and your surety contract, you need a few operational pieces in place. First is your fee structure. In most states, 10% is the standard premium rate, but some states cap it differently — Nevada is 10% with a $100 minimum, Connecticut caps at 15% on smaller bonds and drops to 8% on larger ones. Check your state's regulatory framework before you set your rates, because charging above the legal maximum is a fast track to losing your license. You also need a process for collecting premiums, which sounds trivial until a client says they will pay next week and then does not. I use a strict upfront payment model — premium collected before the bond is ever submitted to the court, no exceptions. This is non-negotiable. There is a specific edge case that caught me early on: a client brought in a defendant with a $50,000 bail, agreed to pay the $5,000 premium via check, and I held the bond submission until the check cleared. It bounced. The defendant was already in custody awaiting the bond, and by the time I re-contacted the client, the court had moved on and the scheduling was disrupted. Since then, I only accept certified funds or card payments for premiums, and I run the payment through before I call the court clerk. It adds about 15 minutes to the intake process but eliminates the worst-case scenario entirely. Your collateral management system is where most small agencies fail quietly. When a bond exceeds what you can absorb, you take collateral — vehicles, property deeds, jewelry, cash. The problem is tracking it. I have seen two agents in the same county lose their licenses because they could not produce receipts for collateral they claimed to hold during a routine audit. Maintain a digital log with scanned copies of every collateral document, photos of physical items, and signed release forms filed in a searchable system. Don't store physical collateral in your home office. Get a fireproof safe or a P.O. box rental at a storage facility.
Get the Full Details
Technology matters more than people think. A basic agency management system handles bond paperwork, tracks premiums, manages collateral records, and sends court date reminders. There are several options — BondSift, BailBondManager, and a few smaller regional platforms. I went with BondSift for a small operation and it cut my paperwork time from about 45 minutes per bond to roughly 12 minutes once I got the templates customized.
The Court System Is Your Real Bottleneck
Understanding how local courts operate is more important than any marketing strategy. Different counties have different booking times, different procedures for accepting bonds, and different expectations for agents. In some rural counties, bonds can be posted within 30 minutes of receiving the paperwork. In busy urban counties like Los Angeles County Jail or Cook County, the process can take four to six hours just for the bond to be processed and the inmate to be released, regardless of how fast you turn around the paperwork. Build relationships with the clerk's offices and the jail intake desks. Not through favors — through consistency. Show up on time, have your paperwork complete, and be professional even when the desk sergeant is having a bad day. I have a contact at two county jails who will literally call me if a bond has a problem before it gets rejected, which has saved me from multiple wasted trips and late-night rushes. That relationship came from showing up consistently for two years, not from any single interaction. Another thing that catches people: not all bail bonds are equal. A cash bond works differently than a surety bond. Some judges set conditional bonds that require check-in with a pretrial services officer or regular drug testing. Your bond contract needs to explicitly state what the defendant is required to do, and you need to communicate that clearly at signing. I had a case where the defendant thought he was free after posting bond and moved to another county, triggering a failure to appear warrant. The bond was forfeited because he violated the conditions, and since his collateral agreement didn't explicitly prohibit changing residence without written authorization, recovering anything was nearly impossible. After that, I rewrote my collateral agreement to include specific condition violations as defaults, and I read every bond condition aloud to the indemnitor before they sign.
Marketing And Risk Management
Marketing in this space is surprisingly constrained. You cannot advertise aggressively in many jurisdictions, and Google has tightened restrictions on bail bond advertising over the past several years. The most effective channels are referrals from defense attorneys, partnerships with jail visiting room businesses, and a functional website that shows up when someone searches "bail bonds near me." A clean, professional website with clear contact information and the ability to submit cases online captures more leads than most agents realize. The agents who invest in basic SEO and keep their site updated with local jail information tend to get consistent organic traffic within six to twelve months. Insurance is another practical requirement most people overlook until it is too late. Professional liability insurance protects you if a client sues over alleged misconduct in handling their bond. General liability covers you if someone gets injured at your office. If you employ anyone — and I mean even a part-time receptionist — workers compensation is mandatory in most states. The annual cost for basic coverage runs roughly $3,000 to $8,000 depending on your location and claims history, but going without it is an existential risk. The honest downside of this business that nobody pushes hard enough: the revenue is inconsistent. You might close five bonds in one week and three in the next. Economic downturns actually increase demand, but they also increase default rates. The defendants who skip court during a recession are more likely to stay skipped. Plan for at least six months of personal expenses covered before you quit your day job, and factor in a 15% to 20% non-recovery rate on bonds in your first two years, which is roughly industry average. Some months you will struggle to cover your overhead. Some months you will have more volume than you can handle. That variance is normal and it will test your finances regardless of how careful you are.
There is also the emotional weight of the work. You are talking to people at their worst moments — family members who just lost someone to arrest, people who are scared and making decisions they cannot fully process. The industry has a reputation for being predatory, and even if you operate honestly, you will hear that reflected in how clients treat you. Developing a flat affect and a consistent process is not about being cold. It is about not getting dragged into situations where your judgment is clouded by someone else's desperation. I stopped taking calls after 10 PM and on Sundays two years ago. The business did not collapse. One client called at 11 PM on a Saturday and hung up when I did not answer. She called back at 9 AM Sunday and was processed by 9:30. The urgency she felt was real, but the timeline she perceived was not.
When This Business Model Fails Completely
There are scenarios where starting a bail bonds business is a bad call. If you live in a state with heavy regulation and low bond volumes — a rural county with one small jail and a population under 30,000 — the math rarely works. Fixed costs like licensing, bonding, insurance, and software eat into thin margins before you write a single bond. Similarly, if your local market already has three or more established agencies with attorney relationships that are decades old, breaking in is harder than the industry literature suggests. The attorneys who refer cases have trusted relationships and switching costs are not zero. The most viable entry point is a growing suburb near a major metro area with a newer jail facility and no dominant local agency. Even then, the biggest bottleneck is your own capacity to handle volume. This is not a scalable business in the traditional sense. You cannot hire someone to make bonding decisions. You cannot automate the judgment call of whether to take a case based on the defendant's flight risk, the strength of their community ties, and whether the indemnitor's collateral is legitimate. Those decisions are yours and they get heavier, not lighter, as you gain experience. The agents who thrive are the ones who know when to say no, and the ones who recognize when a case is too risky regardless of the premium. The licensing process for How To Start A Bail Bonds Business typically takes between four and eight weeks from application to approval, assuming no complications with your background check or credit history. Budget approximately $500 to $1,500 in upfront costs for licensing, examinations, surety bonds, and initial insurance. Factor in another $2,000 to $5,000 for a basic management system, marketing materials, and operational supplies like scanners and secure storage. The total startup range for a lean operation is roughly $3,000 to $8,000 depending on your state and how much you already own versus what you need to purchase.