The paperwork nobody warns you about
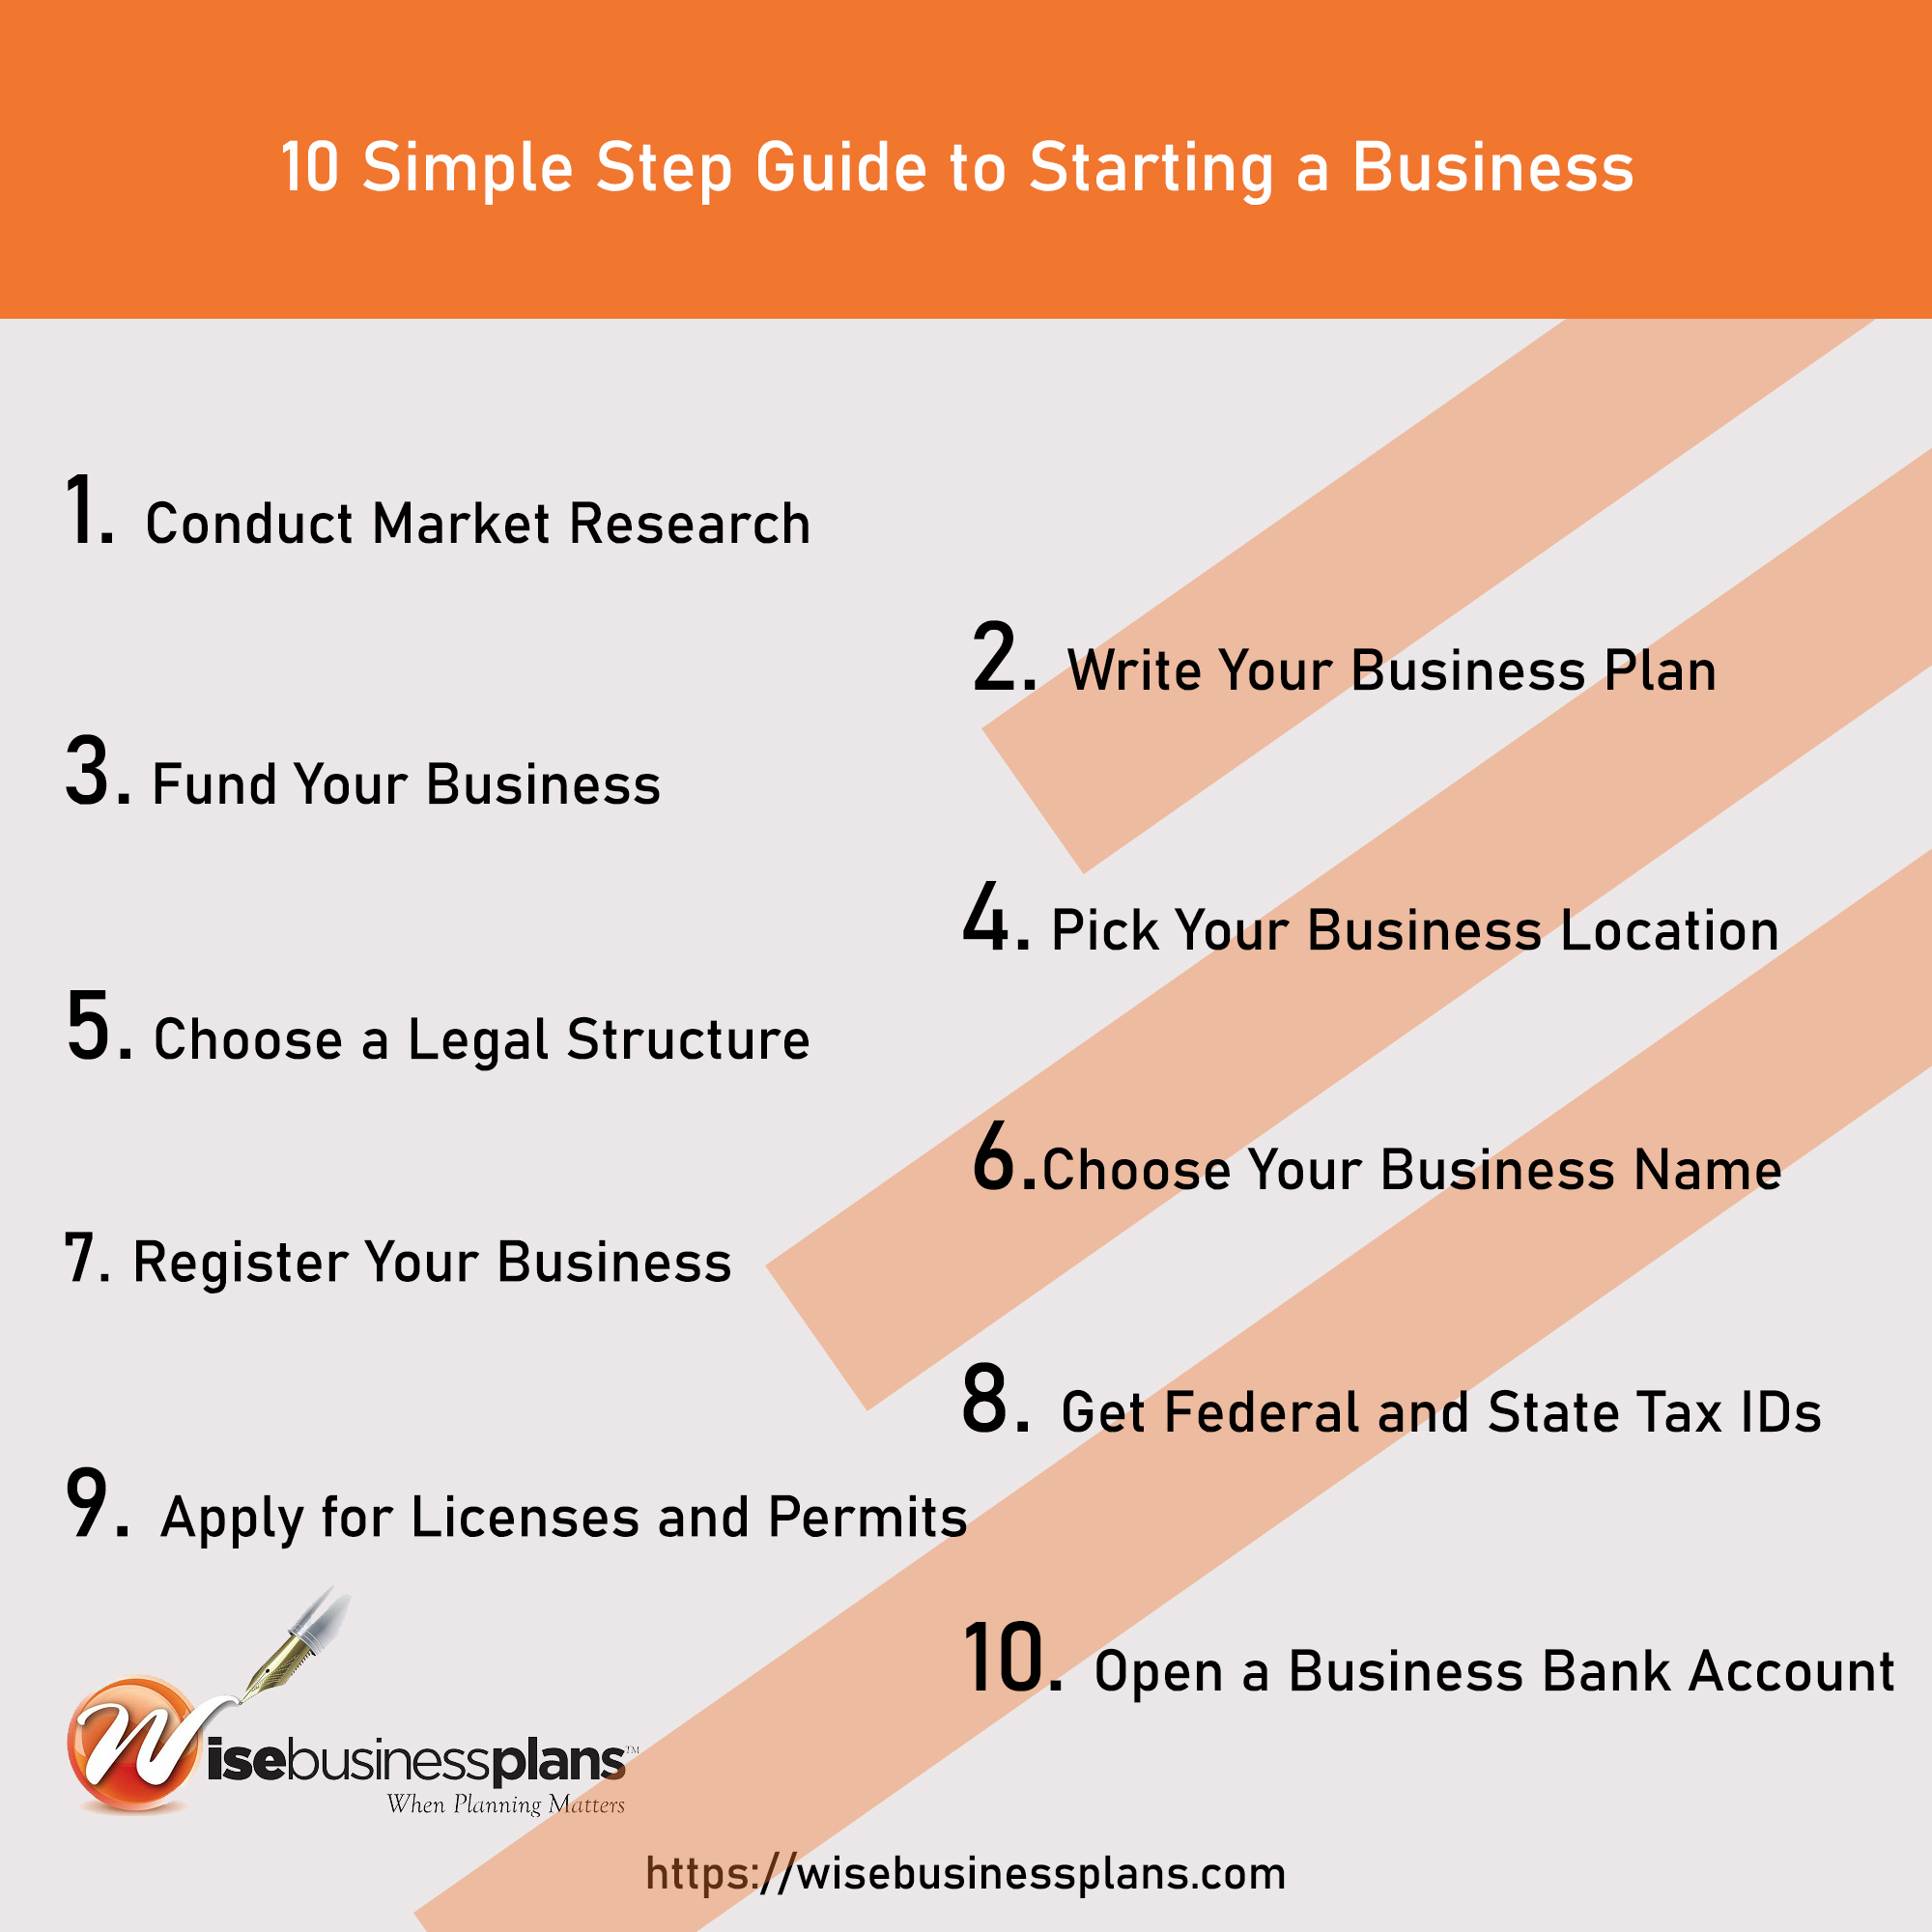
Most people think forming a corporation is just filing a form and you are done. That is wrong. The form is the easy part. The stuff that actually matters happens before and after, and most first-time founders skip it or do it lazily because they assume it does not matter much. Here is the sequence. Step one is picking your state. This is where most people waste money. If you live in Delaware but run a coffee shop in Ohio, there is almost no reason to incorporate in Delaware. You will pay Delaware franchise tax and still have to register as a foreign entity in Ohio. I learned this the hard way back in 2014 when I incorporated a holding company in Delaware for a project that never launched. The $300 annual franchise tax ran up for eighteen months on a dead project while I was paying for nothing. The fix was straightforward: I dissolved the Delaware entity and restarted under my home state. It cost about forty dollars in filing fees to unwind it. Lesson stuck. Step two is choosing a business name and running a name availability search through the secretary of state's database. This sounds trivial until you find out someone already registered a confusingly similar name three towns over. I once spent two hours rebranding a mock launch because a limited liability company in another county had a nearly identical name. The state would have approved it, but the trademark search later would have been a nightmare. Check the USPTO database too, not just the state database. Those are two different registries and neither talks to the other.
Step three is appointing a registered agent. You can be your own registered agent if you have a physical street address in the state of incorporation and you are available during normal business hours. A lot of people do this to save money. It works fine until you work from home and get served with process at your kitchen table at ten in the morning. I switched to a paid registered agent service after a vendor lawsuit delivery arrived while I was on a call with a contractor. The agent caught it and forwarded it within the hour. If you miss a service of process window, the consequences are worse than the annual fee for a registered agent. Step four is filing the articles of incorporation. This is the actual legal birth document. You need to include the corporate name, the registered agent, the purpose of the corporation, and the authorized share structure. The share structure part is where people get sloppy. I have seen founders authorize ten million shares on a whim, then regret it when they try to bring in investors later. Every extra share you authorize costs money in some states and creates unnecessary complexity on your cap table. Start with something reasonable like one million authorized shares with a par value that makes sense for your industry. You can always increase authorized shares later through a board resolution. Step five is creating corporate bylaws. This is an internal document. The state does not file it. Most first-time founders ignore it entirely, which is a mistake. Bylaws define how the corporation actually runs. They cover things like how directors are elected, how meetings are called, what constitutes a quorum, and how officers are appointed. Without bylaws, you are operating under whatever default state statute says, and those defaults are written for companies that have been around for decades. They are not optimized for a two-person startup. I draft a standard set of bylaws and customize them for each new venture. It takes about twenty minutes once you have a template you trust.
Step six is issuing stock to the founders. This is where Section 83(b) elections come into play if you are in the United States. When you issue restricted stock to founders, the IRS treats it as income that gets taxed as it vests unless you file an 83(b) election within thirty days of issuance. That election locks in your tax basis at the current fair market value, which for a brand new corporation is usually close to zero. If you skip it, you could end up owing ordinary income tax on shares that vest later when the company is worth significantly more. I have seen founders lose tens of thousands of dollars because they thought the stock issuance was just paperwork. It is not. It is a tax event. File the 83(b) with the IRS and keep proof of mailing. Step seven is getting an Employer Identification Number from the IRS. This is free and you can get it online in about ten minutes. You need this for everything: opening a bank account, hiring employees, filing taxes. Do not delay this. Some states will not let you complete your formation without an EIN. The IRS issues them instantly during business hours. Outside those hours, you can still apply online but you will receive the number by mail in about a week. Step eight is opening a business bank account. Bring your articles of incorporation, your EIN confirmation letter, your corporate bylaws, and a resolution from the board authorizing the account opening. Some banks will ask for additional documents depending on the structure. Keep everything organized in a folder. I use a shared drive with scanned copies of every document. It saves time whenever a bank or investor asks for something unexpected.
Get the Full Details

After all of that, you have formal corporate obligations. Annual meetings. Minutes. Franchise tax filings. State annual reports. These are not optional. Missing an annual report can result in your corporation being administratively dissolved, which means you lose the liability protection you spent weeks setting up. I set calendar reminders for every filing deadline and pay for a corporate compliance service that tracks them automatically. It costs about two hundred dollars a year and saves you from the panic of realizing you missed a deadline by three weeks.
Where the process breaks down
There are real limitations to this approach that most guides do not mention. The biggest one is that forming a corporation does not protect you from personal liability in every situation. If you personally guarantee a loan, sign a lease as an individual, or commingle personal and business funds, the corporate veil can be pierced. I watched a founder lose personal assets because he used the business checking account to pay his personal mortgage for eight months. The court ruled the corporation was his alter ego. The corporate structure meant nothing in that case. Another issue is the cost of maintenance. Corporate compliance is not free. Legal fees for drafting proper documents, accounting fees for quarterly and annual filings, state franchise taxes, and registered agent fees add up. In some states, the annual franchise tax alone can exceed one thousand dollars. If you are running a side project with under fifty thousand in annual revenue, a corporation may not make financial sense. An LLC with pass-through taxation might be the better choice here. The corporate structure is designed for companies that plan to raise venture capital, issue stock options to employees, or eventually go public. If your goal is just to operate a small business with minimal liability exposure, an LLC does most of what you need at a fraction of the cost and paperwork. The foreign qualification process is another pain point that people underestimate. If you incorporate in one state but operate in another, you must register as a foreign corporation in every state where you conduct business. Each state has its own form, its own fee, and its own annual report requirement. New York, for example, requires publication of your formation in newspapers, which can cost anywhere from five hundred to two thousand dollars depending on the county. I had a client who incorporated in Delaware, operated in New York, and did not realize the publication requirement until a lender asked for proof of good standing. It took six weeks and eight hundred dollars to cure.
If you want a simpler path that avoids most of these complications, forming an LLC in your home state and electing S-corp tax status if it makes sense for your tax situation is usually the smarter default. The corporate structure has advantages for fundraising and employee equity, but those advantages only matter if you are actually pursuing those paths. Most businesses never do. Check with a qualified attorney or CPA before making the final decision. The forms are generic but the consequences of getting them wrong are not.