Where most people go wrong before they even file paperwork
I watched a friend spend nine months building a product for a market that didn't exist, then another four trying to figure out why his LLC wasn't protecting him the way he expected. He had the passion right. He just skipped three steps that take about twenty minutes if you know what you're doing. Here's how it actually works.
How To Start A Company The Way It Actually Works
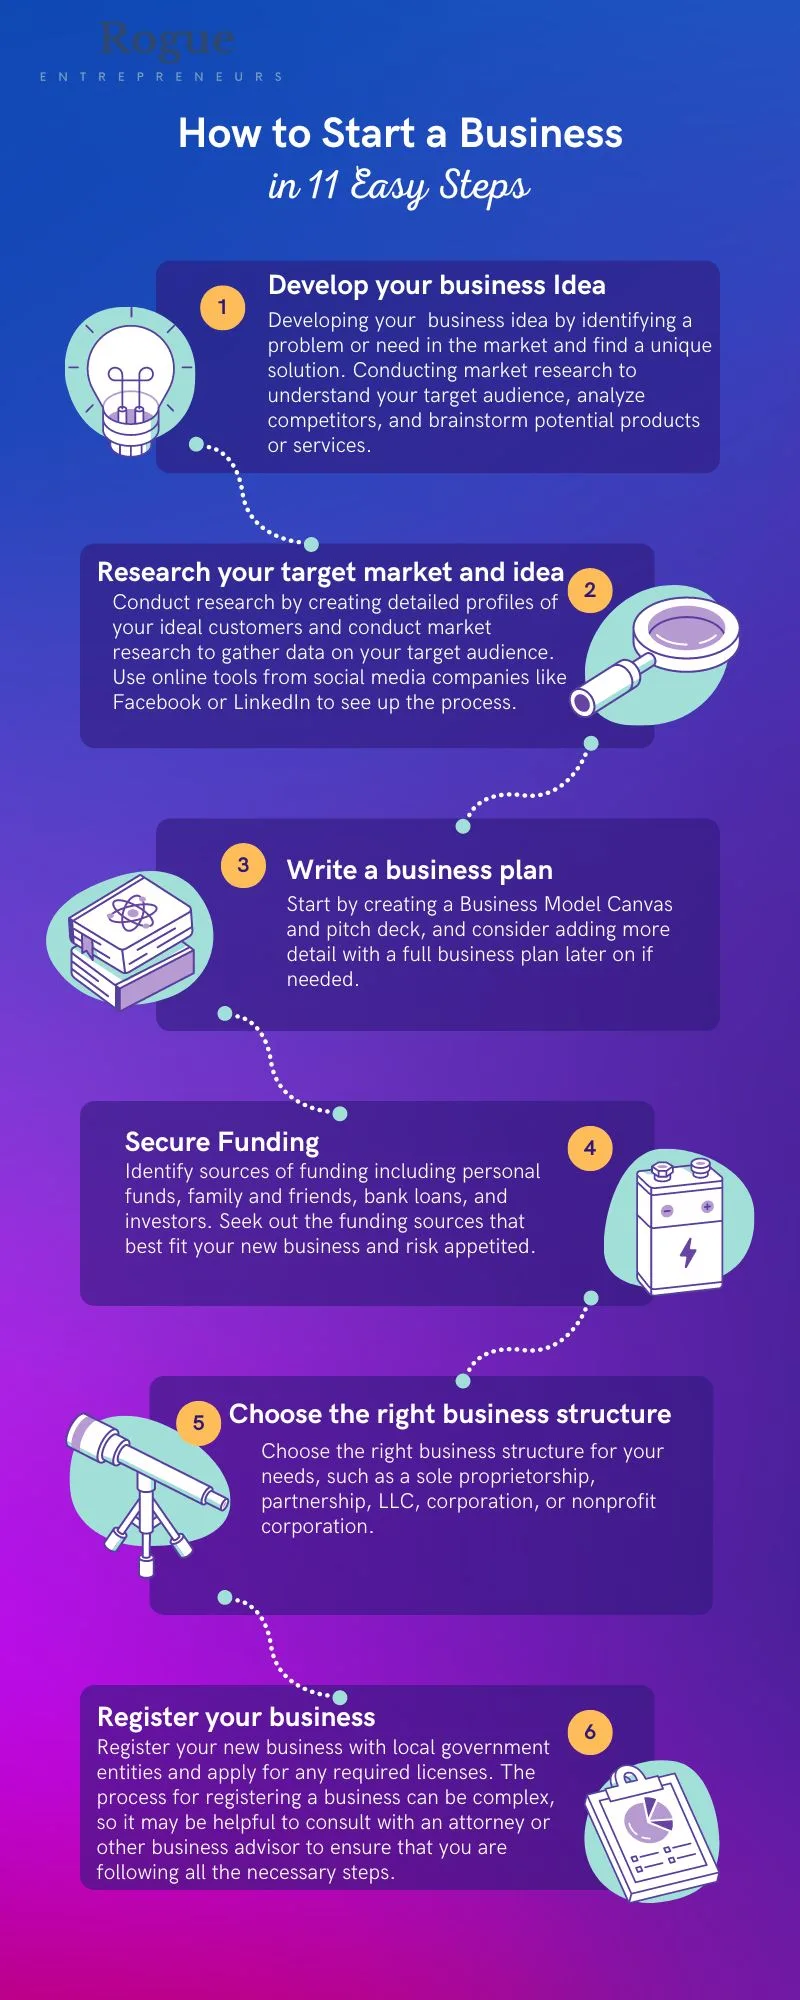
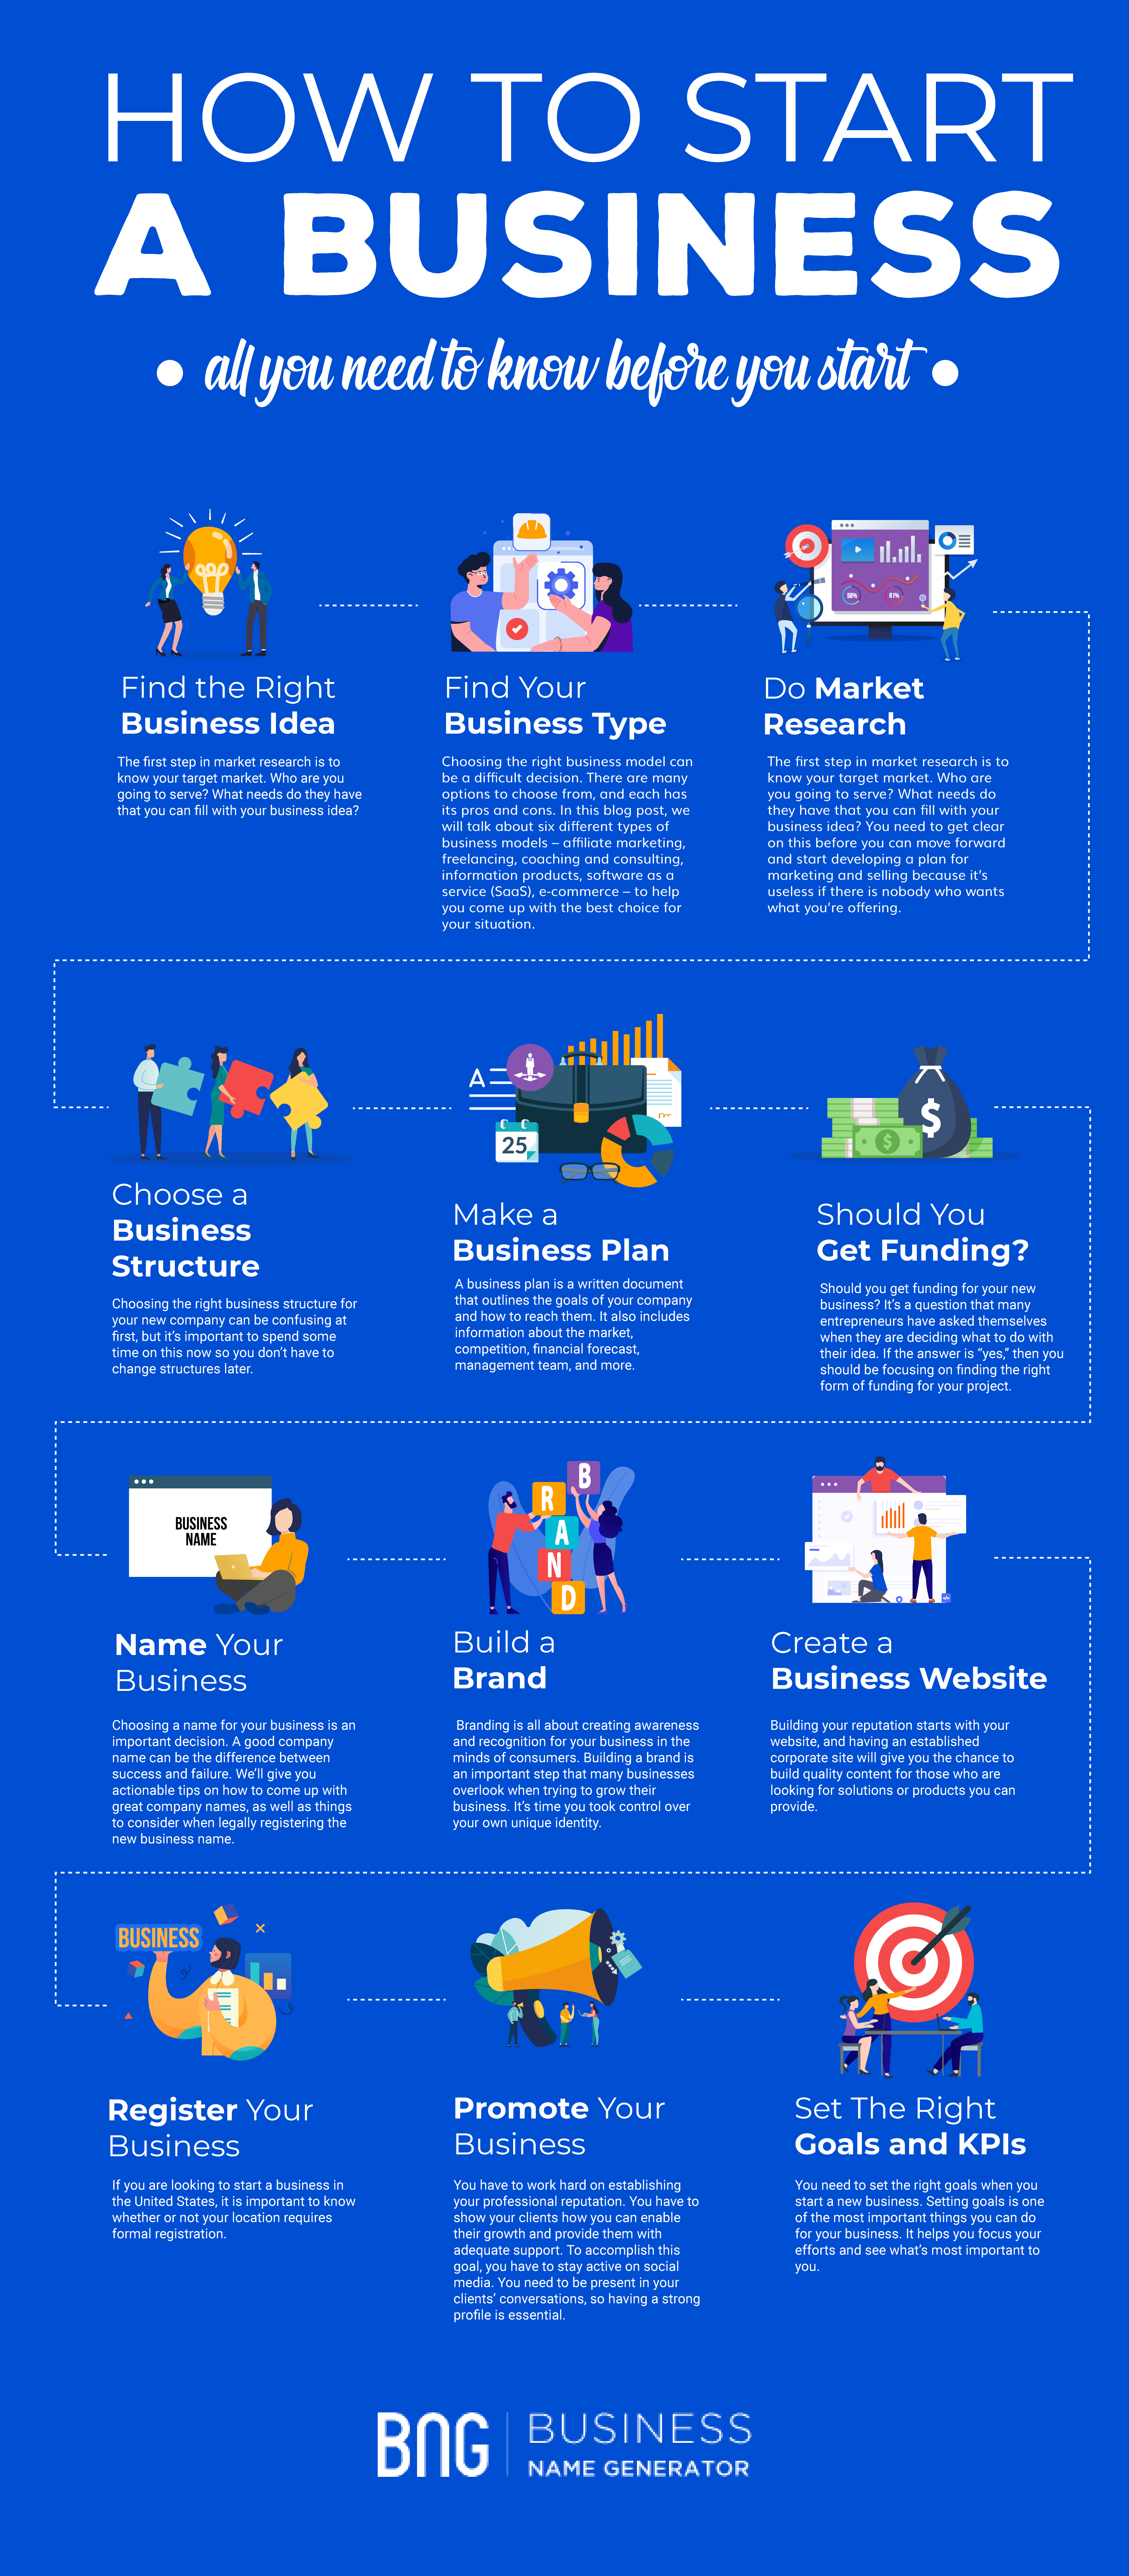
The first decision isn't which state to register in. It's what you're selling and who's actually going to pay for it. I filed my first business in Delaware because a lawyer told me it was the standard move. It wasn't. For a small service company with no outside investors and operations entirely in Ohio, it cost me extra franchise taxes and a registered agent I didn't need. Wyoming would've been cheaper. My home state would've been cheapest. The sequence matters more than anything else. I see people incorporate before they have a name, then waste weeks fighting naming conflicts because they picked something generic like "Apex Solutions" when there are already eleven Apex LLCs in their state. Pick a specific name. Run it through your Secretary of State's database. Check Trademark Electronic Search System if you plan to build a real brand. Do that before you incorporate, not after.
Paperwork and the stuff nobody warns you about
Forming the entity is mechanically simple. Most states let you file online in about fifteen minutes. The cost ranges from fifty to a couple hundred dollars depending on your state and whether you use expedited processing. That part is easy. The hard part starts after the state approves your filing. You need an EIN from the IRS. It's free, it's instant if you do it online, and you absolutely cannot skip it. I had a client who tried operating under just his personal SSN for eight months because he thought he could get it later. He ended up with mismatched 1099s and a messy year-end reconciliation that took a tax professional three hours to fix. The EIN takes eight minutes. Don't treat it as optional. Then there's the operating agreement for an LLC or bylaws for a corporation. States don't always require you to file these documents, but you should create them regardless. Without an operating agreement, your LLC defaults to your state's statutory rules, which are written for companies that don't have custom arrangements. In one case I dealt with, a two-member LLC in Tennessee split down the middle on a decision. Without a written operating agreement specifying how ties get broken, they were stuck interpreting default statute language that assumed majority rule. We spent six thousand dollars in legal fees resolving something a two-sentence clause in the operating agreement could have prevented entirely.
Get the Full Details

The compliance trap that catches everyone
Most people think starting a company means one afternoon of paperwork and then you're done. That's when things fall apart. Your company has ongoing obligations the week after formation. Open a business bank account. Not a shared account. Not a account you also use personally. A dedicated one. When you commingle funds between your personal and business accounts, you pierce the corporate veil in a way that makes your liability protection meaningless. I've seen it happen. A contractor paid from a personal account for business supplies, then got sued. The plaintiff's attorney pulled bank statements showing the accounts were functionally identical. The judge let the case proceed to personal assets. Get an operating agreement drafted. File it internally. Sign it. Date it. Put it in a folder. You won't look at it again for years, but you'll need it the day someone questions your company's legitimacy.
Register for state and local taxes. Sales tax permits, employer withholdings if you hire anyone, annual report fees. The specific requirements depend entirely on your jurisdiction and business type. Check with your state's department of revenue and your county clerk's office. Missing an annual report filing in Colorado, for example, results in automatic administrative dissolution of your LLC. That happened to a friend of mine who forgot for one year. Restoring the entity cost him four hundred dollars in fees and three weeks of downtime while clients questioned whether he was still operational.
When to talk to a professional versus when to DIY
Here's my actual rule of thumb based on what I've seen go right and wrong over the years. If you're a solo founder running a single-member LLC, providing services or selling low-risk products, and you're not seeking outside investment, you can handle the formation yourself in a weekend. Use LegalZoom, your state's filing portal, or a straightforward template from a reputable source. The savings are real. If you have multiple founders, equity splits, vesting schedules, or plans to raise money, hire a business attorney. The lawyers who charge four thousand dollars to set this up properly save their clients from problems that cost forty thousand to fix later. I watched one co-founder dispute escalate because the original operating agreement had no buy-sell provision. The company was stuck in legal limbo for eleven months. A well-drafted agreement with clear exit terms costs about the same as what they ended up paying in litigation, except it actually prevents the problem instead of resolving it after the damage is done.

What comes after formation that nobody mentions
Your business needs a basic compliance calendar. Annual reports. Franchise tax payments. Business license renewals. Industry-specific filings if applicable. Set reminders in your calendar for each one. The cost of missing a deadline is almost always higher than the cost of filing on time. Bookkeeping starts day one, not after you've made money. Pick a system. QuickBooks, Wave, or even a well-organized spreadsheet if you're keeping it simple. Track every transaction. Separate business and personal. Receipts matter. I can't stress this enough. The IRS doesn't care that you lost the receipt for a three-thousand-dollar equipment purchase. Without documentation, that deduction disappears and your taxable income goes up accordingly. Insurance is another thing people skip until it's too late. General liability, professional liability if you provide advice or services, workers compensation if you hire anyone. A single mistake on a client project without professional liability coverage can cost you more than your business will ever make in a decade. I know someone who got sued for two hundred thousand dollars over a consulting error. He had zero E&O insurance. The settlement ate his personal savings and a portion of his house equity.
The counter-intuitive part about incorporation timing
Most people think you should form the company before you do any work. That's usually wrong. If you're still figuring out whether anyone will pay for what you're building, incorporating too early creates unnecessary overhead and potential liability exposure. Form the company when you have your first paying customer or a committed contract. Before that, you can operate as a sole proprietorship or do what I call a pre-revenue trial run: build the product, talk to customers, validate the idea without the administrative burden of an entity. That said, if you're entering into contracts, handling other people's money, or operating in a regulated space, form the entity before you start. The protection only exists if the company is in place when something goes wrong. A company formed after the incident doesn't shield you from it. There's also the question of intellectual property. If you're writing code, designing products, or creating content before incorporation, that IP belongs to you personally. You need to assign it to the company once the entity exists. A simple assignment agreement covers this. Without it, you own the IP, not your company, which creates problems if you ever try to sell the business or bring in investors who want to verify ownership.
A quick note on what I learned the hard way
Early in my experience with this, I incorporated a company in a state that offered perceived benefits but required a foreign qualification in my actual state of operation. That meant double filing, double fees, and double compliance work for no real advantage. The other founder insisted on it because of something he read online. We ended up spending about eight hundred dollars more than we needed to and dealing with two states' regulatory requirements instead of one. The workaround was straightforward once I figured it out: check whether your home state recognizes the formation state's benefits for your specific business type before you file anywhere. Sometimes the benefit is real. More often it isn't for small businesses. Just make sure whatever structure you choose actually matches what you're doing. There's no universal best answer. There's only what fits your situation and what you're willing to maintain.