Working Out Real GDP Without the Textbook Fluff
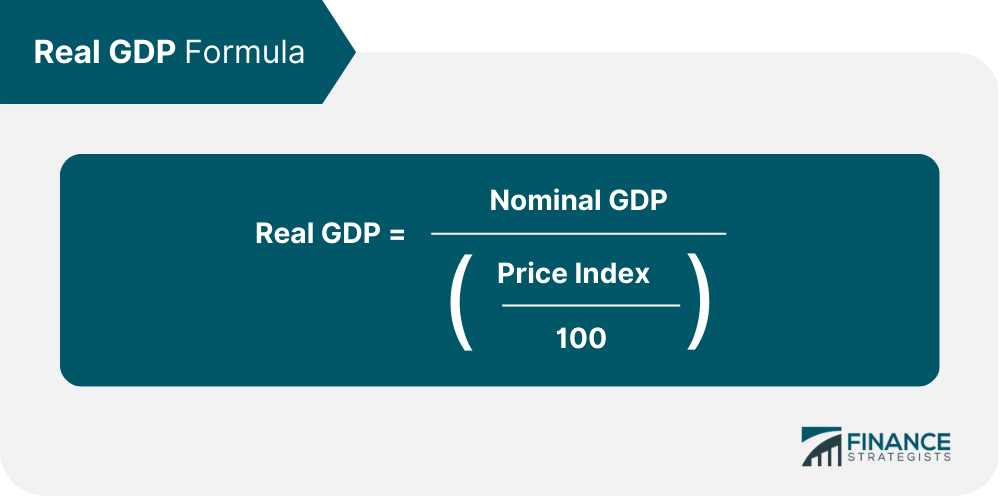
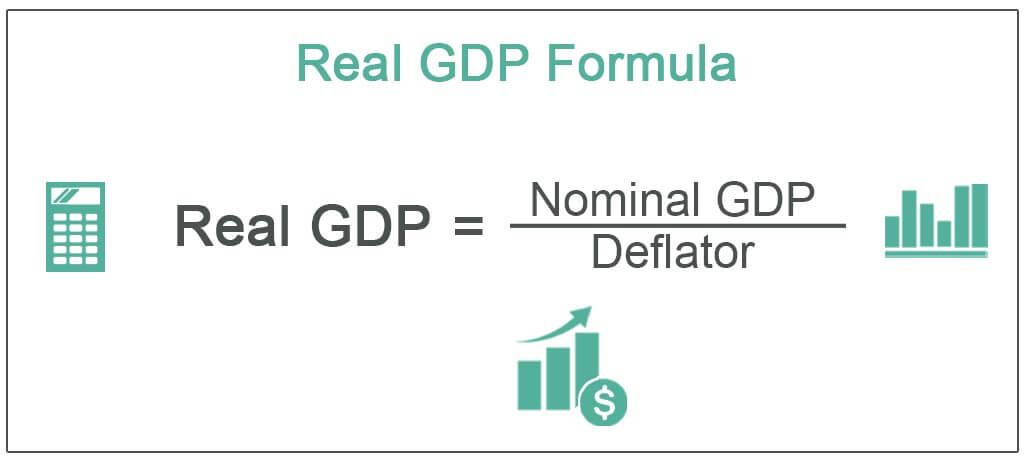
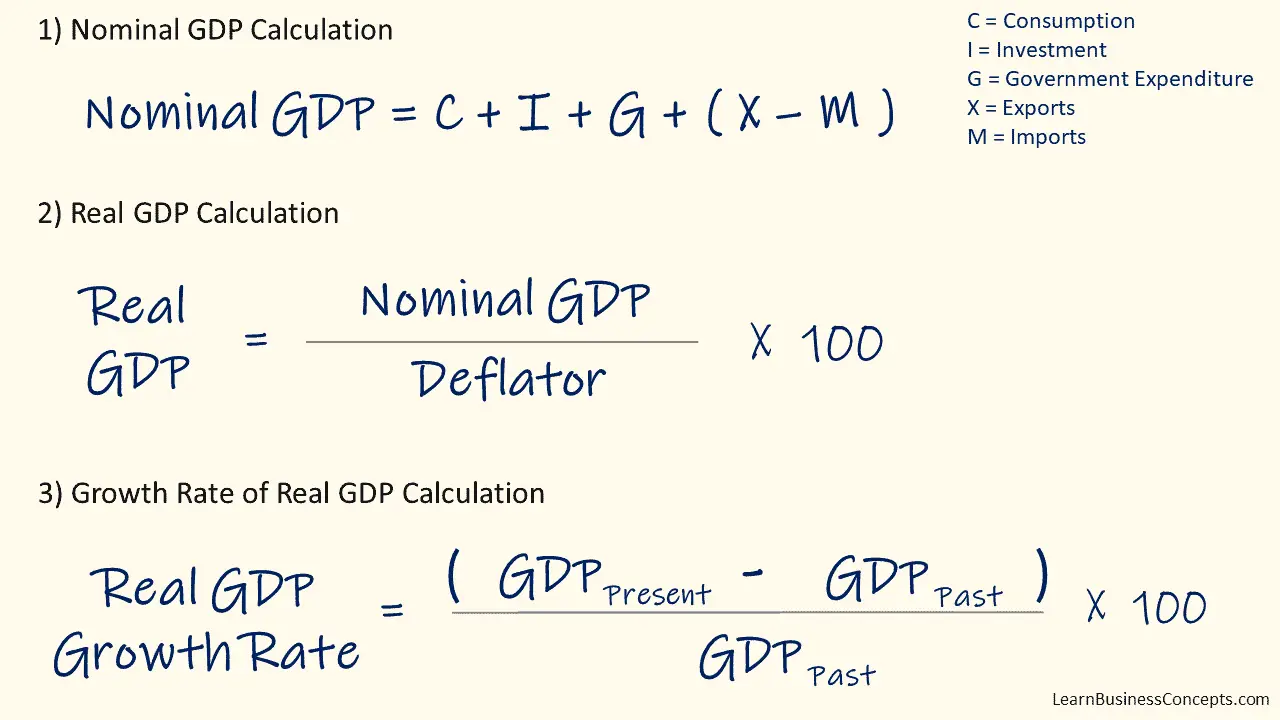
Most people learn the nominal-versus-real GDP distinction in macroeconomics 101 and then never really use it again until they're forced to somewhere down the line. I spent three years working in economic forecasting where we adjusted state-level output numbers every quarter, and the gap between what the spreadsheet said and what actually happened on the ground was usually wider than anyone outside the profession expected. You start with nominal GDP, which is just the raw market-value total of everything produced in a given year using current prices. Then you pick a base year and pull a price index—usually the GDP deflator or sometimes CPI if you are working with consumption only. The formula itself looks stupidly simple: divide nominal by the index and multiply by 100. That is where the simplicity ends. The real pain comes from the data. Different agencies use different base years, different basket compositions, and occasionally they revise the whole series backward when methodology changes. I once spent two weeks chasing down why our regional real output growth number looked wrong, only to find the statistical bureau had quietly switched from chained dollars to fixed-weight prices mid-decade. You have to check the methodology notes every single time you pull a new dataset, not because you do not trust the numbers but because the definition of the measurement changes without warning.
When you actually do the division, remember that a year with high inflation will show a much larger gap between nominal and real than a stable year. The 1970s in the United States are a classic example, where nominal GDP grew at double-digit rates but real growth was barely positive because prices absorbed most of the headline number. If you skip the deflator step and just look at nominal growth during periods like that, your analysis will be completely misleading.
Where This Method Breaks Down
Real GDP is not a perfect measure of economic welfare, and anyone who tells you otherwise is selling something. It does not account for unpaid household labor, environmental degradation, or the underground economy, which can be substantial in developing countries. During the 2022 energy crisis in Europe, real GDP numbers looked surprisingly flat in several nations even though living standards deteriorated noticeably for ordinary households, because the price shock showed up as a deflator adjustment rather than a real output change. The other common mistake people make is comparing real GDP across countries with very different price levels without using purchasing power parity adjustments. Nominal exchange rates will make an economy look richer or poorer than it actually is in terms of what people can buy locally. I had a colleague who insisted a certain Southeast Asian economy was outperforming based on headline real growth rates, but once you convert to PPP terms the picture reverses completely because the domestic price level is far lower than the exchange rate suggests. If you are working with annual data only, you will miss short-term fluctuations that quarterly estimates capture. The Bureau of Economic Analysis in the United States releases advance, second, and third estimates for quarterly GDP, and each revision can shift the real growth number by a fraction of a percentage point. That sounds small until you are making policy decisions based on whether the economy is expanding or contracting at the margin.
Get the Full Details
A Quick Numerical Example
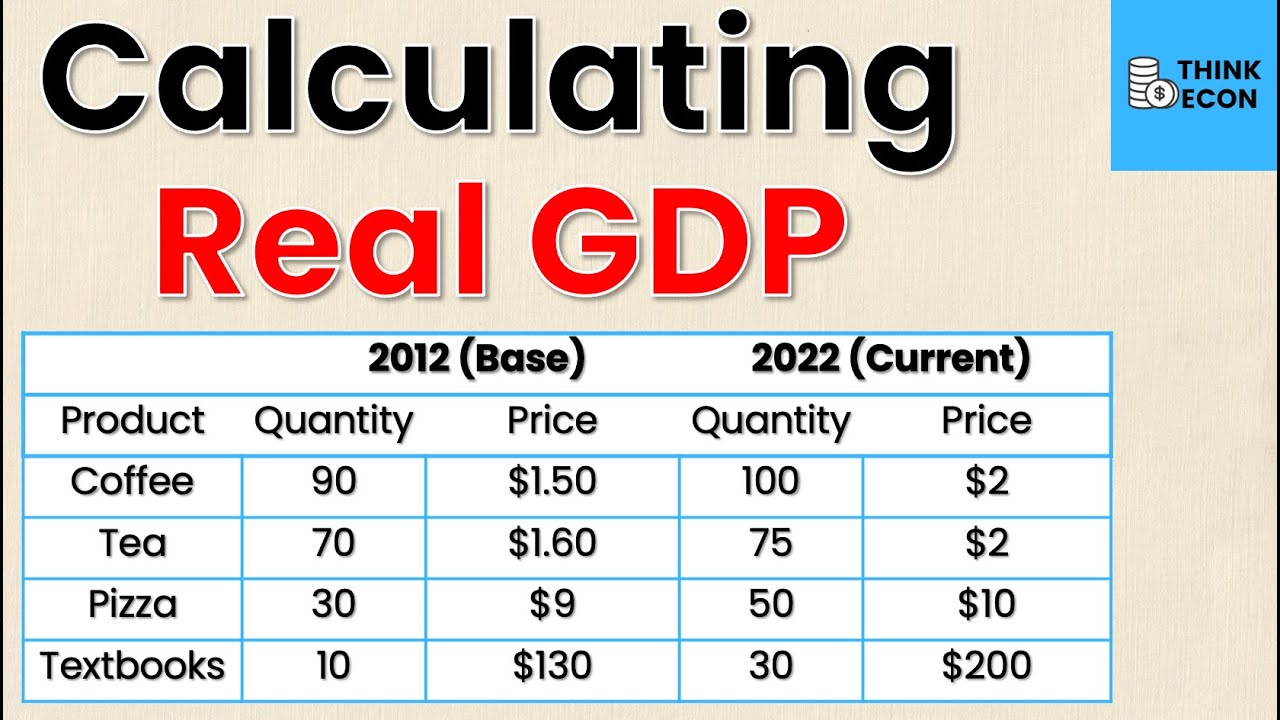
Let me walk through a simple case. Suppose nominal GDP in 2023 is 120 billion and the GDP deflator with base year 2020 equals 110. You divide 120 by 110 and multiply by 100, which gives you approximately 109.1 billion in real 2020 dollars. That means after stripping out price changes, the actual volume of goods and services produced is worth about 109.1 billion compared to the current-price total of 120 billion. If the deflator was 105 in 2022 instead, you would do the same calculation for that year and get roughly 114.3 billion in real terms. The real growth rate between the two years would then be about minus 4.5 percent, which tells you the economy actually shrank in volume terms even though nominal output grew. Without the deflator adjustment, you would completely misread the direction of economic activity.
Alternative Approaches
Some analysts prefer chained dollars instead of fixed-base-year calculations because chained methods update the weights every period and reduce substitution bias. The United States switched to chained 2012 dollars in 2015, and the difference is usually small but systematic over long time horizons. Fixed-base calculations can overstate or understate real growth depending on whether relative prices are changing rapidly. If you are working with very high inflation environments, real GDP adjustments become less meaningful because the base year becomes outdated quickly. Zimbabwe in the late 2000s is an extreme example where monthly price changes exceeded 100 percent, making any annual deflator almost useless for capturing short-term trends. In those cases, analysts sometimes use alternative indicators like electricity consumption or satellite imagery of nighttime lights as proxy measures of real activity. The bottom line is that real GDP is a useful but imperfect tool. Use it carefully, check your methodology, and never assume the number tells the whole story about what is actually happening in an economy.