How Extra Payments Actually Work on Your Mortgage
Most people think throwing extra money at their mortgage is straightforward. It's not. The mechanics depend entirely on how your servicer handles the payment and what instructions you give them. Get it wrong and that extra money just becomes a credit balance sitting there waiting for next month's due date instead of actually reducing your principal faster. When you pay extra on your mortgage, two things can happen depending on how the payment is applied. It either reduces your remaining principal balance immediately, or it gets applied to your upcoming monthly installment as an advance. The difference matters a lot. Principal reduction shortens your loan term and saves you interest. An advance just shifts when a payment is due without saving you anything meaningful. I learned this the hard way back in 2019. I set up an automatic extra payment of $300 per month through my servicer's online portal, thinking I was accelerating payoff. Turns out the system was treating it as a prepayment credit rather than a principal-only supplement. I didn't notice for eight months because my balance looked fine on the statement. The workaround was calling them and requesting a formal "principal only" designation on the extra payment, then getting written confirmation that future overpayments would go directly to principal. They agreed. I also started sending separate checks marked "principal only" instead of relying on the automated system.
The key term here is principal-only payment. Your servicer is legally required to apply any additional amount toward principal unless you explicitly tell them otherwise. But most servicers have confusing interfaces that default to treating everything as a regular payment advance. You have to be intentional about it.
Setting Up Extra Payments Correctly
There are three reliable methods. Pick the one that fits your situation. Method one is the separate check approach. Write a second check each month with the exact extra amount you want to apply. Mail it separately from your regular payment. On the check itself, write "principal only" clearly in the memo line. This eliminates any ambiguity about how the money should be applied. It sounds old-fashioned but it works because there's no automated processing to misinterpret your intent. Method two is using your servicer's portal with explicit instructions. Log in and look for a section labeled something like "extra payments" or "additional principal." Fill in the amount and make sure it specifies principal application. If the portal doesn't give you that option, call them. Ask them directly: will this extra payment be applied to principal or to the next scheduled payment? Write down the representative's name and the date. Follow up with an email confirming the conversation if you can. Method three is making a lump sum payment. This is simpler because you control the timing. Any lump sum sent as a separate transaction should be applied to principal by default. Again, confirm with your servicer first. A single extra payment of a few thousand dollars can knock years off a 30-year mortgage depending on your interest rate and remaining balance.
Get the Full Details

The Math Behind It
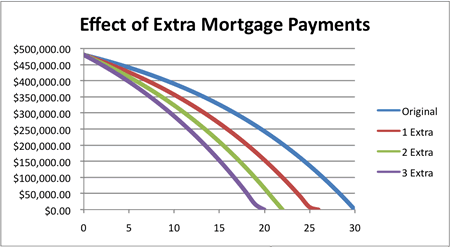
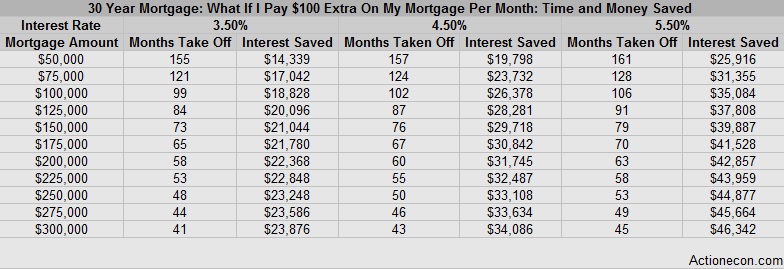
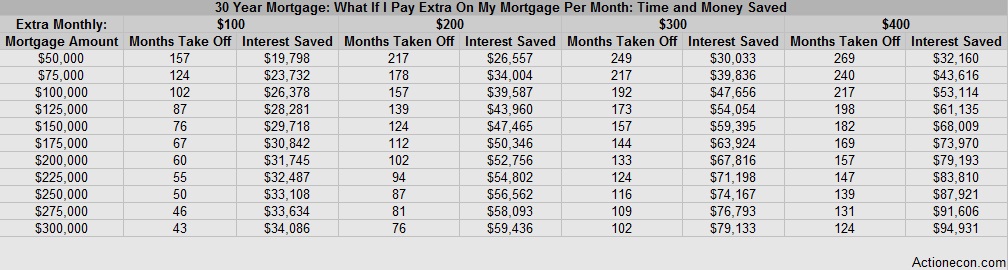
Extra payments reduce the principal, which means less interest accrues each month going forward. This creates a compounding effect. The earlier in the loan term you start, the more you save. On a $300,000 loan at 6.5% interest over 30 years, adding just $200 per month to your payment cuts roughly four years off the term and saves around $47,000 in total interest. That's not a small number. The savings diminish the further along you are in the loan. After year 15, the interest portion of each payment is already small relative to principal. Throwing extra money at the balance at that point saves less overall. This is why timing matters more than most people realize. If you're already past the halfway mark and considering extra payments, the return is decent but not dramatic. You'd likely get better returns putting that same money into other investments.
Pitfalls to Watch For
Your mortgage might have a prepayment penalty clause. It's less common than it used to be, but some loans still include one, especially in certain states or with lender-specific products. Check your closing documents. A prepayment penalty could eat into the savings from extra payments, sometimes for the first three to five years of the loan. Another issue is the acceleration clause. Some mortgages allow the lender to call the full balance due if you miss payments or violate terms. Extra payments won't trigger this, but they also won't protect you if you fall behind on the base payment. Always ensure your regular monthly obligation is covered before sending extras. A servicer can't work with you if you're in default. The biggest mistake I see is people who pay extra but don't verify the application. They assume it's working. It might not be. Request annual statements showing your current principal balance and compare it to what your amortization schedule says it should be. If the numbers don't match, something is wrong. Contact the servicer immediately.
When It Doesn't Make Sense
Extra mortgage payments aren't always the best move. If your mortgage interest rate is below 4%, the math shifts. You'd likely earn more by investing that extra money in a diversified portfolio, even a conservative one. A 6% to 7% average annual return beats a 3.5% interest rate savings over time. The mortgage payment becomes a lower priority. High-interest debt should always come first. Credit cards, personal loans, or any debt above 6% or 7% interest should be cleared before you throw money at a low-rate mortgage. There's no rational reason to carry 18% credit card debt while making extra mortgage payments. Fix the high-interest problem first. Then revisit the mortgage question. Liquidity is another factor. Money tied up in home equity is hard to access quickly. If you're using your emergency fund to make extra payments and something breaks, you're stuck. Keep at least three to six months of expenses in liquid savings before accelerating mortgage payoff. An illiquid house won't help you when the water heater fails.
If I Pay Extra On My Mortgage and Want to Recast Instead
Sometimes a one-time large payment followed by a recast makes more sense than monthly extras. A recast means you make a significant lump sum payment, the servicer recalculates your monthly payment based on the new lower balance, and you keep the same loan term and interest rate. The monthly payment drops, which improves cash flow without changing the loan structure. Not all servicers offer recasting. Those that do typically charge a fee between $75 and $300. The minimum lump sum required varies by lender, usually somewhere between $5,000 and $10,000. This option works well if you receive an inheritance, a bonus, or proceeds from selling another property. It's also useful if your cash flow is irregular and you want the security of a lower required payment after a big lump sum.
Verification Steps
After you start making extra payments, verify they're working. Request a payoff quote from your servicer every year. Compare it to your expected payoff based on your amortization schedule. Also ask for a re-amortization schedule that reflects the extra payments you've made. This should show your updated balance and remaining term. If they can't provide it, that's a red flag about their tracking systems. Keep records of every extra payment. Copies of checks, transaction confirmations, emails with representatives, and written responses. Servicers change. Your account might get transferred to a new company. Documentation helps you prove payments were made and applied correctly when you need it most.