Comparing Two Interest Rates Is Trivial; Comparing The Full Financial Impact Is Where People Mess Up
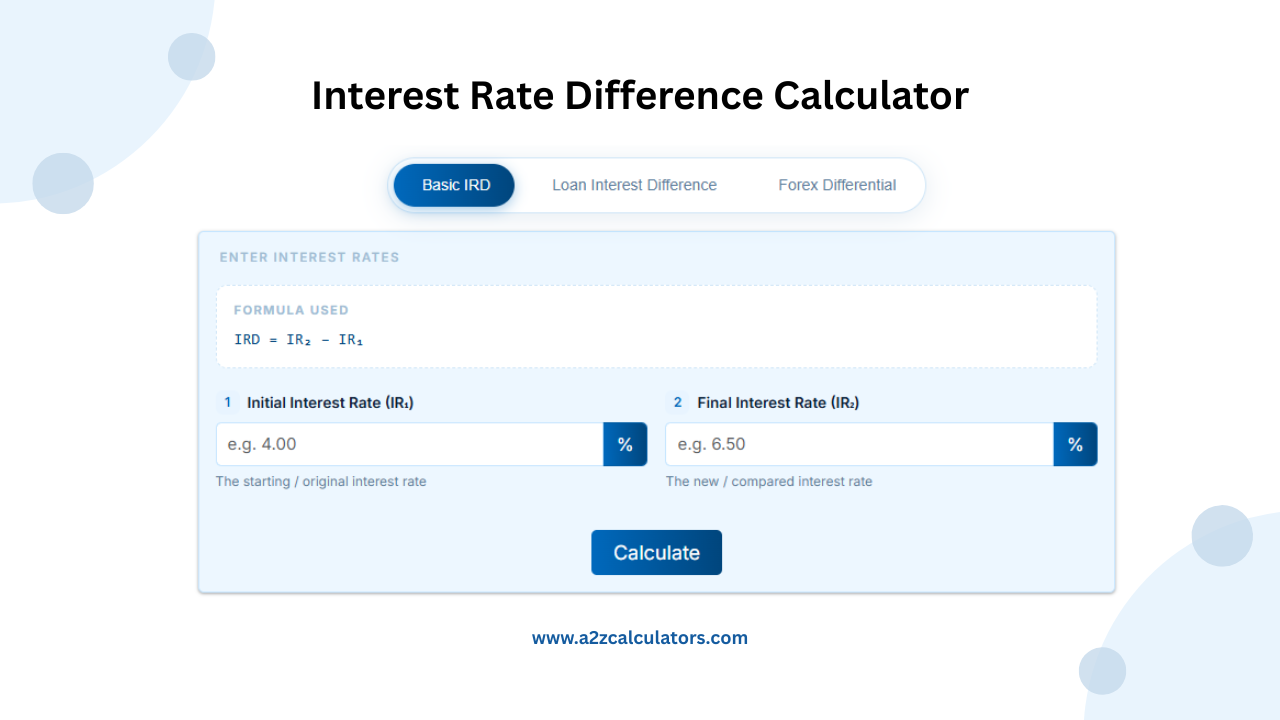
You've got two loan offers. One has a 4.2% rate and the other 5.1%. The second one costs you more, obviously. But how much more, and over what timeframe does it actually matter? That's where an Interest Difference Calculator comes in handy. It takes two separate interest scenarios and spits out the gap between them, usually in dollar terms, sometimes in percentage points depending on what you're comparing. I use this kind of tool when I'm doing quick feasibility checks for clients who are torn between two refinancing options. The spreadsheets get messy fast when you're juggling different compounding periods, payment frequencies, and balloon payments. A calculator that handles the raw difference removes a lot of the manual error that creeps in during manual line-by-line comparisons.
Interest Difference Calculator: How To Use It Properly
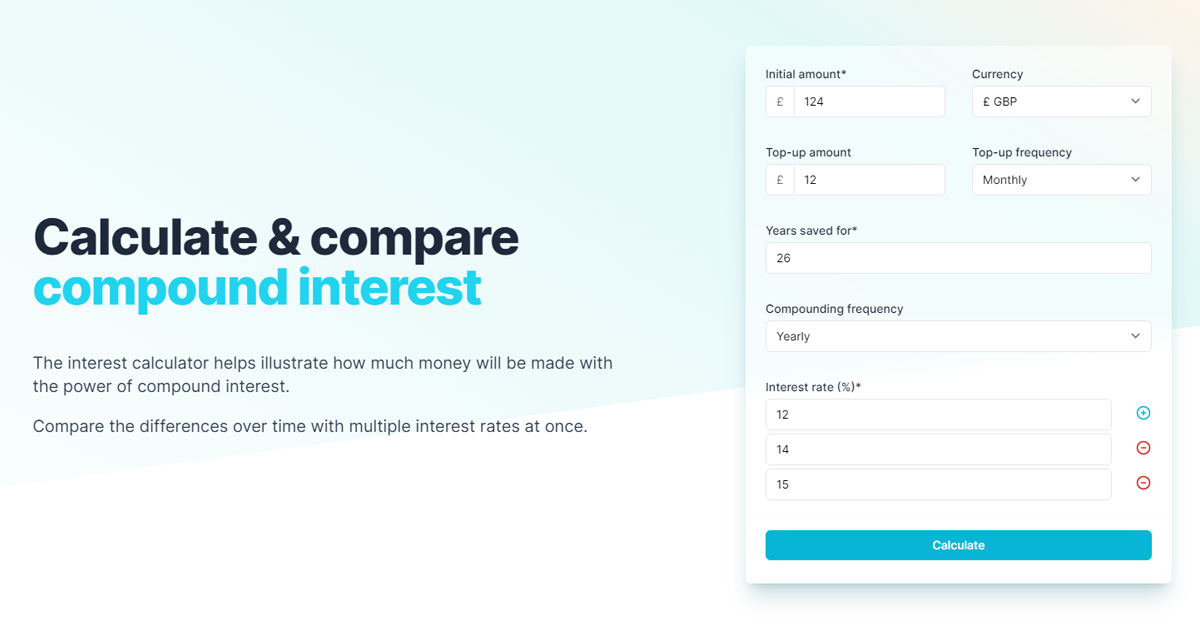
Most calculators in this space work the same way. You enter the principal amount, the first interest rate, the second interest rate, the compounding frequency for each, and the time period. The tool then runs both scenarios through the standard compound interest formula and subtracts one total from the other. What comes out is the cost difference, or the savings, depending on which scenario is more favorable. Here's the part that matters and nobody really explains clearly. The compounding frequency is where things fall apart for most people. If Loan A compounds monthly and Loan B compounds daily, you can't just plug in the nominal rates and call it a day. The effective annual rate differs even if the nominal rates look close. I had a client last year who was comparing a mortgage at 4.5% monthly compounded against a home equity line at 4.4% daily compounded. On the surface, the HELOC looked cheaper. When I ran the actual effective rates, the mortgage came out roughly 0.08% lower annually. That detail shifted the entire decision. So here's what you actually do. Make sure both inputs use the same compounding basis before you trust the output. If the calculator lets you choose compounding frequency per loan, set both to the same thing first, run the comparison, and then run it again with the real compounding schedules. The difference between those two results tells you how much the compounding structure itself is adding or subtracting from your bottom line.
For the actual calculation behind it, the formula is straightforward. You're looking at the future value of each scenario. Future value equals principal times one plus the periodic rate, raised to the power of the total number of compounding periods. Subtract one future value from the other and you have your interest difference. It's not complicated math. The complexity lives in making sure every variable is entered correctly. I ran into another edge case recently that still bugs me. Someone sent me a comparison between a fixed-rate loan and an adjustable-rate loan using an average projected rate for the ARM. The calculator spit out a clean number. The problem is that average rates ignore the cap structure, the adjustment windows, and the fact that the ARM could hit its lifetime maximum well before the term ends. When I pulled the actual amortization schedules from the lenders and compared month by month, the difference was nearly triple what the calculator had shown. Calculators like this assume static rates. They don't model rate movement. If you're comparing a fixed against an ARM, do not trust a simple interest difference output. Run a full cash flow projection instead, month by month, with the actual rate adjustment schedule from the lender. Another common mistake I see is comparing different loan amounts as if the rate difference is the only variable. Say you're looking at a $300,000 loan at 5% versus a $280,000 loan at 4.5%. The calculator will show you the interest gap between those two scenarios, but that gap mixes together the effect of a different principal and a different rate. You can't tell from that single number which factor is driving the difference. Isolate the variables. Run the same principal at both rates first. Then run the same rate at both principals. Only then do you understand what's actually happening.
Get the Full Details
What These Calculators Miss Completely
They ignore fees. Points, origination charges, closing costs, prepayment penalties, late payment structures. All of that exists outside the interest rate itself and it changes the real cost picture significantly. A loan with a slightly higher rate but zero points can end up cheaper overall than a lower-rate loan loaded with upfront fees. The calculator won't tell you that. You have to add those numbers in separately. They also don't account for tax implications. Interest on certain loans is tax deductible. The after-tax cost of a 5% mortgage might be materially different from the after-tax cost of a 4.8% loan depending on your bracket and whether the debt qualifies. Again, that's outside the calculator's scope. And there's the inflation question. Money today is worth more than money tomorrow. A dollar saved in interest five years from now isn't the same as a dollar saved today. If you're comparing long-term scenarios, discounting the future difference back to present value gives you a more honest picture of what the gap actually means to you right now.
When To Use This And When To Walk Away
Use an Interest Difference Calculator when you're comparing two loans with the same principal, same term, same fee structure, and both are fixed-rate products. That's the sweet spot. It's fast, it's accurate enough for a first-pass comparison, and it saves you from doing twelve rows of spreadsheet math by hand. Walk away from the calculator when any of those conditions aren't met. Different principals, different terms, mixed fixed and variable rates, significant fee disparities, or tax considerations that matter for your situation. In those cases, build a full amortization schedule or use a loan comparison tool that ingests all the variables at once. The 15 minutes you save with a simple calculator aren't worth a decision that's off by a few thousand dollars because you missed something in the fine print. I keep a basic calculator bookmarked for quick checks, but my default workflow is still to export the actual amortization schedules from the lenders and compare them side by side. The calculator is a shortcut. The schedules are the truth. Both have their place, but don't confuse the shortcut for the destination.