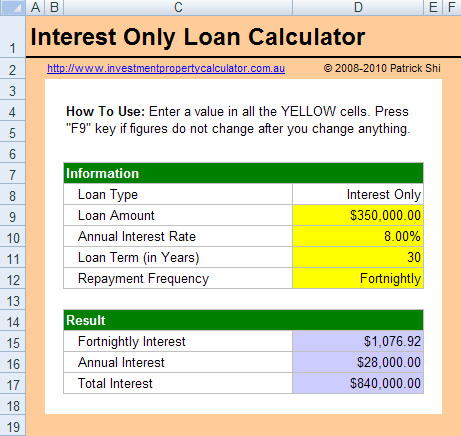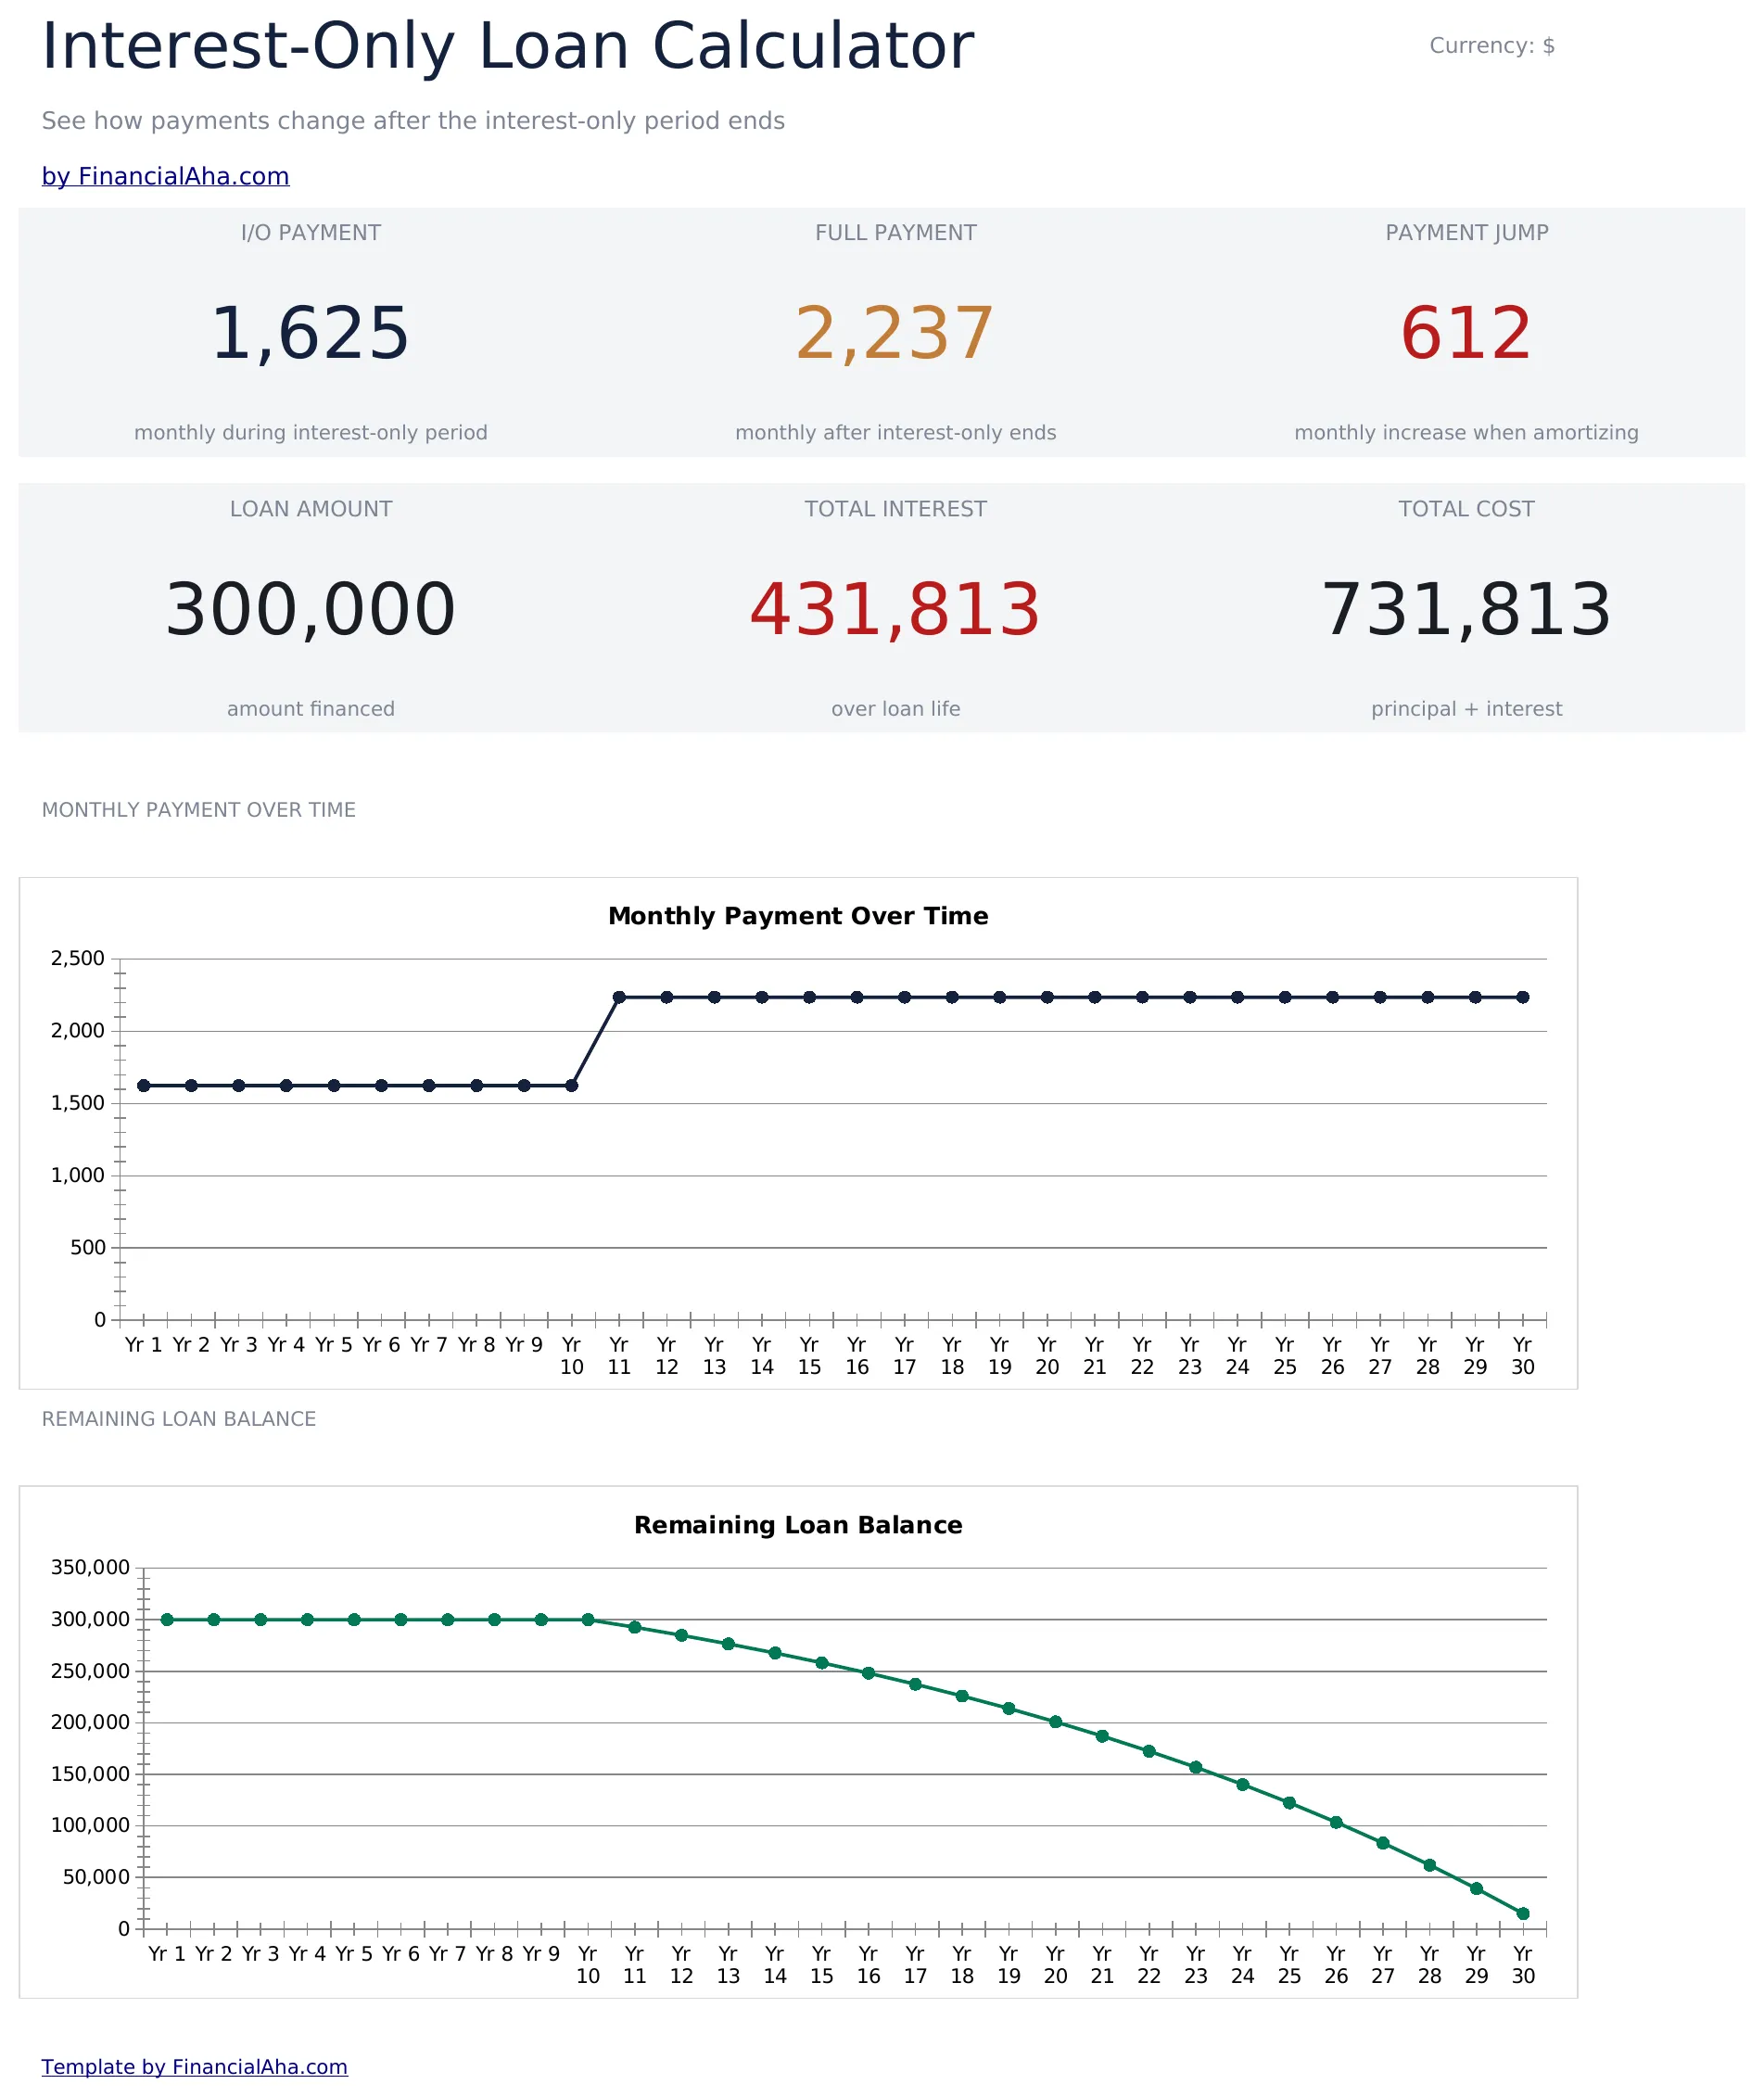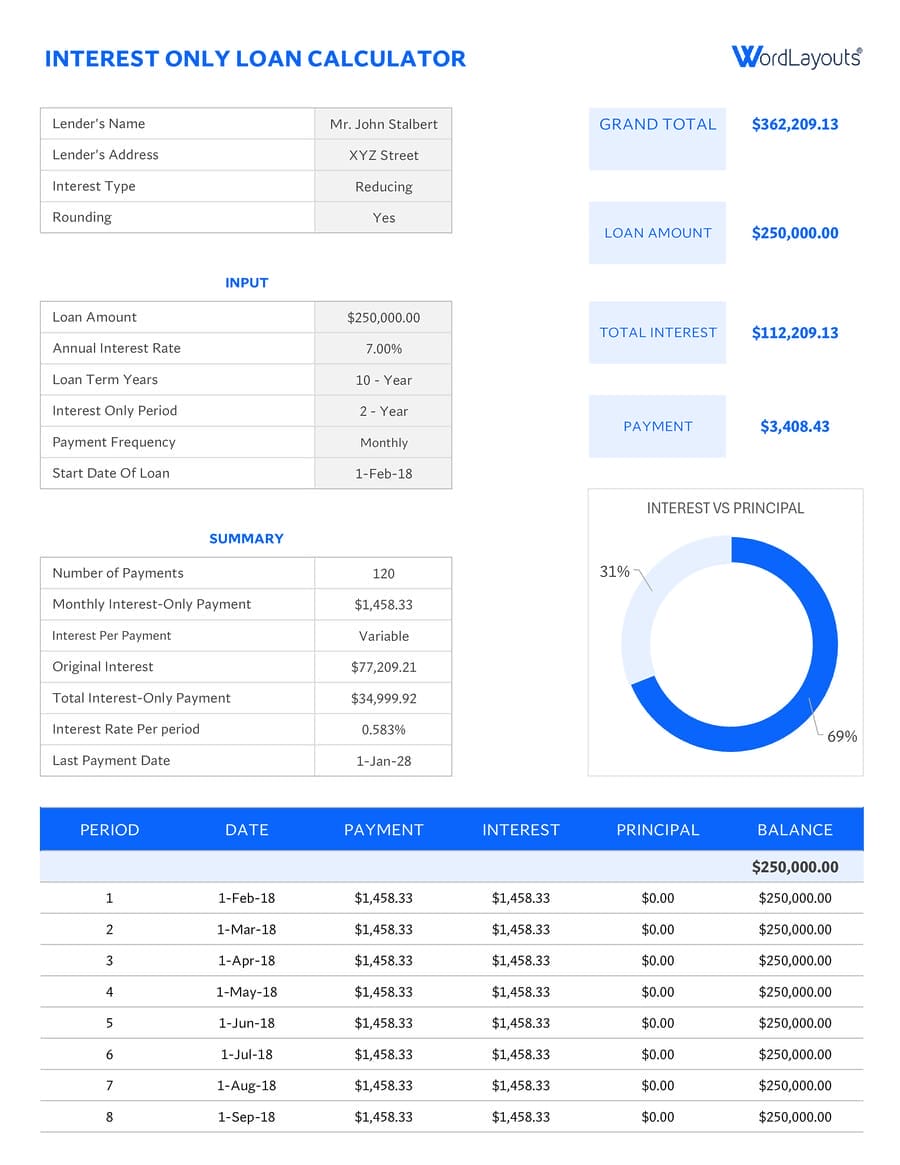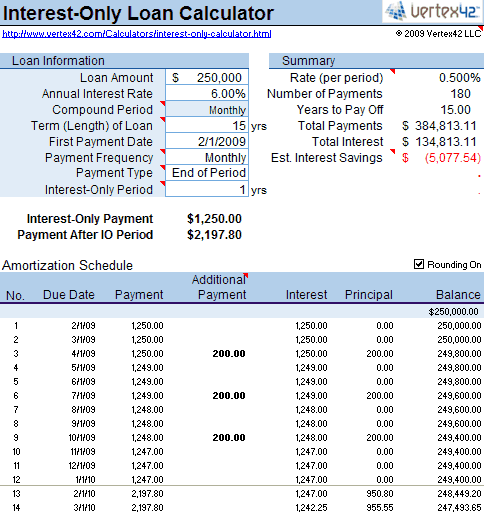
How an Interest Only Calculator Loan Actually Works in Practice
Most people treat an Interest Only Calculator Loan tool as something that just spits out a monthly payment number and calls it a day. It's more complicated than that, and the gap between what the calculator shows and what actually hits your bank account is where most borrowers get stuck. I'm going to walk through the mechanics, the gotchas, and a specific problem I ran into when working with these calculators on a client's file last year.An interest-only loan is straightforward in theory: you pay only the accrued interest for a set period, usually 5 to 10 years, and then the repayment phase kicks in. The principal balance doesn't decrease during that window. What people forget is that after the interest-only period ends, your payment can easily double or triple because you're suddenly amortizing the full balance over the remaining term. Let me break down how the calculation actually works before we get into the edge cases.
How to Use an Interest Only Calculator Loan Tool Correctly
The basic math is simple enough. Take your loan amount, divide by 12 to get the monthly principal, then multiply by your annual interest rate divided by 100. That gives you the monthly interest charge, which is your payment for the interest-only period. Most online calculators do this in about three seconds, but the inputs matter more than you'd think. Here's a concrete example. Say you have a $400,000 loan at 6.5% annual interest. Your monthly interest-only payment is $400,000 multiplied by 0.065, divided by 12, which equals $2,166.67. The calculator will show you that number and stop there. But it won't tell you that once your interest-only period expires after say seven years, your payment jumps to roughly $4,394 per month if you're still on a 30-year amortization schedule. That jump is the part people don't plan for. When you're using an Interest Only Calculator Loan tool, make sure it lets you adjust the interest-only period length, the amortization term, and the balloon payment date. A calculator that only gives you the monthly IO payment is basically useless for real decision-making.
The tools that actually work well also let you toggle between fixed and adjustable rates, factor in property tax and insurance if you want an escrow estimate, and show you a year-by-year payoff schedule. Without those features, you're just seeing the tip of the iceberg.
Get the Full Details

The Problem Nobody Warns You About
I had a client recently who was looking at a $625,000 interest-only loan on a refinanced investment property. The calculator showed a monthly payment of $3,125 at 6%. She was comfortable with that number. What the standard calculator didn't surface immediately was the amortization cliff. After the 7-year IO period, her payment wasn't going to $4,000 or even $4,500. It was going to $5,847 because the loan was structured on a 25-year amortization schedule, not the typical 30 years most people assume. The workaround was to dig into the actual loan documents and pull the exact amortization term from the promissory note, not just trust the standard calculator defaults. Most free calculators assume 30-year amortization by default. When your actual loan has a different term, your post-IO payment is completely different from what the calculator predicted. I built a quick spreadsheet that cross-referenced the IO period, the actual amortization term, and the remaining balance to project the exact payment at year 8. It took about 20 minutes but saved her from signing a loan she couldn't afford past year 7. Another issue I see constantly is negative amortization creep. Some interest-only loans allow you to pay less than the full accrued interest, and the unpaid interest gets added to the principal. The calculator won't show this unless you explicitly select that option. If your loan has a payment cap or partial payment feature, the numbers change drastically. I've seen clients who thought they were paying down interest but were actually watching their balance grow by 2 to 4 percent annually during the IO period without realizing it.
What the Calculators Get Wrong Most of the Time
First, they rarely account for the rate reset on adjustable interest-only loans. A 5/1 ARM might show you a beautiful 5.25% payment for the first five years, but the calculator often keeps that rate locked in for the entire display period. In reality, after year 5, your rate could reset to whatever the index is plus the margin, which is often 2 to 3 percentage points higher depending on the market. Second, most calculators ignore the fact that property taxes and insurance often scale with the property value, which may have appreciated during your IO period. Your total housing payment isn't just principal and interest. If you're using this for an investment property, vacancy and maintenance costs also factor in, and the calculator doesn't touch those. A realistic payment estimate should include those line items, even approximately. Third, the tax implications are missing from every single free calculator I've seen. Interest on investment property loans is generally deductible, but the rules changed after the 2017 tax reform. The deduction is capped at $750,000 of acquisition debt for most borrowers now. If your interest-only loan is above that threshold, your actual after-tax cost is significantly higher than what the payment number suggests. I always run the post-calculation through a quick tax adjustment myself before presenting numbers to a client.
When an Interest Only Calculator Loan Tool Actually Helps
These tools are genuinely useful when you're comparing multiple loan scenarios side by side, especially if you're weighing an interest-only structure against a fully amortizing one. Plugging both into the same calculator and looking at the total interest paid over the life of the loan gives you a clear picture of the trade-off. You'll usually find that the IO loan saves you several thousand dollars per month during the early years but costs you noticeably more in total interest if you hold it to completion. They're also valuable for understanding cash flow on rental properties. If you're analyzing whether an investment property covers its own expenses during the interest-only window, the calculator gives you the baseline number you need. Subtract that from your projected rental income and you immediately know if the deal works month to month. It's a quick filter that saves you from diving deeper into a property that doesn't pencil out. For buyers who plan to sell before the IO period ends, the calculator is essentially a proof of concept. You're not concerned with the payment at year 8 because you won't be holding the loan that long. The tool tells you exactly what your carrying cost will be during ownership, which is all you really need to make the decision.

The Honest Downsides
Interest-only loans carry real risk, and no calculator can measure that for you. The biggest danger is the payment shock at the end of the IO period. If your income hasn't increased and your property hasn't appreciated, you could be stuck with a payment you can't sustain. I've seen this play out more times than I care to count, usually with borrowers who priced the loan based on the lowest possible monthly payment and never stress-tested the post-IO scenario. Another downside is that some lenders charge slightly higher rates for interest-only products compared to fully amortizing loans. The rate premium is usually 0.125 to 0.375 percent, and while that seems small, it compounds across the entire balance. A calculator that doesn't let you compare rates side by side won't reveal this cost to you. Finally, these loans aren't available everywhere or for every borrower. Conventional loans with IO terms are mostly aimed at investment properties or jumbo loans. If you're a first-time homebuyer looking at a standard purchase, your options are much more limited. An online calculator might show you a product that simply doesn't exist in your market or at your credit tier.
If you're looking at a traditional primary residence purchase and want payment predictability, a standard 30-year fixed mortgage calculator is going to serve you better. The interest-only structure makes sense for specific situations, but it's not a universal solution.