How IRS strategies actually work in a live book
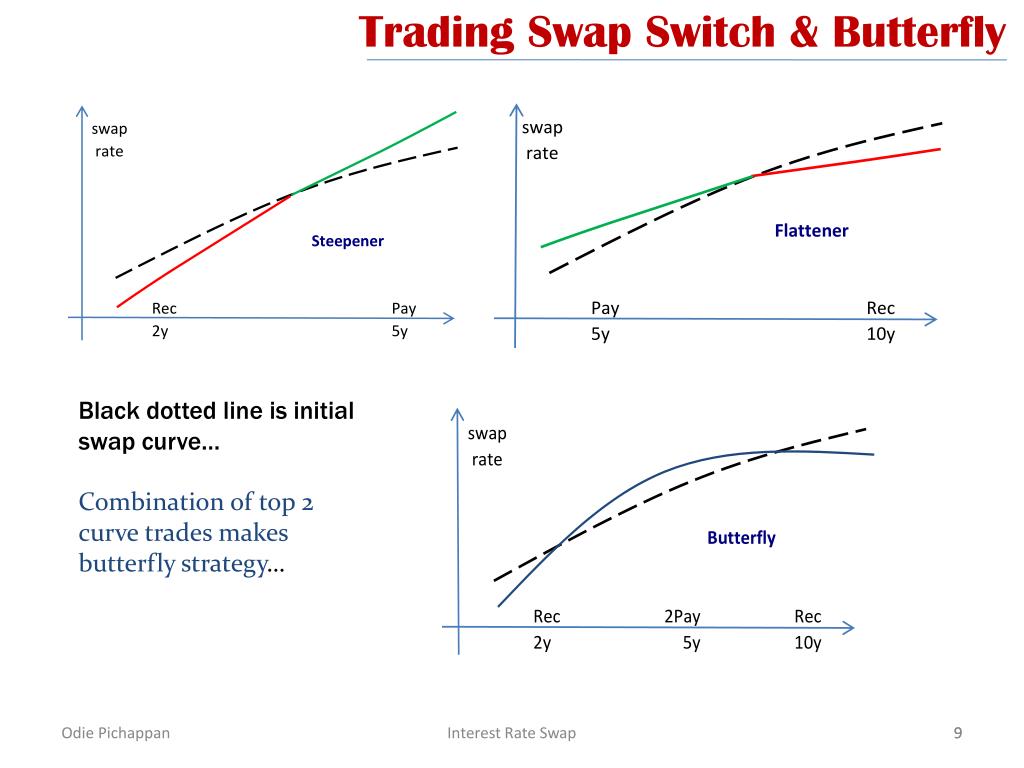
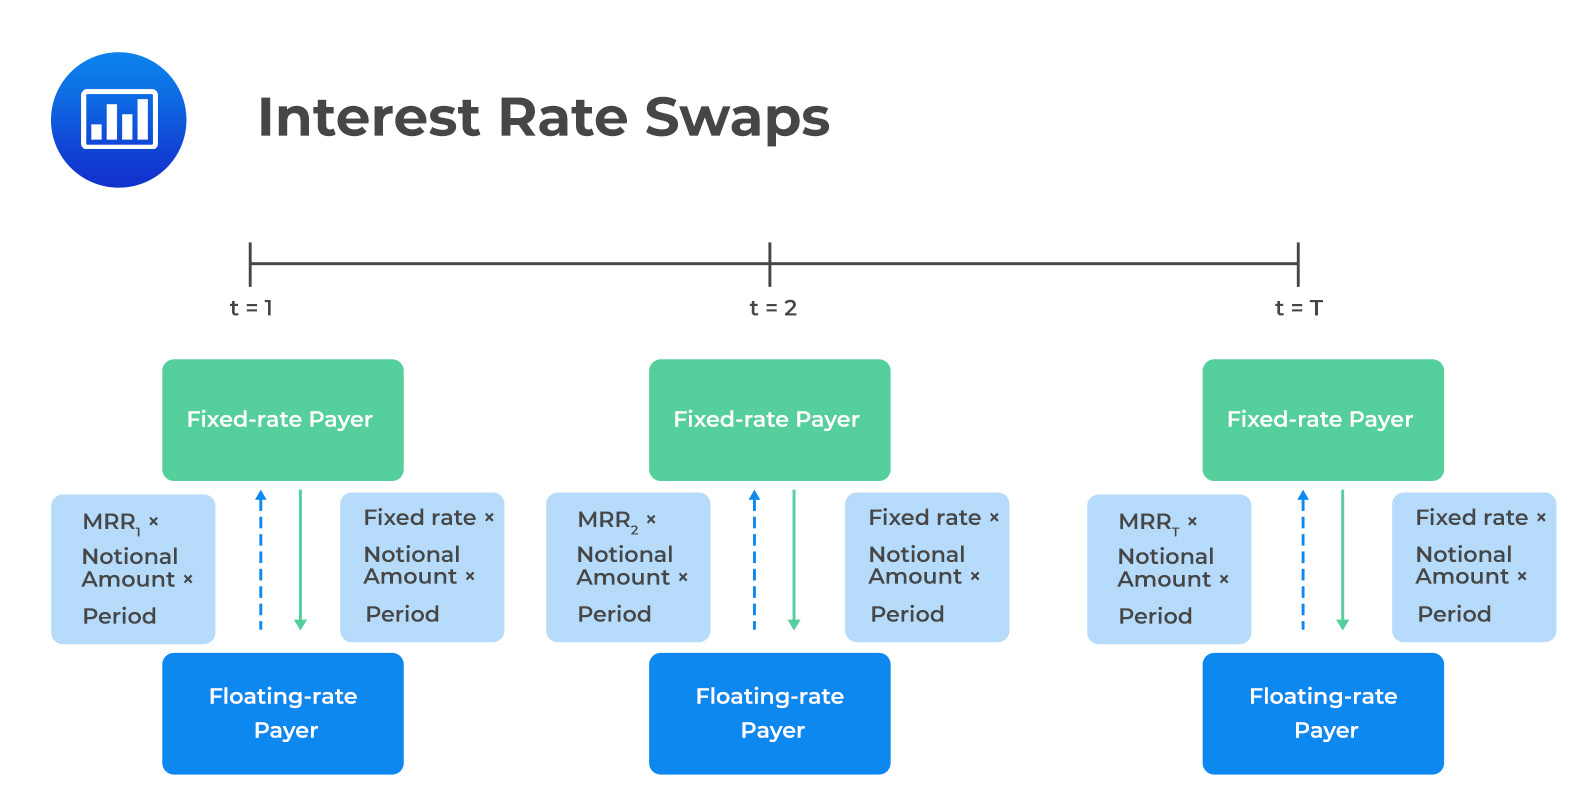
I've been building and unwinding interest rate swap positions for about eight years across a handful of desks, and the thing nobody tells you going into this space is that the payoff isn't in finding some exotic structure. The money is in execution, in the spread between what your model says and what the market actually gives you, and in knowing when not to trade. Most people come at this from the textbook side and they miss the friction. Here's what it looks like from the front. At the simplest level, you're trading the difference between a fixed rate and a floating reference rate over some defined tenor. The standard vanilla IRS pays a fixed leg against a floating leg tied to something like SOFR or EURIBOR. You enter one side as payer or receiver, and your P&L moves with the curve. But that's the product definition, not the strategy. Strategies are about combining multiple swaps with different tenors, vintages, or payment structures to express a view or hedge something else. The strategy part is where most people get sloppy. The most common starting point is a butterfly trade. You're long the 2-year and 10-year while short the 5-year, or vice versa, depending on whether you think the belly is going to steepen or flatten relative to the wings. This isn't theoretical. I ran a simple 2s5s10s butterfly in the second half of 2023 when the front end was pricing in aggressive cuts and the back end was largely unchanged. The trade worked for about six weeks, then the Fed pivot signal made the curve move in the opposite direction and I had to cut it. The insight most beginners miss here is that butterflies aren't pure curve plays. They carry roll risk, they carry funding cost differences across tenors, and the correlation between short and long rates changes depending on where you are in the cycle. In a tight liquidity environment, the 5-year leg can move disproportionately because there are fewer market makers willing to quote across all three tenors simultaneously.
Steepeners and flatteners are the next layer. A steepener is typically long longer-dated and short shorter-dated floats, or equivalently, receiver on the short end and payer on the long end. A flattener does the opposite. These sound straightforward but they're not. When you execute a steepener using swaps, you're often trading into a market where the 2-year is heavily bid by duration hedgers and the 10-year is being absorbed by liability-driven investors. The spread you see on your screen is not the spread you get after you factor in the cost of funding the position. I once ran a 2s30s steepener where the quoted spread looked attractive at 25 basis points, but once I accounted for the repo cost differential between the two tenors and the collateral optimization overhead, the real economic value was closer to 8 basis points. The trade still made sense, just barely. Writing it off as a great deal would have been a mistake. Another strategy that comes up constantly is the swap spread trade. This is a relative value play between the swap rate and the equivalent-maturity government bond yield. Swap spreads widen when there's credit concern among dealers or when there's demand pressure on Treasury issuance, and they compress when funding is abundant. The counterintuitive thing about swap spreads is that they don't always move with credit risk in the way you'd expect. During the QT cycle in 2022, swap spreads actually tightened even though funding stress was visible, because banks were actively selling Treasuries from their balance sheets to meet liquidity requirements. The swap spread narrowed precisely when the market should have been pricing in more dealer risk. If you were trading that based on a simple credit framework, you would have been on the wrong side of the move. For people who want to be more tactical, basis trades within the swap market itself are where the grind happens. The most common version is the OIS-vs-libor basis trade, which has evolved since the transition from LIBOR to alternative reference rates. With SOFR now the dominant benchmark, the basis trade is less of a standalone alpha generator than it used to be, but it still exists in the form of term-SOFR versus overnight-SOFR basis products and cross-currency basis flows. I had a specific problem last year where a client wanted to express a view on the term premium using a standard 5-year fixed-for-floating swap, but the desk's risk system was flagging the trade as exceeding our VaR limit because the model was double-counting correlation with existing Treasury positions. The workaround was to net the Treasury hedge first, recalculate the incremental risk, and then execute the swap as a pure basis overlay rather than a standalone position. It added about 45 minutes to the process but kept the trade within limits. Without that adjustment, we would have had to shrink the position size by roughly 60 percent.
What most people get wrong about execution
There's a gap between how these strategies are taught and how they actually behave. A textbook will tell you that if you expect the curve to steepen, you buy a steepener. It won't tell you that your trade has a natural convexity profile that changes as rates move, or that your stop-loss levels will get hit faster during high-volatility periods because liquidity evaporates on both sides of the trade at the same time. I learned this the hard way during the March 2020 spike. We had a set of steepener positions that looked fine on paper with normal historical correlations. When the shock hit, the 2-year moved 80 basis points in a single day and the 10-year moved 40. The trade didn't behave like a linear combination of two rates. It behaved like something much more painful because the short end is inherently more volatile and the positions were sized assuming a stable volatility ratio. Credit valuation adjustment is another area where beginners consistently underprice the risk. When you're trading swaps with non-tier-one counterparties, the CVA can eat into your expected profit significantly, especially on longer-dated trades. A 10-year swap with a mid-tier bank counterparty can have a CVA charge that's 3 to 5 basis points per year, depending on the credit rating and the collateral agreement. Over the life of the trade, that adds up. The practical fix is to negotiate CSA terms that include a threshold and clearing arrangements where possible, and to price CVA into your mark-to-market from day one rather than treating it as an afterthought. The funding component deserves its own section because it's where most retail and even some institutional traders lose money without realizing it. An interest rate swap is not a free leveraged position. If you're paying fixed and receiving floating, you need to fund the upfront collateral movements. The cost of that funding varies by counterparty, by jurisdiction, and by your own credit profile. A well-capitalized bank can fund at near-OIS rates. A smaller fund or a non-bank entity might be paying 20 to 40 basis points more on the funding side. That spread is the difference between a profitable trade and a breakeven one, or between a breakeven trade and a losing one. I've seen traders run backtests that showed strong returns, then get destroyed in live trading because the backtest assumed free funding.
Get the Full Details

Practical sizing and risk management
Position sizing in IRS strategies should be driven by P&L volatility targets, not by notional size. A $100 million notional 2s10s butterfly and a $500 million notional butterfly carry very different risks depending on where the curve is and what the volatility environment looks like. The standard approach is to calculate the DV01 of each leg, combine them using the correlation matrix for the relevant tenors, and then size the position so that the portfolio-wide DV01 doesn't exceed your daily P&L limit by more than a predetermined factor. I typically use a factor of 2 to 3 times the daily VaR, which means a position that could lose two to three times my normal daily limit in a single adverse move. It feels uncomfortable at first, but it's far better than sizing by notional and getting surprised. Hedge ratio recalibration is something you need to do more frequently than most people expect. The correlation between 2-year and 10-year swap rates is not constant. It ranges from about 0.7 to 0.95 depending on the macro environment, and it drops toward the lower end during regime shifts. If you're running a static hedge ratio based on a one-year lookback, you will be wrong about half the time. I use a rolling 90-day correlation with an exponential weighted moving average that gives more weight to recent observations. This adjusts the hedge ratio faster without being as noisy as a pure short-window calculation. The trade-off is that you'll adjust more frequently during normal periods, but you'll react quicker when the regime actually changes. One thing I want to be direct about: these strategies are not perfect. They have real limitations. Steepeners and flatteners can lose money in both directions if the curve moves in ways you didn't anticipate, especially if the move is driven by a liquidity event rather than a fundamental shift in rates expectations. Butterfly trades are sensitive to the exact shape of the curve between the tenors you're trading, and if there's a kink or a discontinuity at the tenor you're short, the trade can underperform even if the wings move as expected. Swap spread trades are exposed to central bank balance sheet dynamics that are difficult to model and harder to trade around. The basis trade, once a reliable source of alpha, has become much harder to execute profitably as major central banks have reformed the reference rate landscape.
If you're just getting started, the best approach is to begin with a single straight vanilla swap position and get comfortable with the mechanics, the collateral requirements, and the P&L attribution before layering on complexity. Try a small payer or receiver position with a 5-year tenor, monitor it for a few weeks, and understand exactly where your P&L is coming from each day. Then move to a simple steepener or flattener using two tenors. Only after you have that foundation should you attempt multi-leg structures. The market will reward patience here, and it will punish haste very quickly. There's no download link or software shortcut that replaces understanding how these instruments actually settle and how your positions interact with the broader market. What helps is building a simple spreadsheet or Python script that tracks the DV01, the implied funding cost, the CVA charge, and the roll-down contribution for each leg of your trade separately. When you can see each component's contribution to daily P&L, you'll understand what's driving your returns and what's just noise. Most traders skip this step and then spend months trying to figure out why a trade that looked good on paper didn't perform as expected. The answer is usually sitting in one of those components, and it's almost never the direction of the rate move itself.