How This Textbook Actually Works in Practice
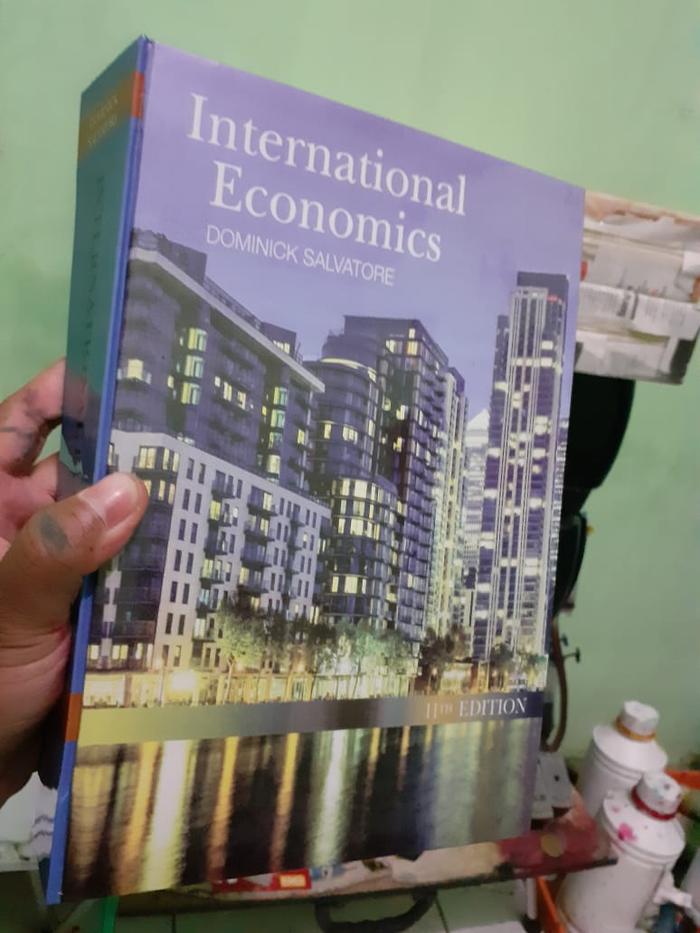
Most people pick up International Economics 11th Edition expecting a straightforward reference. It isn't one. The book is split into two massive parts—international trade and international finance—and each part operates almost like a completely different discipline. Trade uses graphs with supply curves and tariff wedges. Finance throws in interest rate parity, exchange rate regimes, and policy trilemmas. Switching between them mid-semester is where students lose points, not because the material is hard, but because the mental framework shifts. The trade section builds from the Ricardian model through Heckscher-Ohlin, then moves to trade policy instruments. The finance section starts with balance of payments accounting, which is tedious but non-negotiable—you need to actually understand how the current account, capital account, and financial account sum to zero before anything else makes sense. I spent an entire chapter fighting with BOP decomposition problems until I stopped memorizing and started drawing the T-accounts. Once that clicked, the monetary approach to exchange rates became manageable. The policy analysis chapters are where the book gets useful. When you understand the Armington model and terms-of-trade arguments, tariffs stop being abstract. I was consulting on a trade policy brief once and realized the entire debate over agricultural safeguards came down to whether the importing country was large enough to improve its terms of trade through a tariff. The textbook had the framework for it in Chapter 9. Most people skim past that section.
What the Book Gets Right and Where It Fails
The empirical work in this edition is solid. The data tables at the end of most chapters are real, and the exercises use actual trade flows rather than contrived numbers. That matters when you're trying to build intuition for how gravity models work. The trade section's treatment of intra-industry trade and new trade theory is also better than most competitors. Krugman's own work is woven in naturally, not as a name-drop. Here's what doesn't work. The coverage of emerging market finance is thin. When you look at currency crises in practice, the textbook framework—Mundell-Fleming with fixed exchange rates—feels like it's describing 1990s economics. It doesn't handle sovereign debt dynamics, capital control frameworks, or the role of foreign-currency-denominated debt in a meaningful way. If you're studying Latin American or Southeast Asian finance post-2008, you need supplemental readings. The book's treatment of the policy trilemma is correct but incomplete. Real central banks navigate around it in ways the model doesn't capture. The exchange rate determination chapters assume rational expectations in a way that doesn't match how markets actually operate. When the Fed signals a pivot, the yen doesn't move according to uncovered interest parity. It moves on positioning, flow-driven order books, and dealer inventory constraints. The textbook will teach you the theoretical benchmark. It won't prepare you for the gap between that benchmark and observed behavior. You can bridge that gap with reading BIS working papers, but that's not in the assignment.
Using the Problem Sets Effectively
The end-of-chapter problems range from straightforward algebra to moderately challenging derivations. The trick is to do the derivations by hand first. I've seen students copy solutions from the manual and think they understand IS-LM with floating rates. They don't. Working through the algebra yourself—getting the slope of the BP curve wrong, then correcting it—takes longer upfront but saves hours during exam review. The derivation of the Marshall-Lerner condition from first principles, for example, takes about ten minutes if you already know the elasticity approach. It takes forty-five minutes the first time you do it from scratch. Do it the long way once. It locks in. There's a specific problem type in the trade section involving optimal tariffs in a two-country model that trips people up repeatedly. The solution requires setting up the foreign export supply curve correctly. Most students draw it as perfectly elastic, which only works for a small country. The optimal tariff result vanishes if you make that mistake. I caught this repeatedly when I was TA-ing. The workaround is simple: check whether the problem gives you a world relative price or asks you to solve for equilibrium. If it asks you to solve for equilibrium, the country is large, and you need the downward-sloping export supply curve.
Get the Full Details
How Long This Actually Takes
Reading one chapter covering the new trade model and policy implications takes about four to six hours if you're doing the problems. Without problems, maybe two. The finance chapters run longer because the math is denser. Expect six to eight hours per chapter if you're serious about the material. This isn't a book you read passively on the commute. It's a workbook dressed as a textbook. The difference matters for scheduling. If you're using this alongside a course, the chapter on currency crises is worth double-reading. The first pass covers the model. The second pass, done after watching a couple of case studies on the 1997 Asian crisis or the 2001 Argentine default, connects the theory to something resembling reality. The book doesn't do this connection for you. You have to make it.
Where to Get It
The publisher is Pearson. You can find it on their website, on Amazon, at campus bookstores, or through your university library. The international student edition exists and is significantly cheaper, but the page numbers for problems differ from the standard edition, which causes confusion when cross-referencing solution manuals. If you can afford the standard edition, it's worth it. The binding is better too, which sounds trivial until you're opening it to page 400 and it falls flat on its own. There's also a separate Student Study Guide available that walks through selected problems. It's helpful for the early trade chapters but less useful for the finance sections, which move faster than the guide can accommodate. I used it for Chapters 2 through 6 and skipped ahead after that.
Bottom Line
This is a thorough book. It's not elegant, and it doesn't pretend to cover everything that happens in the real world. The trade portion is stronger than the finance portion, which is unusual for a combined text. If your program focuses on development finance or emerging markets, plan to supplement. If you're doing trade policy or standard macro-level international finance, this covers the core competencies. The exercises are the part that actually teaches you anything. Reading the chapters without doing the problems is like looking at someone else doing weightlifting. You'll recognize the movements. You won't have built the muscle.