What Chapter 5 Actually Covers (and Why It Trips People Up)
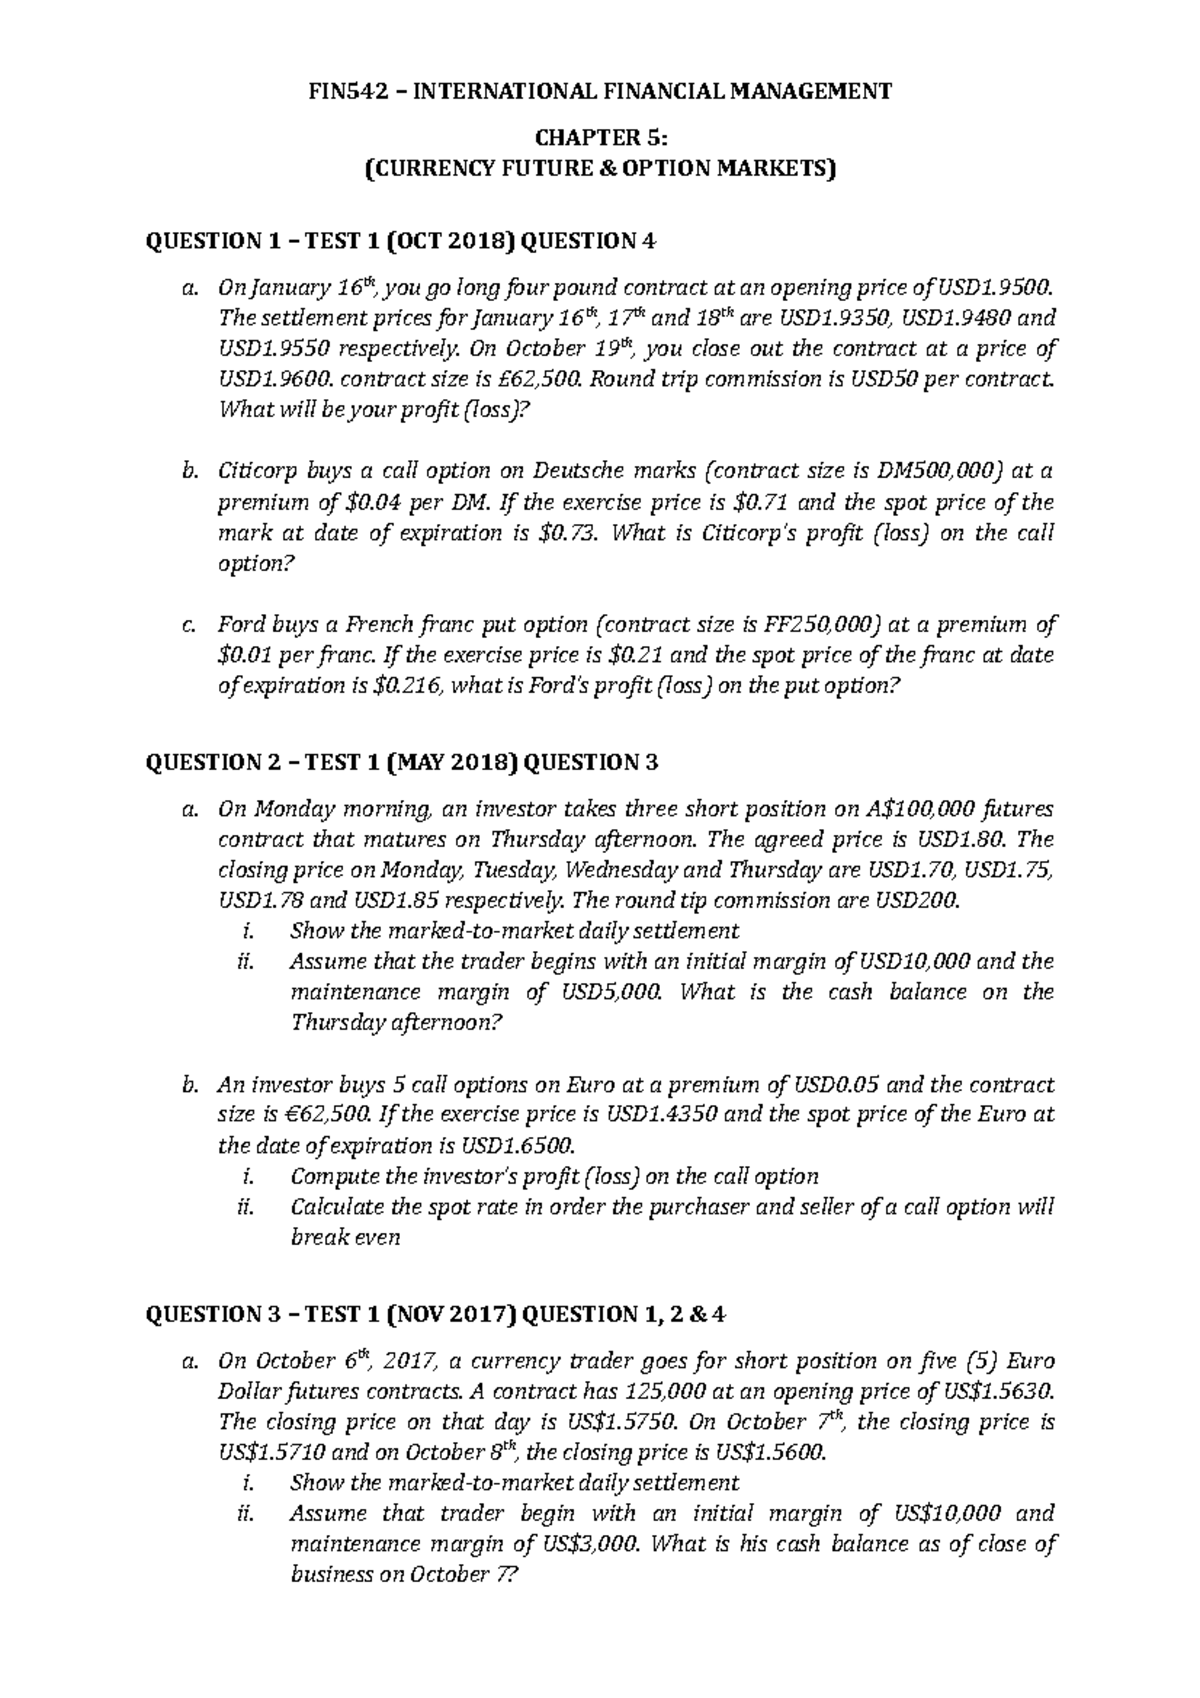
Chapter 5 of an International Financial Management textbook usually deals with foreign exchange exposure measurement and hedging strategies. Transaction exposure, translation exposure, economic exposure, and the tools you use to manage each one. The solutions themselves are rarely complicated math, but they reward careful reading and penalize rushing. Here is the practical approach I use when grading or working through these problems. Start by identifying which type of exposure you are dealing with, then map the cash flows to the correct dates. That single step eliminates roughly half of the mistakes I see from students who jump straight into formulas without understanding what the numbers represent. The typical problem structure goes like this: a company has a receivable or payable denominated in a foreign currency, you are given the spot rate, forward rates, expected future spot rates, and interest rates for both currencies. You need to calculate the expected dollar value under different strategies — doing nothing, using a money market hedge, using a forward hedge, or using options. Each method produces a different result depending on your assumptions about future exchange rates.
I once worked through a problem where a US firm had a 3-month payable of 5 million Swiss francs. The forward rate showed a 2 percent premium on the franc, and the Swiss interest rate was 3 percent while the US rate was 5 percent. The money market hedge required borrowing dollars today, converting to francs at the spot rate, depositing those francs, and using the maturity value to pay the liability. The calculation involves present value adjustments on both sides. When I initially set up the present value factor for the franc deposit incorrectly — using the US rate instead of the Swiss rate — the hedge came out wrong by nearly $18,000. Double-check which currency's rate applies to which cash flow. That mistake costs time and points. A counter-intuitive point that almost no introductory text emphasizes clearly: the money market hedge and the forward hedge should theoretically produce identical results under covered interest rate parity. When they do not, it is either because CIP does not hold in practice due to transaction costs and capital controls, or because the textbook problem uses simplified numbers that create an arbitrage gap. In real markets, the difference between a forward hedge and a money market hedge is often just a few basis points, but in textbook problems that gap can be substantial enough to change which strategy looks better on paper. Students should not assume one method always dominates. Another nuance beginners miss involves option hedges. The cost of the option premium is paid upfront, but the payoff depends on whether the option ends up in the money at expiration. Calculating the effective exchange rate requires accounting for the future value of the premium — which means compounding it at the relevant domestic interest rate over the hedge period. Missing that compounding step shifts your breakeven analysis and can make a supposedly protective hedge look worse than it actually is.
Common pitfalls to avoid: First, mixing up direct and indirect quotation conventions. If the problem quotes EUR/USD as 1.08 and you treat it as the number of euros per dollar instead of dollars per euro, every subsequent calculation is inverted. Second, applying the wrong time fraction to interest rates. A 6-month rate needs to be halved or used with the correct day count, not applied as a full annual rate. Third, forgetting that translation exposure is an accounting concept, not a cash flow concept. The gains or losses from remeasuring balance sheet items do not affect actual cash until the assets are sold or liabilities settled. For translation exposure specifically, the current rate method and the temporal method produce different equity translations depending on whether an entity is considered self-sustaining abroad or financially integrated with its parent. Most textbook problems default to the current rate method for foreign subsidiaries, but the choice matters for the bottom line. Under the current rate method, a weakening home currency increases reported equity. Under the temporal method, it does not. This distinction shows up in exam questions regularly.
Get the Full Details

A Practical Walkthrough
Take a straightforward transaction exposure problem. A US importer owes 10 million yen in 90 days. The spot rate is 110 yen per dollar. The 90-day forward rate is 108 yen per dollar. The US annual interest rate is 4 percent. The Japanese annual interest rate is 1 percent. You need the dollar cost under three approaches. For the forward hedge, you simply lock in 108 yen per dollar. The dollar cost is 10,000,000 divided by 108, which equals approximately $92,593. No interest calculations needed. This is the baseline. For the money market hedge, you calculate how many yen you need to deposit today to have 10 million yen in 90 days. That amount is 10,000,000 divided by (1 plus 0.01 times 90/360), which gives roughly 9,975,062 yen. Convert that to dollars at the spot rate: 9,975,062 divided by 110, giving $90,682. Then compound the dollar cost forward at the US rate for 90 days: $90,682 multiplied by (1 plus 0.04 times 90/360), which equals approximately $91,589.
Comparing the two, the forward hedge costs about $92,593 and the money market hedge costs about $91,589. The money market hedge is cheaper by roughly $1,004 in this scenario. If you had guessed that the forward hedge would always be cheaper because it is more direct, you would be wrong here. The relative attractiveness depends entirely on the interest rate differential and the forward premium or discount. For an option hedge, you would need the strike price, the premium per unit, and the option contract size. Since those vary by problem, the general procedure is: calculate the total premium cost in dollars, compound it to the expiration date, then compare the payoff in three scenarios — the option exercised, the option not exercised, and the breakeven point. The worst-case dollar cost under an option hedge is capped at the strike price plus the future value of the premium. That cap is the primary advantage over a forward hedge, which locks in a fixed rate regardless of favorable movement. The economic exposure calculation is fundamentally different from transaction and translation exposure. It requires projecting how future cash flows change as exchange rates change, then discounting those changes back to present value. Textbook problems often simplify this by providing a single elasticity figure — the percentage change in cash flow per percentage change in the exchange rate. Without that figure, you cannot complete the calculation from first principles. In practice, firms use scenario analysis and Monte Carlo simulations rather than a single elasticity number, but exams almost never require that level of complexity.
Where the Textbook Falls Short
One significant gap in most Chapter 5 treatments is cross-hedging. Not every currency has an actively traded forward market against the dollar. A company exposed to the Turkish lira or the Vietnamese dong often cannot simply enter a forward contract. The textbook solution is to use a correlated currency as a proxy — hedging lira exposure with a Turkish lira equivalent like the euro or Turkish lira futures if they exist. The effectiveness of such a hedge depends entirely on the stability of the correlation, which can deteriorate rapidly during stress periods. No textbook problem adequately addresses this failure mode. Another gap involves netting. Multinational companies with multiple subsidiaries in the same currency often use bilateral or multilateral netting to reduce the volume of transactions needing hedging. The textbook covers this in one paragraph but rarely includes a problem that requires calculating the net position across multiple intercompany flows before determining the hedge amount. In practice, netting can reduce hedge requirements by 30 to 60 percent for firms with dense intercompany transaction networks. If you are looking for International Financial Management Chapter 5 Solutions to compare against your own work, the most reliable sources are the official test bank solutions that accompany the textbook, instructor posted materials from university courses, and occasionally well-maintained study guides on academic forums. Be cautious with user-generated solution sites. The errors in posted solutions are frequent, particularly in the money market hedge sections where interest rate day count conventions and PV/FV direction errors are common.

The single most useful habit I developed after grading dozens of these problem sets is drawing a timeline. Mark the transaction date, the settlement date, and any intermediate dates for interest accrual or option expiration. Label each cash flow with its currency and direction. This simple visual step prevents at least 70 percent of the mistakes I encounter, including ones that seem obvious only after the fact. Chapter 5 is not difficult if you understand that each hedge method is simply a different way of fixing the exchange rate at which a known foreign currency amount will be converted. The mathematics are elementary. The discipline required to apply them correctly is what separates a passing grade from a thorough understanding.