Financial Analysis Doesn't Work The Way Textbooks Say It Does
Most people approaching financial analysis for the first time come at it backwards. They try to learn the ratios before understanding what numbers they're actually looking at. That's like learning golf swing mechanics before you know where the ball is. The practical approach starts with a balance sheet, an income statement, and a cash flow statement. You pull those from whatever source the company publishes. SEC filings for public companies. Internal reports for private ones. You don't need fancy software to start. A spreadsheet and a basic understanding of accounting fundamentals will get you through most introductory work. I once spent three weeks trying to figure out why a manufacturing client's quick ratio looked healthy while their operations were suffocating. The quick ratio was fine on paper, around 1.4, which most analysts would call comfortable. What I missed initially was that their inventory was heavily concentrated in a single warehouse that had been damaged in a flood, and the replacement cost was roughly triple what book value showed. Once I pulled the insurance claim documentation and adjusted for that, the picture changed entirely. It's not a unique situation. I've seen this pattern in at least four companies over the years, all involving inventory valuation issues that ratios alone would completely gloss over.Getting Started With Intro To Financial Analysis
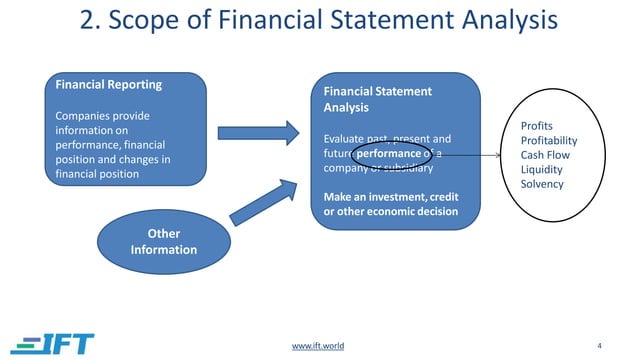
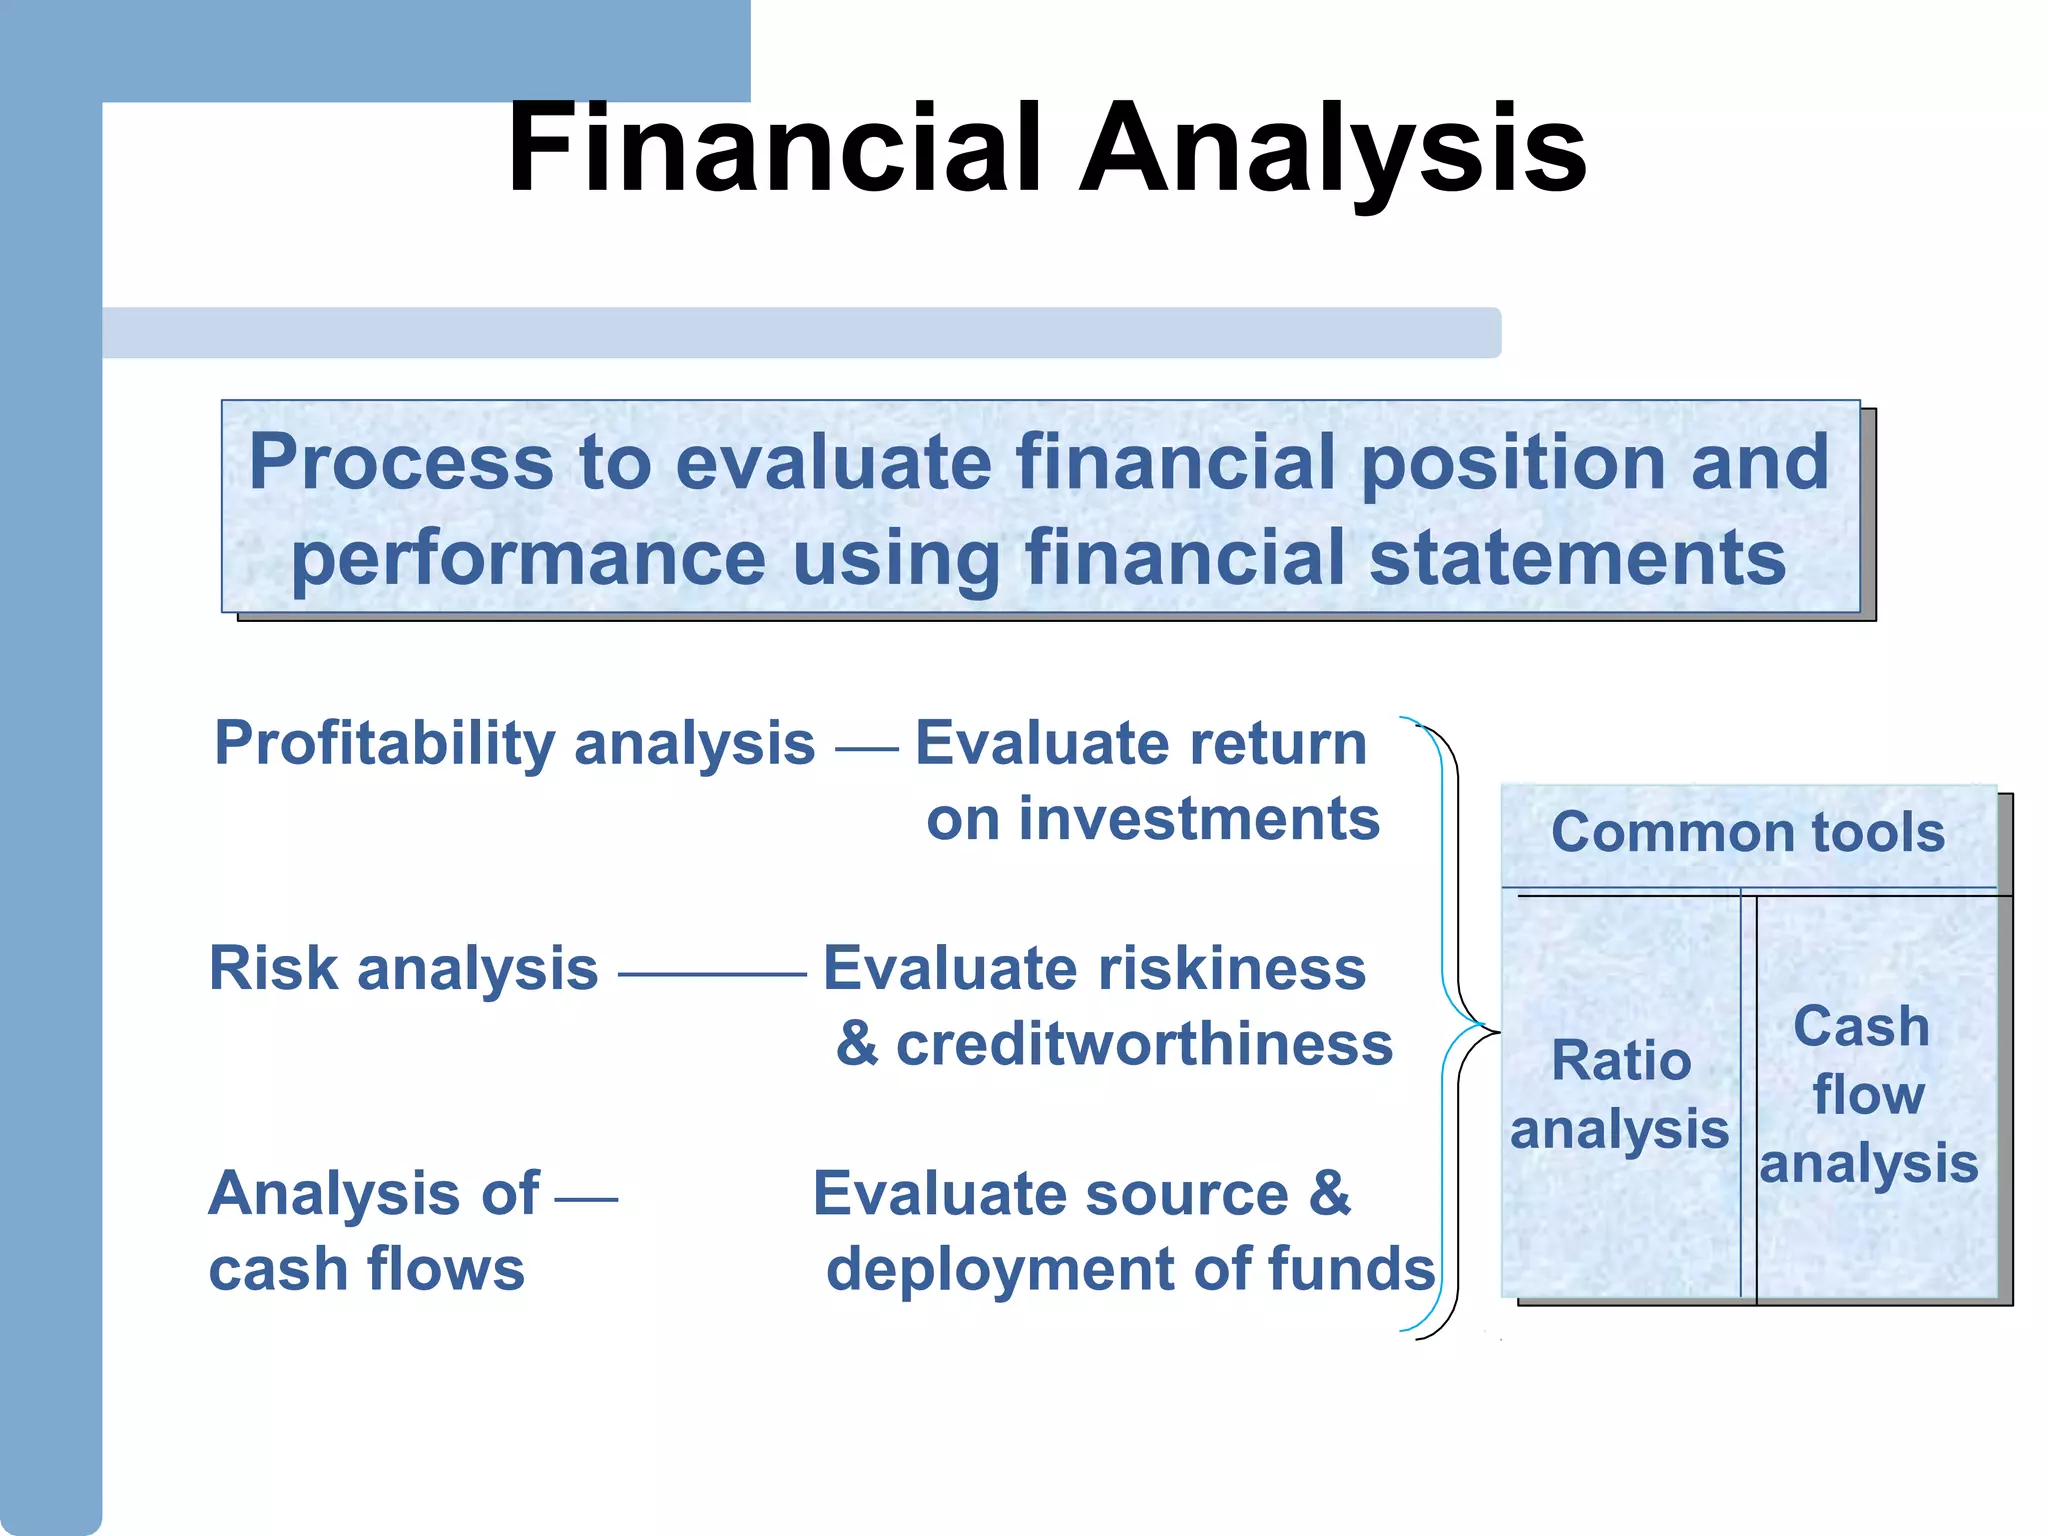
Financial analysis basics aren't complicated conceptually, but they're also not simple. The core process involves three things: understanding the source documents, calculating relevant metrics, and interpreting what those metrics actually mean for the business in question. Most beginners skip straight to the metrics and never circle back to the source data. That's where mistakes happen. Start by pulling a company's annual report and reading the notes section before calculating anything. The notes contain disclosures about accounting methods, one-time charges, and off-balance-sheet liabilities that standard ratio calculations won't show you. A revenue growth rate of 18% sounds good until you read the footnote about a major acquisition boosting top-line numbers by 12 percentage points that year. The organic growth was 6%, not 18%. That's a real difference when you're making decisions. The ratio calculations themselves are straightforward arithmetic. Current assets divided by current liabilities gives you the current ratio. Net income divided by revenue gives you the profit margin. These formulas are taught in every introductory course because they're useful. They're also insufficient on their own.
Here's something most beginner resources don't emphasize enough: trends matter more than individual data points. A single quarter of declining margins could be a seasonal glitch or a one-time expense. Three consecutive quarters of the same trend is a signal worth investigating. I set up a simple rolling 12-quarter trend view in Excel years ago and stopped trying to draw conclusions from single-period comparisons. It eliminated about half the false alarms I used to chase down. When you're learning financial analysis, the biggest mistake isn't using the wrong formula. It's trusting the formula result without checking whether the underlying numbers are meaningful. Gross profit can look healthy while receivables are piling up so fast that cash collection is barely keeping pace. Both numbers appear on the same statements. The connection between them doesn't appear on any single line unless you look for it. I recommend starting with companies in industries you already understand. If you know something about how restaurants operate, analyze a restaurant chain's financials before you try to understand a semiconductor company's. Domain knowledge fills gaps that pure number-crunching can't catch. You'll notice things like a restaurant with declining same-store sales even while total revenue grows through new location openings. That's a red flag in food service that an analyst unfamiliar with the business model might miss entirely.
What Actually Separates Good Analysis From Textbook Exercise
Beginner analyses treat financial statements as self-contained truth. They don't tell the whole story. Every set of numbers has context that sits outside the rows and columns. Understanding that context is what separates people who can crunch ratios from people who can make decisions. Cash flow analysis is where most intro-level work falls apart. People look at net income and assume that's the money available. It's not. Depreciation and amortization get added back in the cash flow statement. Changes in working capital can consume or release significant cash without touching the income statement. A company can show strong earnings and simultaneously be running out of money if it's expanding receivables and inventory faster than it's collecting from customers. I remember working with a small logistics company that reported steady profitability for two years straight. When I traced the cash flow statement line by line, I found that their days sales outstanding had crept from 38 to 72 over that period. They were booking revenue on jobs they hadn't actually been paid for yet. The income statement said one thing. The bank account said another. This happened because their largest customer had renegotiated payment terms mid-year, and nobody in the company was tracking that change against historical norms.
Get the Full Details
The fix wasn't complex. I built a simple weekly tracking sheet that compared current DSO against the trailing 12-month average with a color-coded threshold. Green under 45 days, yellow between 45 and 60, red above 60. It caught the drift early enough that they could renegotiate with the problem customer before it became a crisis. Simple tracking replaced what would have been a much messier quarterly discovery process. Another thing beginners consistently underweight is the quality of earnings. Revenue that comes from transactions with related parties, aggressive revenue recognition, or frequent restatements all degrade the reliability of your analysis. You can spot some of these issues by reading the auditor's report. An unqualified opinion means the numbers are fairly presented within materiality thresholds. Anything else warrants closer scrutiny of the underlying transactions. Industry benchmarking is also underused at the introductory level. Comparing a grocery store's profit margins to a software company's tells you nothing useful. Comparing a grocery store to other grocery stores tells you plenty. Industry averages and peer group comparisons give you a reference frame that makes individual company numbers readable. You can find these through SEC filings of comparable public companies, industry association reports, or subscription databases if you have access to them.
Common Pitfalls That Wipe Out Credibility Early
Over-reliance on any single ratio is the most common error. The market loves simple answers, and financial media reinforces that with headlines about the one metric that supposedly predicts everything. No single metric predicts anything reliably. A strong current ratio means nothing if the underlying receivables are uncollectible. A low debt-to-equity ratio looks conservative until you realize the company has massive operating lease obligations sitting off the balance sheet. Another pitfall is confusing correlation with causation in financial trends. Just because a company's margins expanded while their R&D spending decreased doesn't mean cutting research improved profitability. It might mean they deferred necessary investment, and the real cost hasn't appeared yet. Correlation shows up in spreadsheets easily. Causation requires understanding the business mechanics behind the numbers. Data freshness matters more than people think. Using last year's annual report when a company just released quarterly results means you're analyzing outdated information. Update your working models whenever new filings come out. Set a calendar reminder for earnings seasons if you're tracking multiple companies. This is basic but frequently skipped.
Finally, don't ignore qualitative factors. Management commentary, competitive positioning, regulatory environment, and industry disruption risks all affect a company's financial trajectory in ways that historical ratios can't capture. I've seen analysts miss significant deteriorations because they were too focused on improving ratios and didn't notice the CEO had just resigned, or a key supplier had gone bankrupt, or a new regulation was about to make their primary product non-compliant. The numbers lag the reality. The lag is usually two to six quarters. Financial analysis at the introductory level is really about developing habits: checking the notes before the ratios, tracking trends across periods, comparing to relevant peers, and questioning whether the numbers reflect actual economic conditions. The arithmetic takes a weekend to learn. The judgment takes years to develop, mostly through making the mistakes described above and figuring out how to avoid them next time.