What This Cheat Sheet Actually Is
A lot of people treat a cheat sheet as something you memorize. That's the wrong approach. An Investing Survival Guide Cheat Sheet is a quick-reference document you print out or pin to your desk and open when you need a reminder. It covers the things you know but can't reliably recall under pressure. Things like the 4% rule, position sizing formulas, tax-loss harvesting windows, the difference between dollar-cost averaging and lump-sum timing, and what to do when your stop-loss gets triggered in a gap-down scenario. I've been building these things for about twelve years now. Each one looks different depending on what I'm tracking. Mine currently sits on two A3 pages and lives in a plastic sleeve on my monitor bezel. It changes every six months or so when I find blind spots.
Investing Survival Guide Cheat Sheet
The cheat sheet itself isn't special. What matters is how you use it. Here's the method I settled on after burning through a bunch of approaches. Step one: Write down every question you've ever had about investing that required you to open a browser. Be ruthless. If you had to look it up, it belongs on the sheet. I once spent forty-five minutes across three sessions trying to remember whether capital gains rates change based on filing status or taxable income brackets. That single confusion got a permanent spot on my sheet. Rule of thumb: if a google search interrupted your workflow more than twice, it goes on the list. Step two: Group related items. Position sizing, leverage limits, and margin calls belong in one section. Tax considerations get their own section. Asset allocation rules, rebalancing thresholds, and glide paths go together. Don't organize alphabetically. Organize by scenario. You're looking for answers when something happens, not when you feel like browsing.
Step three: Keep each entry to one line. The moment you write a paragraph, you've failed the format. If it doesn't fit in a single sentence, break it into multiple cheat-sheet entries. This forces clarity. For example: "Rebalance when any asset class drifts more than 5 percentage points from target allocation" is better than a whole explanation of why rebalancing matters. You already know why. You need the threshold. Step four: Print it. Seriously. Screen-reading fatigue is real. When I keep mine on my desk, I glance at it during the first ten minutes of market open. That habit alone has kept me from making impulsive adjustments based on overnight news. The physical placement matters more than the content for some people. Step five: Update it quarterly. Add entries for things you looked up that weren't there. Remove entries you now have firmly memorized. This is where most people stop doing it right because they treat it as a static document. It's not. It's a living record of your knowledge gaps.
Get the Full Details
What Most People Get Wrong
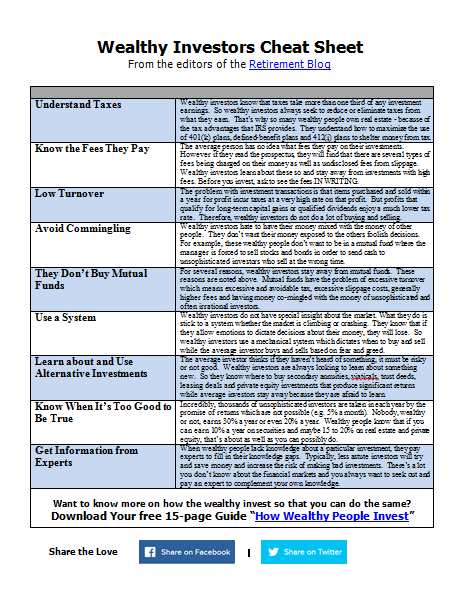
The biggest mistake I see is building a cheat sheet that duplicates what you can find on Google in ten seconds. If the information is universally available and you'll never forget it, don't put it on the sheet. The cheat sheet is for the things that are hard to remember because they're conditional, specific, or frequently confused. Another mistake is including advice without the trigger. Writing "sell losing positions to harvest taxes" on a cheat sheet is useless. You need to know WHEN. The correct version is: "Harvest tax losses before December 15th or within 30 days of closing your position, whichever comes first, and avoid repurchasing the same security within the wash sale window." Now you have actionable information. I learned this the hard way in 2022 when my old cheat sheet told me to "cut losing positions fast." That was it. No timeframe, no criteria, no tax consideration. When tech stocks dropped hard in March, I read that line and immediately sold everything at the worst possible moment. I lost about eighteen percent of my portfolio on that single decision. The replacement entry now reads: "If a position drops more than 15% below your original cost basis AND the thesis hasn't changed, hold and review. Only sell if the thesis broke or you need the funds within six months." This matters enormously during volatile periods.
Counter-Intuitive Things You Should Know
First, diversification isn't a cheat sheet topic most people think about. They list stocks, bonds, real estate, gold. Real diversification means checking correlation coefficients between your holdings. If your "diverse" portfolio has three technology stocks and two cloud computing ETFs, you don't have diversification. You have sector concentration with extra steps. Put a small note on your sheet about running a correlation check annually. It takes twenty minutes and reveals structural risks you'd otherwise miss. Second, the 4% rule is often misunderstood as a ceiling. It's not. It's a floor for how much you might need in the worst case. Using it as a maximum withdrawal target will actually leave you with more money than necessary at retirement. The rule was designed to give a conservative baseline with a 95% probability of lasting thirty years. If you're a careful spender, you might safely withdraw closer to 5%. If you want a margin of safety for unexpected expenses, stick with 4%. The nuance matters for portfolio longevity calculations. Third, dollar-cost averaging isn't universally superior to lump-sum investing. Studies from Vanguard and others show lump-sum beats DCA roughly two-thirds of the time because markets trend upward. But DCA reduces sequence-of-returns risk for someone who just received a large sum and feels anxious. The cheat sheet entry should reflect both facts, not pretend one is the answer.
Limitations and When It Fails
A cheat sheet has a real bottleneck: it doesn't help with emotional regulation. I've seen people follow their cheat sheet perfectly through a market crash and then ignore it entirely during a speculative mania. The document is rational. You're not. No cheat sheet fixes that gap. Therapy, coaching, or a written investment policy statement with pre-committed rules tends to be more effective for behavioral problems. The second limitation is that cheat sheets become outdated. The tax rules changed significantly in 2025 with new RMD age adjustments and modified Roth conversion provisions. My sheet needed about three hours of updates across two sessions. If you haven't touched your document in over a year, something has probably changed. Check the IRS website and any relevant regulatory updates before assuming your cheat sheet is still accurate. For people managing very large portfolios above ten million dollars, a single-page cheat sheet simply won't capture the complexity. Estate planning, trust structures, and alternative investment nuances require professional guidance and more elaborate documentation. In that case, a cheat sheet is a supplement, not a substitute.

Free Download
I've posted my current template in Google Sheets format with pre-populated sections and conditional formatting that highlights entries due for review. The file is available at the link below. It's structured so you can fill in the blanks with your own situations and preferences. You'll also find a blank version if you want to build from scratch. The Google Sheets link is here: investing-survival-guide-cheat-sheet-template. It's free, no email required, no premium upsell.


