The Basics Before You Open Any Spreadsheet
Most people learning real estate math get bogged down in theory before they ever see a real deal. The formulas are simple. The problem is applying them correctly under pressure when you are looking at a deal and your phone is blowing up with messages. Here is what actually matters. Gross Rent Multiplier (GRM) is just purchase price divided by gross annual rental income. That is it. A property priced at $450,000 with $36,000 in annual rent has a GRM of 12.5. You compare that number against similar properties in the same neighborhood to see if the price is in line. Nothing fancy. The cap rate is more useful but people mess this up constantly. It is net operating income divided by property value or purchase price. If a property produces $30,000 in NOI and sells for $400,000, the cap rate is 7.5%. Cap rate measures the return you would get if you bought the property all-cash. It does not account for financing, taxes, or any of the other expenses that actually eat into your check. That is the first thing you need to understand before you rely on it.
Real Estate Math Cheat Sheet
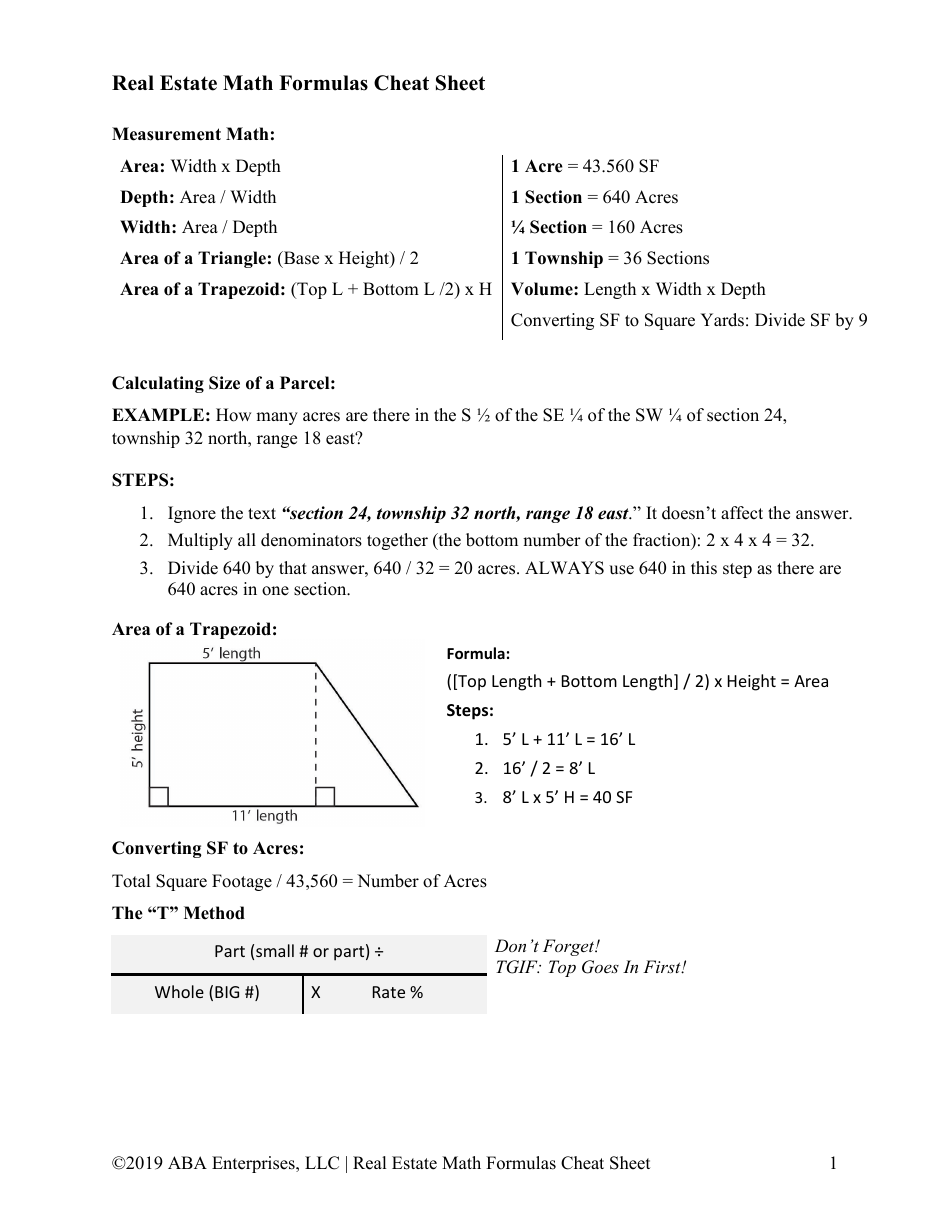
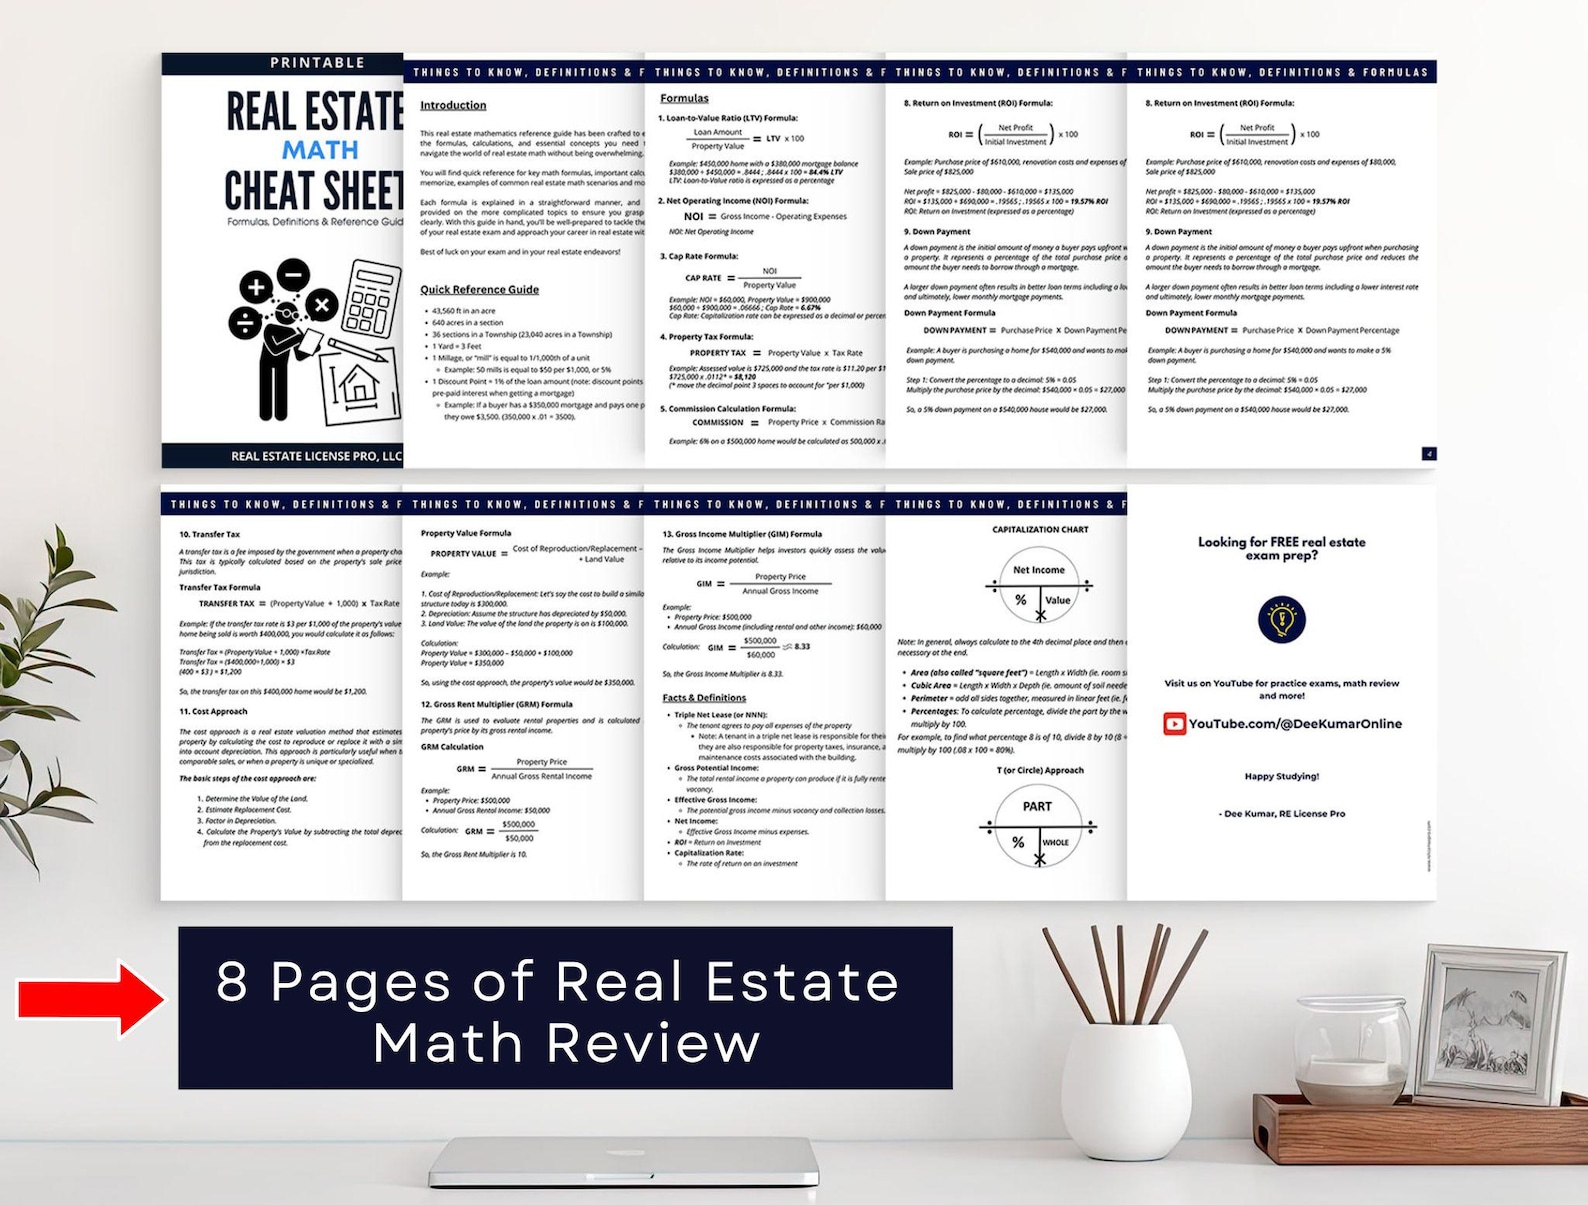
I put together what I call a Real Estate Math Cheat Sheet because I was tired of flipping between five different tabs while trying to analyze deals. It sits on my desk and I reference it constantly. The core formulas are: ROI = (Net Profit / Total Investment) x 100
Cash-on-Cash Return = Annual Pre-Tax Cash Flow / Total Cash Invested
Debt Service Coverage Ratio (DSCR) = NOI / Annual Debt Service
Loan-to-Value Ratio (LTV) = Loan Amount / Appraised Value
Annual Property Tax = Assessed Value x Tax Rate
Monthly PITI = Principal + Interest + Taxes + Insurance
Percent to Decimal = Move decimal two places left (25% = 0.25)
Decimal to Percent = Move decimal two places right (0.075 = 7.5%) The percent conversion one sounds stupid simple but I have seen people lose deals because they multiplied by 25 instead of 0.25. It happens more than you would think when you are rushing.
The Formulas That Actually Matter in Practice
GRM and cap rate are the entry-level numbers. Once you get past those, the calculations that separate people who make money from people who lose money are the debt service and cash flow projections. Lenders require a DSCR above 1.0, usually 1.20 or higher depending on the loan program. If your NOI is $36,000 and your annual debt service is $32,000, your DSCR is 1.125. Some lenders will reject that outright. Others will require a larger down payment. Know your lender's threshold before you fall in love with a property. The bricks and mortar method for calculating interest is another place where people trip. If you need to find the interest on a loan for a partial period, multiply the principal by the rate by the time in years. For example, interest on $100,000 at 7% for 6 months: $100,000 x 0.07 x 0.5 = $3,500. This comes up constantly during closings when prorating interest between buyer and seller. Prorations are where most closing statement errors happen. Property taxes, HOA fees, rents, and insurance premiums all get prorated based on the closing date. The standard method is the 30-day month, 360-day year approach. Each month counts as 30 days. If closing is on the 15th, that is exactly half a month. Simple in theory. Messed up in practice because whoever prepares the closing statement is working with incomplete data from the seller's records.
Get the Full Details

A Specific Problem I Encountered
Last year I was analyzing a multi-family deal where the seller provided rent rolls that showed unit 4B at $1,200 per month. The actual lease had a $1,350 renewal already signed that the seller hadn't updated on the roll. The cap rate based on the provided roll looked terrible. Once I pulled the actual lease and adjusted the income, the numbers flipped completely. The deal went from a marginally acceptable 5.8% cap rate to a solid 7.1%. This is exactly why you never trust the proforma the seller hands you without verifying every line item against actual leases and expense records. A Real Estate Math Cheat Sheet is useless if your input numbers are wrong. The formulas I listed above work fine for standard residential investment properties. They do not work well for everything. Vacancy rates, collection losses, and bad debt are often glossed over in quick analyses but they can easily eat 5 to 10% of gross income in older properties. I always run a vacancy and collection loss factor of at least 8% into my NOI calculations even when the current tenant profile looks stable. It costs you nothing extra to be conservative and it saves you from a surprise when the market softens. Deed constants are another area where people waste time. The deed constant represents the annual debt service as a percentage of the loan amount. You can look it up in a table based on interest rate and term. For example, at 7% over 25 years, the deed constant is approximately 0.0799. Multiply that by the loan amount and you get the annual debt service instantly without running through a full amortization schedule. This was a lifesaver when I was analyzing dozens of deals in a single weekend and did not have time to build out individual payment models for each one.
There is also the issue of imputed depreciation that nobody talks about. When you calculate cap rates across properties, newer buildings naturally show higher cap rates because their expense base is lower. An older building with deferred maintenance will show a deceptively attractive cap rate until you factor in the roof replacement, HVAC updates, and other capital expenditures that are overdue. I always subtract a reserve for capital expenditures of roughly 5% of gross income before calculating my effective cap rate. It is a rough number but it keeps you honest.
How I Actually Use This Stuff Day to Day
I keep a single spreadsheet with the formulas built in so I am not doing mental math under pressure. I input the purchase price, the gross income, the operating expenses, and the financing terms. The sheet spits out GRM, cap rate, cash-on-cash return, DSCR, and total cash needed to close. It takes about three minutes to run a full analysis once the numbers are entered. Without the sheet, I would be spending 20 or 30 minutes per deal doing the same calculations manually and making arithmetic errors along the way. The biggest limitation of any cheat sheet or formula-based approach is that it cannot account for deal-specific complications. A property with a ground lease, a tenancy in common structure, or an unusual zoning situation will throw off every standard metric. In those cases, you need to build a custom proforma or bring in someone who specializes in that asset class. The formulas are a starting point, not a substitute for due diligence. I also use a quick rule of thumb for rough screening: if a property does not meet a minimum 8% cash-on-cash return after reserves, I usually pass unless there is a significant appreciation story that I can quantify. This filter alone saved me from three bad deals in the past year. The math on those properties looked fine on the surface until I ran the full proforma with realistic vacancy and expense assumptions.