Getting Your Investment Tracking Actually Working
Most people treat an investing troubleshooting guide as a reference document. That is backwards. The real utility comes from using it while you are actively working through a broken process, which means it needs to function as a decision tree rather than a glossary. I built mine after watching my own portfolio tracking collapse during a migration from a manual spreadsheet to a broker API integration. The spreadsheet had accumulated years of custom formulas, and when I tried to replicate them in Python, nothing matched. The broker's API returned data in a completely different granularity than what I expected, and I spent roughly three weeks debugging before I realized the problem wasn't my code at all. The core principle is that your guide should mirror the actual failure modes you encounter, not the textbook ideal. A typical investor will hit problems in three buckets: data availability, calculation accuracy, and automation reliability. Your guide needs to address each bucket with specific diagnostic steps, not generic advice like "check your connection." Most guides I see online just tell you to verify your API key and move on, which is useless when the real issue is a stale cache or a misaligned date range on the data feed. Data availability problems are the most common and the most frustrating. You pull a position statement and the holdings don't match your records. The first thing I check is the settlement date versus the trade date. Brokers sometimes report trades on the execution date but update holdings on the settlement date, usually T+1 or T+2 depending on the asset class and jurisdiction. If you are pulling data through an automated sync, you need to know which date the broker is actually using for your query. I ran into this specifically with international equities held through a US-based broker. The settlement cycle was T+2, but the broker's API documentation didn't mention it, and my reconciliation script was flagging every international position as a missing trade for two full business days after execution. The workaround was straightforward: I added a date offset parameter to my data pull that shifted the query forward by two days for non-US equities, and I also started logging the raw broker response alongside my calculated positions so I could compare them directly when discrepancies appeared.
Calculation accuracy is where most self-built systems quietly degrade over time. Your cost basis formula looked correct six months ago, but something changed. Maybe the broker added a new fee structure, maybe you started receiving DRIP reinvestments that your script doesn't account for, or maybe a stock split happened and your historical price data didn't adjust. I learned this the hard way when I discovered that my unrealized gains calculation was consistently overstated by about 4% on a particular holding. The issue turned out to be that I was using adjusted close prices from a free data source for historical calculations but unadjusted close prices for current values. The split-adjustment was being applied inconsistently across the two sources. Fixing it required going back through three years of transaction data and re-downloading the entire price history from a single consistent source, then rebuilding the cost basis calculation with a strict rule: every price reference in the system must come from the same adjusted price series. Automation reliability is a different problem entirely. Your script runs fine in testing but fails in production because of rate limits, authentication token expiry, or a dependency that went out of service. The best practice here is to design your guide around monitoring and alerting, not just error recovery. Set up a daily health check that verifies your data source is responsive, your calculations are producing values within expected ranges, and your output files are being written on schedule. I use a simple threshold check: if my portfolio total changes by more than 15% between consecutive daily pulls without a corresponding transaction record, the system flags it for manual review. This caught a broker API change that started returning net asset value instead of market price for one of my mutual fund holdings. The fund itself hadn't moved 15% in a single day. The API change did. The second counter-intuitive insight most people miss is that completeness of error handling matters more than speed of resolution. A guide that helps you fix a problem in five minutes but doesn't document why it happened will produce the same problem again next month. Every troubleshooting entry should include the root cause, the symptom pattern, and at least one preventive measure. I structure mine with a consistent format: the error symptom first, the diagnostic path to isolate it, the exact fix, and then a note about what to watch for next time. This takes longer to write but cuts future debugging time dramatically because you aren't starting from zero each occurrence.
Here is another thing nobody talks about: your troubleshooting guide needs to account for the difference between transient and systemic failures. A transient failure is a temporary network hiccup or a brief API outage. You retry and it resolves. A systemic failure is a structural mismatch between your assumptions and how the data actually works. The problem with most guides is that they treat every error the same way. They tell you to retry, then escalate to support, then rebuild. That sequence wastes time because you spend twenty minutes retrying a transient error before realizing it was systemic all along. The faster approach is a quick check list: is the error reproducible with identical inputs? If yes, it is systemic. If it only happens sporadically, it is transient and you can retry without digging deeper yet. When I build these guides, I also keep a dedicated section for edge cases that break standard assumptions. This includes things like fractional shares from DRIP reinvestments, corporate actions that affect cost basis retroactively, foreign currency gain or loss on international holdings, and tax lot selection methods that the broker implements differently than your system expects. I had a particularly annoying case with a dividend reinvestment that created twelve fractional share lots across four different purchase dates. My cost basis calculator was treating all those fractions as a single aggregate lot, which threw off my realized gains calculation by enough to matter on tax day. The fix was to implement lot-level tracking at the fractional cent, which meant rewriting how I stored and retrieved transaction data. I added that case to the guide with the specific data format change required, because it only took me two weeks the first time and I knew it would happen again. There are also scenarios where a troubleshooting guide simply cannot help you. When your broker does not provide an API at all, you are stuck with manual export and import processes, and the failure modes are entirely different. You can troubleshoot CSV parsing errors and mapping mismatches, but you cannot troubleshoot what you cannot access programmatically. In those cases, the best practice is to build your guide around the export format and field mapping, not around API calls. Similarly, if you are using a third-party aggregator service that sits between your broker and your analysis tool, you inherit their failure modes too. Their downtime, their data gaps, their undocumented changes — none of that is in your control, and your guide should reflect that limitation explicitly rather than pretending the problem is solvable on your end.
Get the Full Details
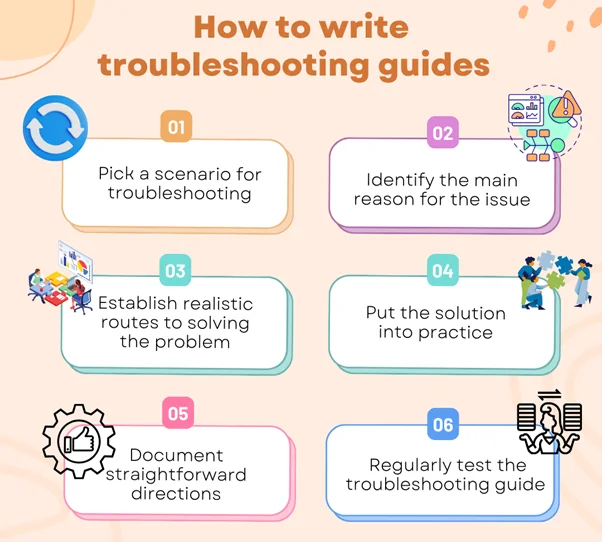
The other practical bottleneck most guides ignore is data retention and historical depth. If you are pulling year-over-year performance data and your guide tells you to verify accuracy by comparing to a broker statement, you need to understand that most brokers only retain detailed transaction history for seven to ten years. Before that window, you are working from memory or scanned PDFs. A troubleshooting guide that doesn't acknowledge this constraint will send you on a wild goose chase trying to reconcile a transaction from 2014 that no digital system has on file. I solved this by maintaining a separate archival database that I update manually whenever I find older records, and I added a note to my guide flagging any transaction prior to the broker's retention window as requiring manual verification rather than automated cross-referencing. If you are starting from scratch, the most useful first step is to log every error you encounter for two weeks before writing any part of the guide. Most people start writing immediately, which means their guide covers the errors they expect, not the errors that actually occur. My first draft covered eight common problems. My second draft, written after two weeks of actual usage, covered twenty-three. Half of those were things I wouldn't have thought to include. The most valuable entry in my guide right now is for a problem I encountered only once: the broker returned a successful API response with a valid status code but an empty holdings array because my account had been restructured overnight and my old account ID was no longer valid. The status code was 200, which meant every automated check assumed everything was fine. The guide entry for that one is long because the diagnostic path is long, but it saved me six hours the next time it happened. For people who want a starting template rather than building from scratch, there are a few open-source frameworks worth looking at. Portfolio Performance by Hans-Peter Krutzler is a desktop application that includes built-in troubleshooting for common data import issues, and its documentation covers the most frequent failure modes for broker exports. For those working in Python, the quantstats and PortfolioPerformance libraries both have issue trackers that essentially function as living troubleshooting guides. The Yahoo Finance data layer, which many projects depend on, has a well-documented set of known issues including delayed pricing, split adjustment inconsistencies, and suspension of certain endpoints — all of which show up regularly as errors in investment tracking systems.
The final piece most people skip is version tracking for your guide itself. Your data sources change, your broker updates their API, tax rules shift, and your own system evolves. An outdated troubleshooting guide is worse than no guide because it gives you false confidence. I maintain a changelog in my guide that records every modification, along with the date and the trigger event. If a troubleshooting step no longer applies, I mark it as deprecated rather than deleting it, because someone searching for an old error message might still find that entry. This has saved me more than once when a broker deprecated a field I had been relying on and I needed to go back and find the migration path I had documented during the last API update.