Getting Started Without Losing Your Mind
The first thing you need to understand is that most people who start investing do it completely backwards. They see a meme about stocks going up, they buy something because it has a catchy ticker symbol, and then they panic when it drops ten percent the next week. This is why the Investing Ultimate Guide Roadmap exists in its current form - it was built specifically to stop that pattern from repeating itself with anyone who actually reads it. I put together my first version of a structured investing roadmap back in 2016 when I was managing a small portfolio for myself and two siblings. We had lost about twelve thousand dollars in eight months between us, mostly because none of us knew the difference between a stock, an ETF, and some crypto token that appeared on an exchange without any actual fundamentals behind it. The roadmap started as a simple one-page document on Google Docs. It grew into something people actually shared around.
What the Investing Ultimate Guide Roadmap Actually Covers
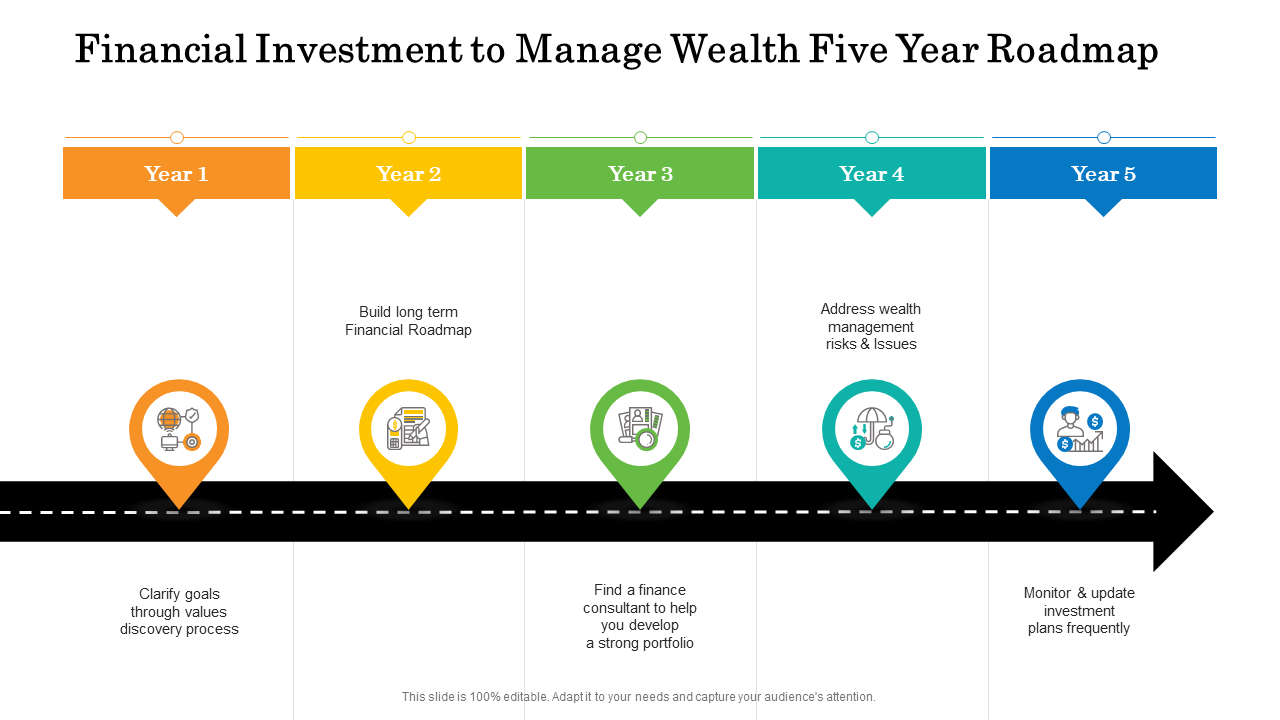
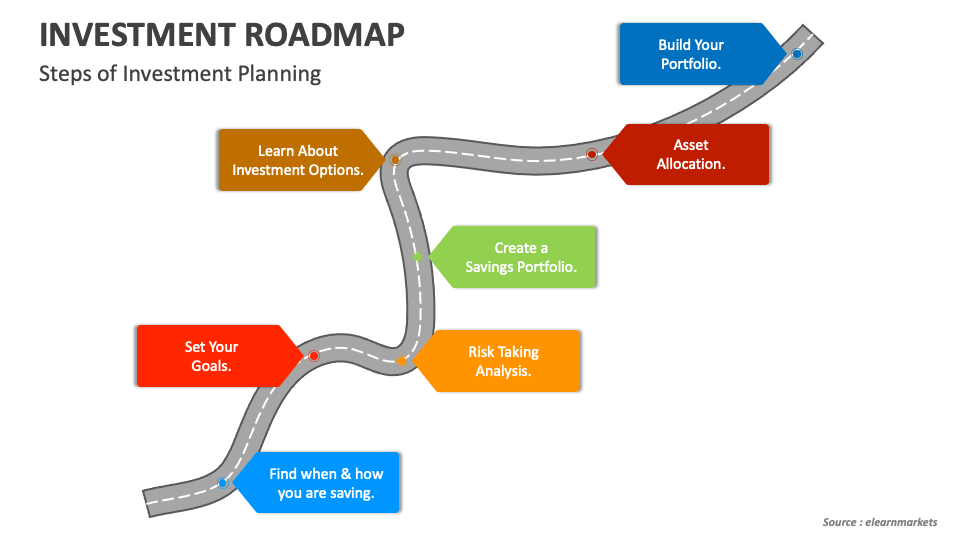
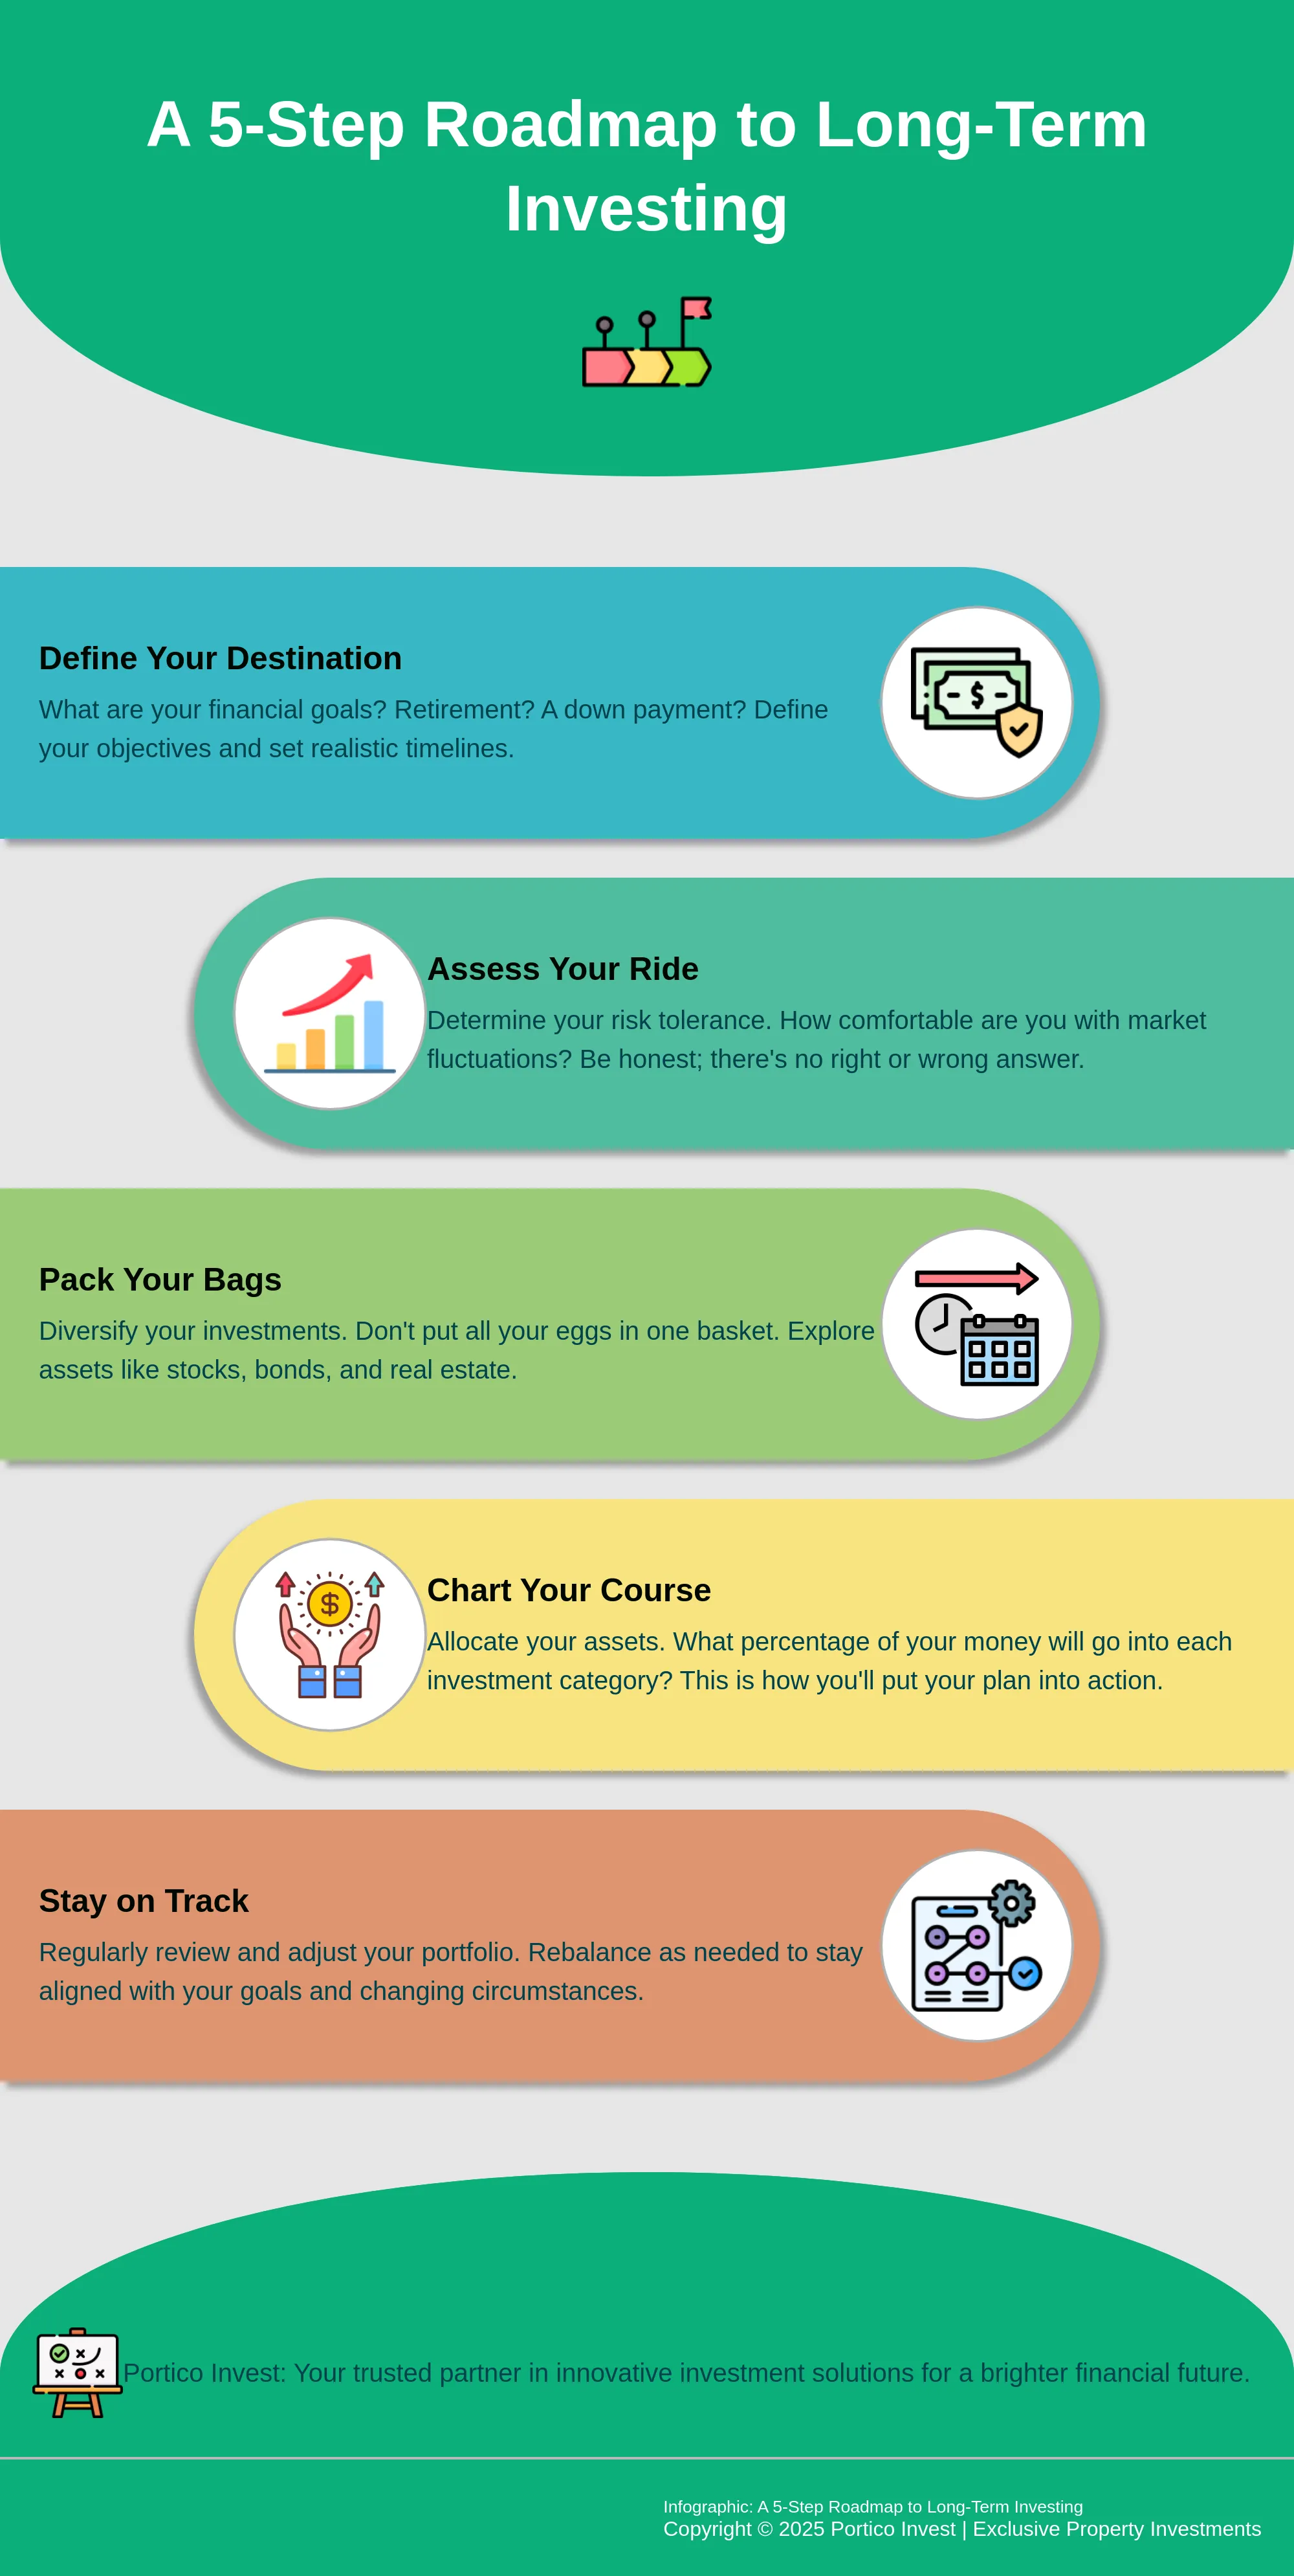
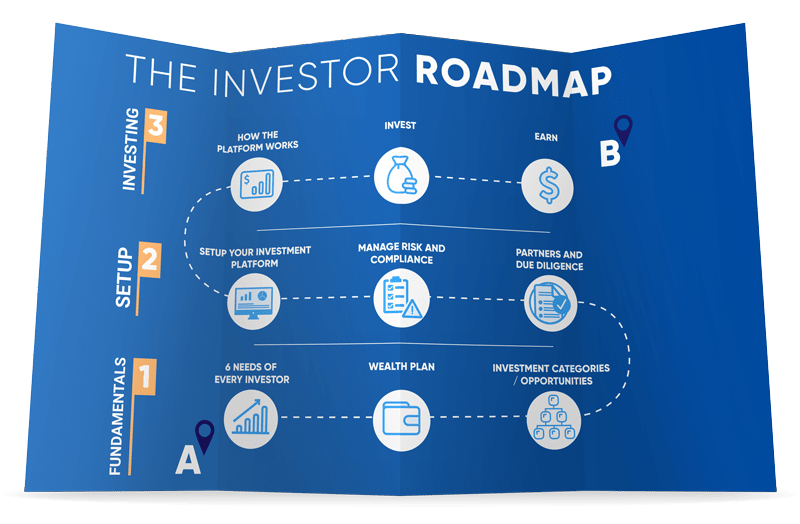
The roadmap breaks down into six phases, though not everyone needs to go through all of them in order. Phase one is the basics - understanding what an asset actually is, how returns work, what compound interest means in practice, and the difference between saving and investing. Most people skip this and come back to it later when they have already lost money and realize they never understood what they owned. Phase two covers the different vehicle types. Stocks, bonds, ETFs, mutual funds, REITs, CDs, money market accounts. Each one has different tax implications, liquidity profiles, and risk characteristics. You need to know what each one does before you put a single dollar into any of them. I once watched someone put their entire emergency fund into a single tech stock because a YouTube video told them it was "the next NVIDIA." That stock was down forty percent six months later and they had no cash reserves when their car broke down. Phase three is where the roadmap gets useful. Asset allocation and diversification. This is the part that separates people who build wealth slowly from people who gamble and either get lucky or get wiped out. A basic guideline most financial planners will tell you is to keep your stock-to-bond ratio aligned with your time horizon, but the reality is more nuanced. If you are thirty years old and your income is stable, you might be fine with 90/10. If you are thirty and work in an industry that lays people off during recessions, you might want 70/30 even at the same age because your human capital is already heavily tilted toward equities.
Phase four covers the actual mechanics of how to open accounts, what brokerage to use, how to set up automatic contributions, and the difference between taxable and tax-advantaged accounts. This sounds boring and people skip ahead, but getting this wrong costs real money. I had a client who maxed out her 401k but never opened an IRA, and she was paying about three thousand dollars a year in unnecessary taxes because she did not understand the sequence of account types. That compounds over decades. Phase five is rebalancing and maintenance. Most beginners think investing is a thing you do once and then forget about. It is not. You need to rebalance at least annually, sometimes semi-annually depending on your allocation targets and how volatile your chosen assets are. If you do not rebalance, your portfolio slowly drifts toward whichever asset performed best, which means you are unintentionally increasing your risk exposure over time without realizing it. I found this out the hard way in 2020 when my tech-heavy portfolio was up sixty percent and felt like genius. It was just concentration risk masquerading as skill. When the correction hit in March 2022, I was down forty-two percent because I never rebalanced. Phase six is the psychological side. Behavioral finance, loss aversion, recency bias, and the other cognitive traps that make smart people make stupid decisions with their money. This is the hardest phase because it requires honest self-assessment. You have to admit that when the market drops, your instinct is to sell, and then you need a system that prevents you from acting on that instinct.
Get the Full Details

How to Actually Use This Roadmap
The roadmap is not a book you read once and file away. It is a reference document. You should read through it front to back when you are starting out, then return to specific sections when you encounter situations you are not sure how to handle. A lot of people treat investing guides like novels - they want a beginning, a middle, and an end. Investing does not work that way. I recommend starting with phase one and spending at least two weeks on it if you know absolutely nothing about how markets work. That means reading about how the S&P 500 is constructed, what P/E ratios mean, how bond yields work, and why inflation matters to your portfolio. If you rush through phase one, everything after it will feel like guessing. I learned this when I tried to teach my father-in-law to invest. He skipped straight to picking stocks because he wanted results. He picked three stocks in his first week and lost eight percent before he had even set up a proper account structure. When you get to phase three and you are figuring out your asset allocation, do not use a generic online calculator and call it done. Those calculators assume you are a typical person with typical income and typical risk tolerance. You are none of those things. I built a custom spreadsheet for my own allocation that factors in my income stability, my existing debt, my age, my dependents, and my actual emotional reaction to market drops. I track it quarterly. The generic calculators would have put me at 80/20. My spreadsheet says 65/35 because my job is stable but my spouse is not employed and we have two kids in college. That changes the risk profile significantly.
The tax optimization section in phase four deserves more attention than most people give it. The order in which you fill your accounts matters. The standard sequence is employer 401k up to the match, then HSA if you have one, then Roth IRA, then back to maxing the 401k, then taxable brokerage. But this assumes you are in a standard situation. If you are self-employed, you might want to consider a SEP IRA or Solo 401k instead. If you are in a very high tax bracket now but expect to be in a lower bracket in retirement, traditional accounts might make more sense than Roth. I spent three years in a high bracket, used traditional accounts aggressively, and moved to a lower bracket when I switched to consulting work. The tax savings were substantial, maybe twelve thousand dollars over those three years alone.
Common Problems and What to Do About Them
The biggest problem I see people run into is overcomplicating things. They read too much, watch too many videos, and end up paralyzed by analysis. The roadmap is designed to prevent this, but only if you actually follow it in order instead of jumping around. Set a timeline for each phase. Give yourself four to six weeks per phase if you are starting from zero. If you already understand phases one and two, move faster. But do not skip ahead because something in a later phase sounds exciting. You are not choosing investments yet. You are building a foundation. Another issue is cost awareness. Expense ratios matter more than most people realize. A fund with a 0.75% expense ratio will cost you significantly more over thirty years than an identical fund with a 0.05% expense ratio. On a hundred thousand dollars invested, that is roughly twenty thousand dollars in extra fees over three decades, assuming the same returns before fees. I see people pick funds based on past performance and ignore the expense ratio entirely. Past performance is meaningless. Expense ratios are a certainty. Here is something most beginner guides will not tell you: the best investment strategy is the one you can actually stick with. A perfectly optimized portfolio that you abandon during the first market crash is worse than a mediocre portfolio you hold through multiple cycles. I have seen people with sophisticated options strategies and sector rotation systems underperform a simple S&P 500 index fund over a ten-year period. Not because the strategy was bad in theory, but because they could not emotionally handle the drawdowns and sold at the worst times. Your strategy needs to survive your psychology, not just the markets.
There is also the problem of timing the market versus time in the market. Everyone knows they should not try to time the market, but very few people actually accept that fact when they are looking at their portfolio dropping. Dollar-cost averaging helps here because it removes the decision from the equation. You invest the same amount on the same schedule regardless of what the market is doing. It is boring and it works. I switched from trying to pick entry points to automatic monthly investments in 2019 and my returns improved by about two percentage points annually because I stopped selling during corrections and started buying them automatically.
Where This Roadmap Falls Short
The Investing Ultimate Guide Roadmap is not a complete solution. It does not cover alternative investments like private equity, venture capital, or direct real estate. It does not address tax-loss harvesting strategies in depth because those depend heavily on your individual tax situation and jurisdiction. It does not provide specific fund recommendations because what works for one person might be terrible for another, and recommending specific securities crosses into financial advice territory that I am not qualified to give. It also assumes you have disposable income to invest. If you are carrying high-interest debt, paying that off should come before any investing. The roadmap mentions this in phase one, but people ignore it. I had a student who was carrying six thousand dollars in credit card debt at twenty-four percent interest and was simultaneously trying to pick individual stocks. The math is not complicated. Paying off that debt gives you a guaranteed twenty-four percent return. The stock market averages about ten percent before inflation. She was losing money by investing before she eliminated the debt. I made her stop trading and focus on debt repayment for six months. She came back to me after and her mindset was completely different because she understood the foundation first. If you want a downloadable version of the full roadmap, the current iteration is available through the personal finance resources page on my site. It is updated roughly every year to reflect changes in tax law and market conditions. The last major update was in early 2024 after the SEC revised some of the fee disclosure rules for brokerages, which affects how you should evaluate account costs. I also added a section on Robo-advisors versus self-managing because the line between those two has gotten blurrier in recent years.
The roadmap is a starting point, not a finish line. Investing is a skill that develops over decades, not weeks. The people who do well are not the ones who know the most facts - they are the ones who avoid the most mistakes. And the biggest mistake is thinking you need to know everything before you start.