What You Actually Need to Know Before Buying An Annuity
Annuities are insurance contracts that pay out a steady stream of income, usually in retirement. That is the textbook definition. The reality is messier. Most people who walk into a bank or call a financial advisor about annuities have never looked at the fine print of a single one. They hear "guaranteed income" and think they have solved their retirement problem. They have not solved anything yet. They have just locked away a chunk of money. When you buy an annuity, you give a lump sum or a series of payments to an insurance company. In return, they promise to send you money starting either immediately or at some future date. There are three main categories that actually matter: fixed, variable, and indexed. Fixed annuities pay a set rate, usually between 3 and 5 percent depending on the current environment. Variable annuities let you choose sub-funds, similar to mutual funds, and your payout fluctuates with market performance. Indexed annuities tie returns to a market index like the S&P 500, with a cap on gains and a floor that limits losses. Something like 0 to 4 percent participation rates and annual caps are typical structures. The payout phase works differently depending on the type. With a fixed annuity, the company calculates your payment using actuarial tables based on your age, gender, and the interest rate they locked in. You get the same check every period. With a variable annuity, the insurance company uses your account value divided by the current unit value of your chosen funds. If the market drops, your payment drops. Indexed annuities sit somewhere in the middle with formula-based calculations.
I learned this the hard way a few years ago when a client had a fixed indexed annuity purchased in 2014. The contract had a 9 percent cap on gains and a 0 percent floor during the accumulation phase. The client thought she was protected from downside risk entirely. She was not. During the 2022 market correction, her account value dropped because the indexing method used point-to-point with no high-water mark provision. She lost about 8 percent of her principal that year despite the "floor" language that sounded protective. The workaround was to renegotiate the distribution election to a systematic withdrawal that pulled from the remaining balance at a conservative rate, preserving what was left rather than forcing a full annuitization at a depressed valuation. It cost her some upside but stopped the bleeding.
How to Actually Decide If an Annuity Makes Sense for You
Before you put any money into an annuity, answer one question: do you have a guaranteed income gap in retirement? That means after counting Social Security, pension payments, and any other fixed sources, is there a shortfall for your basic living expenses? If the answer is yes, an annuity can fill it. If the answer is no, you are likely buying something you do not need. The math behind annuity pricing is not complicated. Insurers use mortality credits, which is the pool of money from people who die earlier than average subsidizing those who live longer. This is the core engine. Without mortality credits, annuities are just taxable savings accounts with worse fees. The longer you live past the breakeven point, the better the deal. For a 65-year-old buying a single life immediate annuity today, the breakeven is typically around age 78 to 82 depending on the insurer and interest rate environment. If you have a family history of living past 85, the annuity starts looking reasonable. If not, you might be leaving money on the table. Here is a number most people miss. Annuity fees, especially in variable products, can range from 1.5 to 3 percent annually when you combine the mortality and expense risk charge, the underlying fund expense ratios, and any rider costs. A 2.5 percent fee on a variable annuity erodes compounding dramatically over 20 years. On a $200,000 investment growing at 7 percent before fees, a 2.5 percent annual fee reduces the ending value to roughly $330,000 instead of $440,000. That is a $110,000 difference purely from fees. The insurance company keeps that money regardless of market performance.
Get the Full Details
I have sat through enough sales presentations to recognize the pattern. The advisor will show you a projection using optimistic market returns and ignore the surrender charges that lock you in for seven to ten years. They will mention the death benefit rider as a free feature when it actually costs an extra 0.75 to 1.25 percent annually. When I push back on the total cost, the conversation usually pivots to tax deferral, which is a valid point but only if you are in a higher tax bracket in retirement than you are now. If you are not, the tax advantage is irrelevant and you are paying for nothing.
Step-by-Step Process for Purchasing an Annuity Correctly
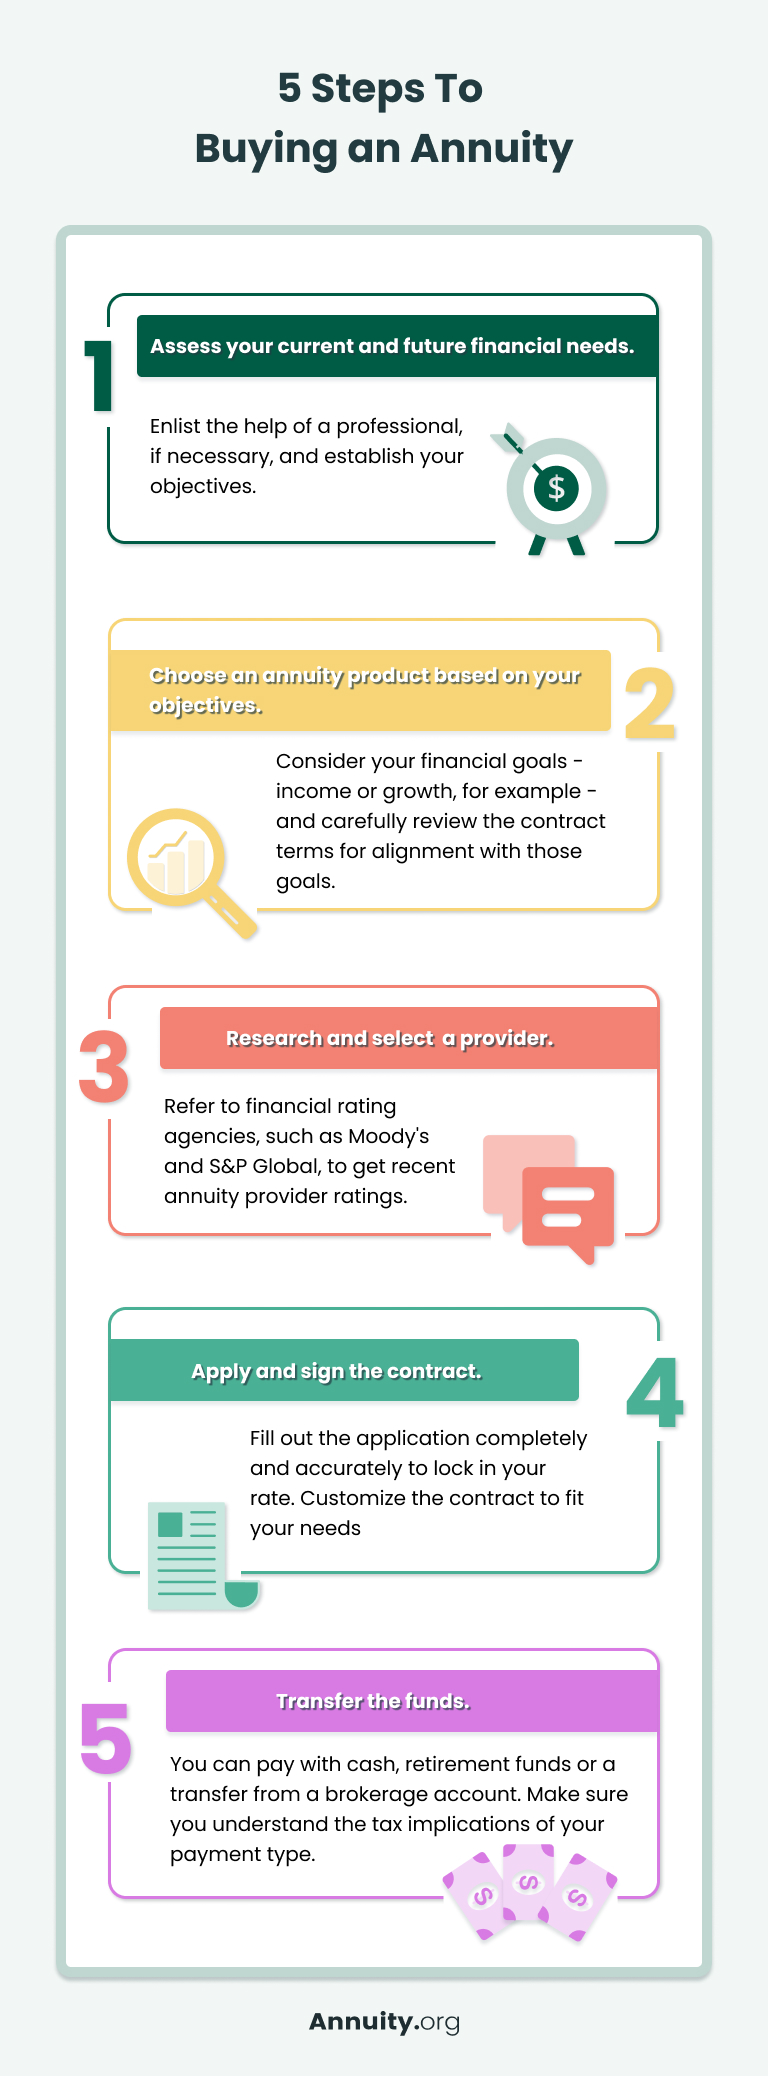
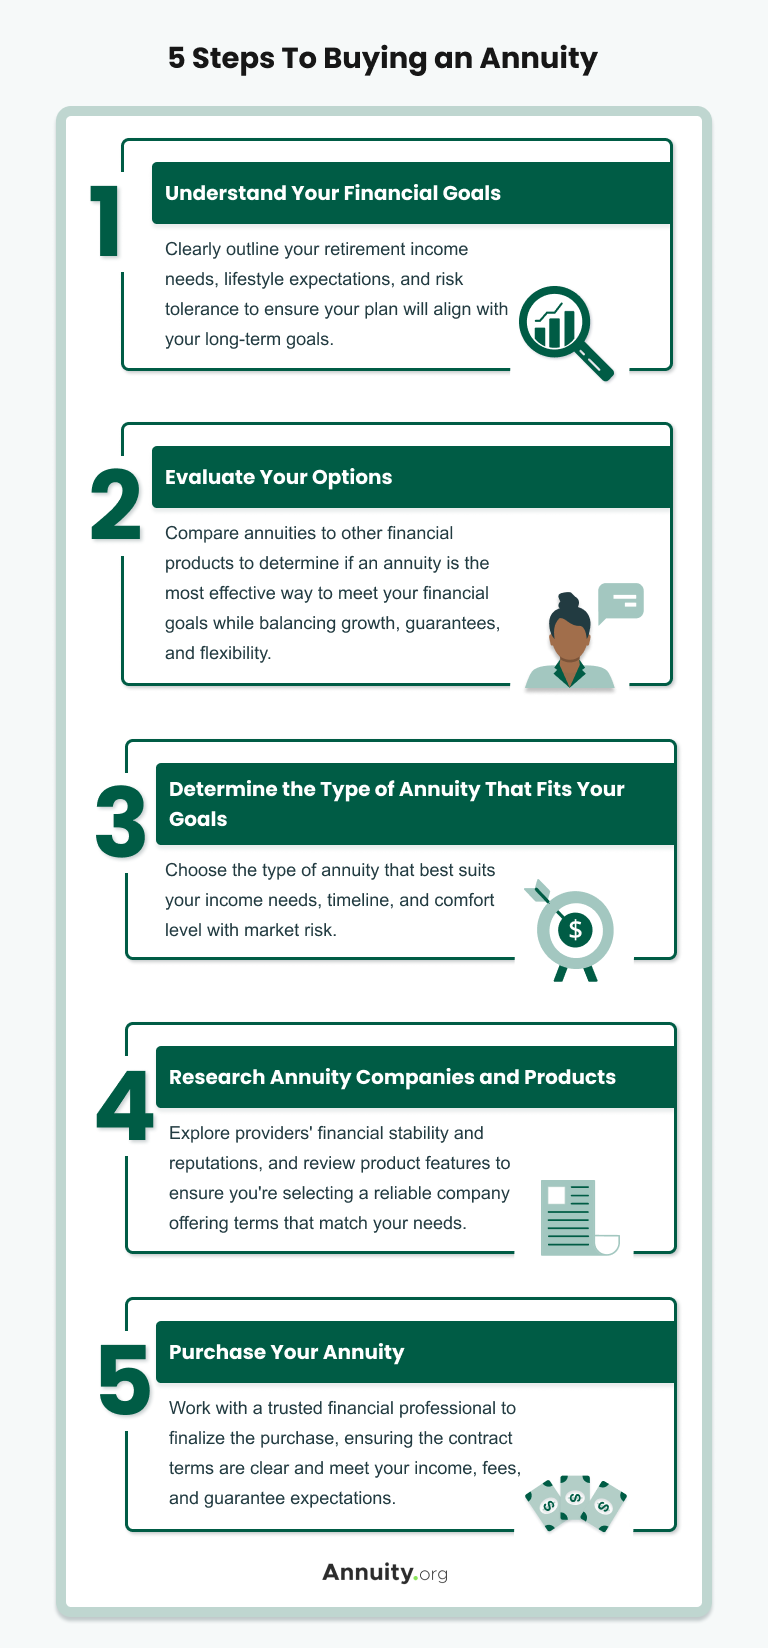
Start by pulling your own financial picture. Write down your monthly expenses, your guaranteed income sources, and the gap. Then decide what portion of your portfolio you are willing to dedicate to an annuity. Most planners suggest no more than 30 to 40 percent. Beyond that, you are sacrificing liquidity for marginal income stability that you may already have from other sources. Next, get quotes from at least three different insurance companies. Do not rely on a single broker who works with one carrier. Annuity pricing varies significantly between insurers because each uses different mortality tables and expense assumptions. A 65-year-old male might get a $60 per month higher payout from Company A than from Company B on the same $200,000 premium. That is a 3.6 percent annual difference purely from shopping around. The difference is not marketing. It is actuarial. When you receive the quote, look at the Illustration exhibit required by state regulations. This document shows projected values under different scenarios. Compare the guaranteed column against the non-guaranteed column. Most variable annuity illustrations will show a "projected" value that assumes 5 to 7 percent annual returns. The guaranteed value is often 30 to 50 percent lower. The guaranteed number is the one that actually matters for planning purposes. If the guaranteed payout does not cover your essential expenses, the product is not solving your problem.
Check the surrender charge schedule before signing anything. A typical schedule starts at 7 to 10 percent in year one and drops by about 1 percent each year until it reaches zero around year seven or eight. If you need access to that money for an emergency in year three, you could lose thousands. I once reviewed a contract where the surrender charge was 7 percent in year one but only dropped to 5 percent by year five, then flatlined at 5 percent for the entire duration. The product had no true liquidity point. That is a red flag that deserves a second look at the alternatives. Consider whether a single premium immediate annuity or a deferred annuity fits your timeline better. SPIAs convert your money into income right away. Deferred annuities let your money grow for a period before payouts begin. If you are 50 years old and not retiring for another 15 years, a deferred annuity makes more sense because your money has time to accumulate and the annuity factor will be more favorable when you are older. If you are 70 and need income now, a deferred annuity delays payments you could be receiving and often results in a lower total payout due to fewer years of accumulation.

Common Mistakes That Cost People Real Money
The most expensive mistake I see is buying a variable annuity with a guaranteed minimum income benefit rider and then holding it for 15 years without ever adjusting the allocation. The rider guarantees a lifetime payout based on the highest account value at purchase or on subsequent anniversaries, whichever is higher. The problem is that the rider costs extra, and the underlying fund choices within the annuity often have high expense ratios. Over time, the fees drag down performance while the rider promise remains theoretical because you never actually annuitize. The workaround is to set a calendar reminder three years before the surrender charge period ends to review whether converting to a systematic withdrawal or annuitizing makes more sense than continuing to pay for the rider. Another mistake is ignoring the tax implications of annuity distributions. Annuity earnings are taxed as ordinary income when withdrawn, not at the lower capital gains rate. If you have a choice between holding an investment inside an annuity or in a taxable brokerage account, the taxable account often wins for assets that appreciate significantly because of the preferential tax treatment on long-term capital gains. Annuities are better suited for assets that generate ordinary income, like bonds or certificates of deposit, where the tax deferral provides actual value rather than just deferring a worse tax outcome. Some people buy annuities with riders that guarantee a minimum death benefit to pass money to heirs. This sounds smart until you calculate the total cost of the rider over the expected lifespan of the annuitant. A guaranteed minimum accumulation benefit rider might cost 0.50 to 1.00 percent annually. On a 20-year horizon, you could pay 10 to 20 percent of your original premium in rider fees alone. If the annuitant lives to 90, the rider pays for itself many times over because the income guarantee kicks in. If the annuitant dies in year five, the rider provided a death benefit but the total cost was still substantial relative to the benefit received. There is no one-size-fits-all answer here, which is why the calculation matters.
When an Annuity Is the Wrong Answer Entirely
If you are under 50 years old and considering an annuity, stop and reconsider. The primary benefit of an annuity is longevity insurance, and you are too young to need that protection. Your money has decades to grow in a taxable or tax-advantaged account where you retain full liquidity and benefit from lower tax rates on gains. An annuity at your age locks away capital that could compound significantly over 20 or 30 years. The opportunity cost is real and usually understated in sales presentations. If you already have a pension or strong Social Security benefits that cover your essential expenses, an annuity adds little value. You are paying for insurance against a risk you do not have. The mortality credits embedded in an annuity are valuable precisely because they protect against outliving your income. If your income is already guaranteed from other sources, those credits are wasted on you. If you have high-interest debt above 6 or 7 percent, an annuity is almost certainly a bad move. Paying off debt at those rates gives you a guaranteed return that an annuity cannot match. A fixed annuity offering 4 percent does not beat a credit card balance charging 18 percent. This sounds obvious but I have seen it happen repeatedly, especially among people who received a windfall and wanted to "secure their future" without addressing the debt problem first.
What to Look for in a Reputable Annuity Product
Check the financial strength ratings of the insurance company from A.M. Best, Standard & Poor's, and Moody's. You want an A rating or above from at least two of these agencies. Annuities are long-term contracts that may not pay out for 20 or 30 years. The financial stability of the issuer matters enormously. A downgrade from A to BBB can trigger margin calls on institutional buyers and reduce the pool of interested purchasers, which can compress the secondary market value of existing contracts. The risk of default is low for highly rated insurers but it is not zero, and it compounds over long time horizons. Look for contracts that offer conversion options without penalty. Some annuities allow you to convert from a variable to a fixed product during the accumulation phase if you become more risk-averse as you approach retirement. Others lock you into the original product structure for the entire term. Flexibility has real value, especially in an environment where interest rates and market conditions shift unpredictably. Read the section on partial surrenders and free withdrawations. Most annuities allow you to withdraw 10 percent of your premium annually without surrender charges after the initial contract period. Some insurers offer more generous terms. If you need access to occasional large sums for medical expenses or home repairs, this provision matters. A contract that allows only a 5 percent annual free withdrawal with a 10 percent surrender charge on excess amounts can trap you in undesirable situations.

The tax reporting on annuities uses something called the LIFO method, which means the IRS treats any withdrawal as coming from earnings first before principal. Since earnings are taxed as ordinary income, even a small withdrawal can create a significant tax bill if your annuity has grown substantially. This is fundamentally different from how taxable investment accounts work, where you can sell specific shares and realize gains on only those shares. With an annuity, every dollar you pull out first clears out the accrued gain. Planning your withdrawal strategy around this rule can save you thousands in unexpected tax liability. Annuities are not scams. They are legitimate financial products that serve a real purpose for the right person at the right time. The problem is that they are sold by people who earn commissions on the sale, and their incentives are not perfectly aligned with yours. Read the contract. Compare multiple quotes. Calculate the total cost including fees and riders. And above all, make sure you actually need the product before you buy it. If you can cover your essential expenses from other sources, you probably do not need an annuity. If you cannot, it might be the most important decision you make for your financial security in later years.