How to Actually Use an Investments Guide Without Losing Your Shirt
I spent about three years managing my own portfolio before I bothered to read anything structured on the subject. That was a mistake. Most people skip the basics because they think they already know how it works. They don't. An Investments Guide isn't just a list of stocks to buy. It's a framework for deciding what not to do, and that distinction matters more than anything else. Here's the thing nobody tells you about investment research: most of the free content out there is written by people who make money from clicks, not from returns. When I first tried to follow a random guide I found online, I ended up in a position that lost 22% in four days. Not because the market was volatile. Because the strategy was built around a metric that barely correlates with actual performance. I had to liquidate at a loss just to stop the bleeding. That's why I started cross-referencing everything. Here's how I approach building a solid investment plan from scratch.
What an Investments Guide Should Actually Cover
A proper Investments Guide starts with risk assessment, not stock picks. You need to answer three questions before you put a single dollar anywhere: How much can you lose without it changing your life? What timeline are you working with? And what happens if your main income source disappears tomorrow? I used to ignore the third question. I got burned when my contract work dried up during a sector downturn. Had I answered it honestly, I would have kept more in liquid reserves and less in long-duration assets. That mistake cost me about eight thousand dollars in opportunity cost alone, but the real cost was emotional. Watching your emergency fund get tapped while markets are down is a specific kind of stress that most guides don't prepare you for.
Core Concepts You Need Before Doing Anything Else
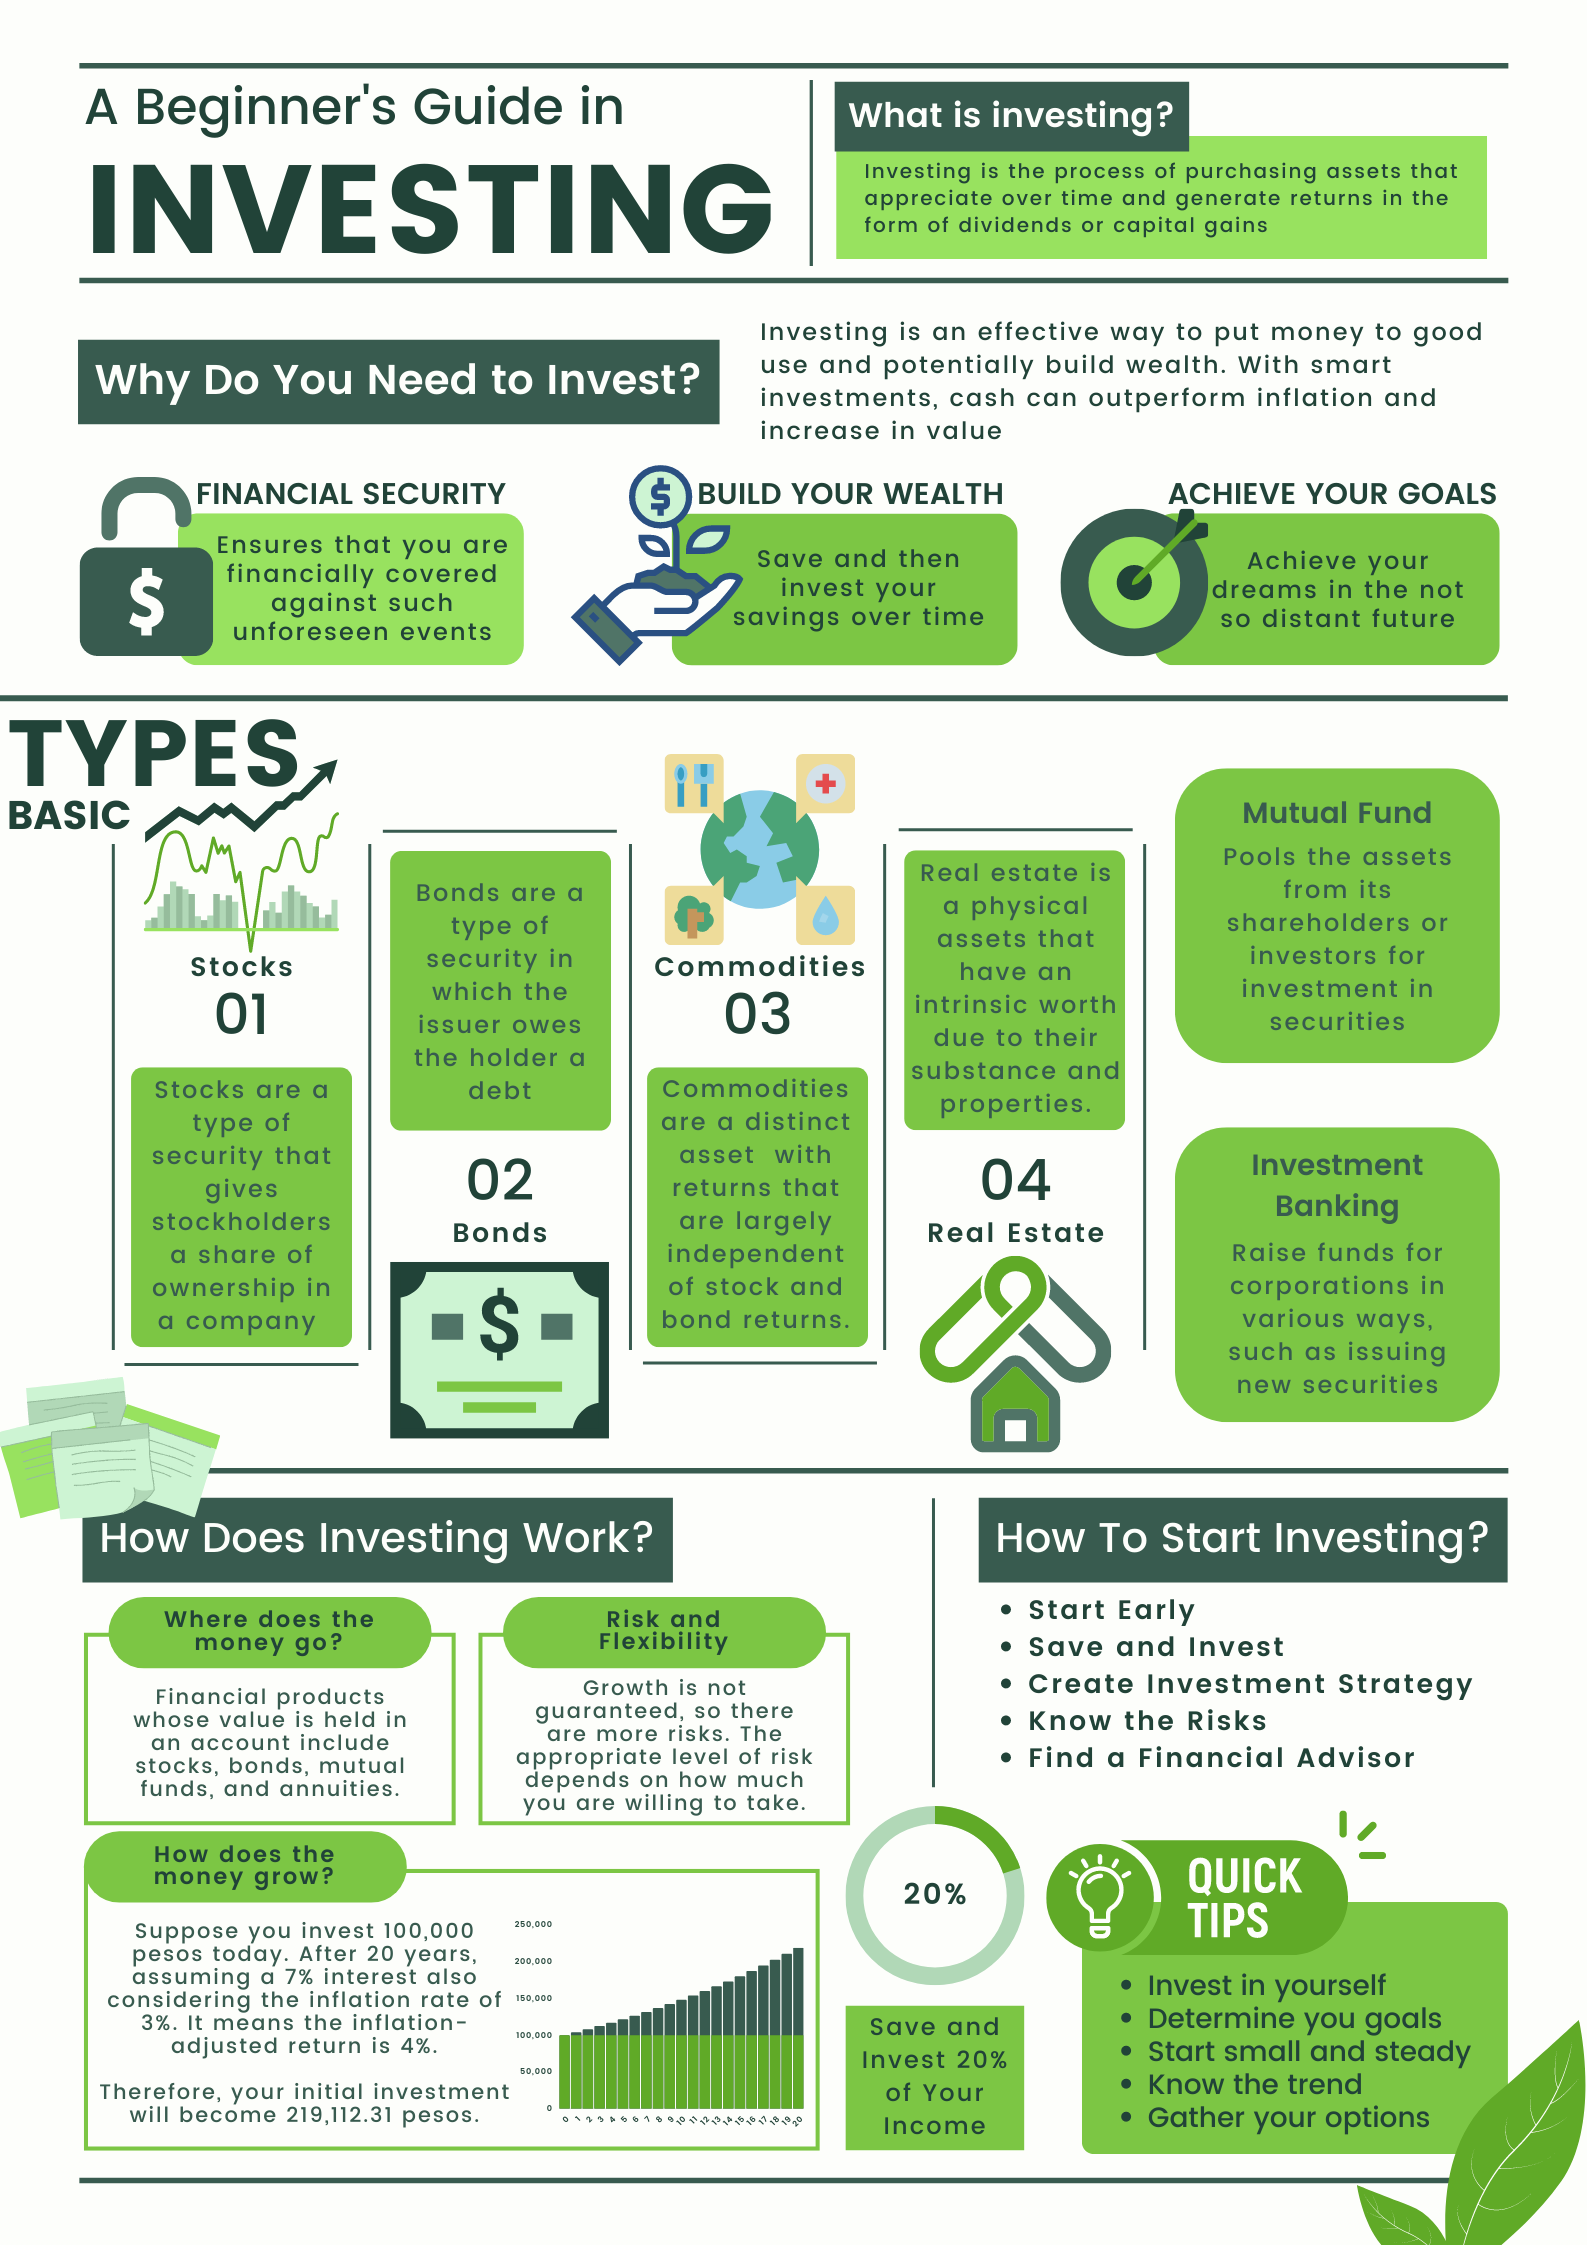
Diversification gets thrown around like a buzzword. Real diversification means your holdings don't move in the same direction when something goes wrong. If you own five tech stocks and call it diversified, you're not diversified. You're just concentrated with extra steps. Asset allocation is your actual steering wheel. The ratio between equities, fixed income, and alternatives determines more of your return than anything else. Studies from Bridgewater and Vanguard both show that over 90% of portfolio variance comes from allocation decisions, not security selection. That number sounds too clean to be true, but it's been consistent across decades of data. Expense ratios are where most people quietly lose money. A fund charging 0.75% instead of 0.05% looks identical on a chart for a few years. Then compounding works against you. Over twenty years, that 0.70% difference can eat up nearly a third of your potential gains. I see people pick active funds because they "feel" safer. They're paying for something they're not getting.
Get the Full Details

The Practical Workflow I Use
Step one: define your time horizon. Money you need in under three years does not go into equities. Period. I've seen too many people put their down payment for a house into an index fund and then panic-sell when it drops during a correction. The money wasn't invested poorly. The timeline was wrong. Step two: pick your core holdings. I use broad market ETFs for the bulk of my equity allocation. VTI for total US market exposure. VXUS for international. The boring stuff. These have low fees, high liquidity, and enough diversification that individual stock picking becomes optional rather than necessary. I allocate about 80% of my equity portion here and leave the rest for targeted positions. Step three: set rebalancing rules. I review my allocations quarterly. If any asset class drifts more than five percentage points from its target, I rebalance. This forces you to sell what went up and buy what went down, which is the opposite of natural human instinct but the opposite of emotional investing.
Step four: automate contributions. Dollar-cost averaging removes timing risk. I set up automatic transfers on the first of each month. The exact amount doesn't matter as much as the consistency. Skipping months because the market "looked expensive" is how people miss rallies. The S&P 500 has returned an average of about 10% annually over the long run, but that average is distorted by a handful of massive up years. Missing just ten of the best days in a twenty-year period cuts your return roughly in half. Automation makes it harder to miss those days.
Where Most People Go Wrong
The biggest mistake I see is confusing a bullish sentiment with a sound strategy. When everyone is talking about a particular sector, it's usually too late to enter on favorable terms. I watched a friend put half his portfolio into AI-themed funds in early 2024. The sector did well. But he bought at peak valuation multiples that made the risk-reward asymmetrical. He needed the stocks to keep rising 40% just to offset a typical correction. That's not investing. That's hoping. Another common failure mode is over-trading. Every trade has costs beyond fees. There's the spread, the tax hit, and the opportunity cost of capital tied up in analysis that could have been deployed elsewhere. I used to spend hours each week researching individual positions. The returns from that effort were indistinguishable from random noise after accounting for transaction costs and taxes. I cut my research time by about 90% and actually improved my returns.

When This Approach Fails
This framework assumes you have a stable income and an emergency fund. If you're carrying high-interest debt while trying to invest, you're doing it backwards. The math doesn't work. Paying off 20% credit card debt gives you a guaranteed 20% return. No investment in existence offers that level of certainty. I had a client who was contributing to a brokerage account while carrying three-figure interest rates on business debt. I told him to stop investing until the debt was cleared. He didn't listen. Six months later, the debt had doubled. The lesson was painful but clear. The approach also breaks down in concentrated situations. If most of your wealth is tied up in a single employer's stock, adding more diversified investments won't solve the problem. You need a separate strategy for managing that specific risk, usually involving gradual selling and tax planning. This guide doesn't cover that. It's worth finding someone who specializes in that niche.
Resources I Actually Trust
For foundational material, I go back to Bogle's The Little Book of Common Sense Investing. It's not exciting. It's also correct. For ongoing reference, I check Morningstar's fund analysis and the SEC's investor publications. Neither is glamorous. Both are reliable. If you're looking for a more hands-on Investments Guide, the spreadsheet model I use is available through my website. It walks through allocation calculations, rebalancing triggers, and tax-loss harvesting timing. It's not complicated. It takes about twenty minutes to set up and maybe five minutes per quarter to maintain. I've updated it with current fee benchmarks and tax bracket thresholds for 2025.
The Bottom Line
Investing isn't hard. It's uncomfortable. The strategy works as long as you stick to it during periods when it feels wrong. That's the part that filters out most people. The math rewards patience and punishes drama. I wish I'd learned that five years earlier.